
Take Two Interactive Software (TTWO) Following Its Microsoft Xbox Deal And The Valuation Debate
Take-Two Interactive Software (TTWO) has just reset its relationship with Microsoft through a long term Xbox Publisher License Agreement that consolidates prior deals and formalizes digital revenue sharing and physical media royalties.
Take-Two Interactive Software’s new Microsoft deal lands after a choppy run, with the share price up 2.3% over the past day and 2.2% over the week, yet down 4.2% over 30 days and 18.6% across 90 days. That short term weakness contrasts with a 48.0% three year total shareholder return, suggesting recent pressure has cooled momentum even as longer term holders have still seen gains.
Scan how other media and gaming stocks are priced against their recent moves by checking the hand picked 31 high quality undervalued stocks alongside Take-Two Interactive Software after this Microsoft agreement.
Take-Two Interactive Software now has a fresh Xbox framework and a long history of heavyweight franchises. The real tension for investors is simple: Does the current share price still make sense against that profile?
Most Popular Narrative: 25.1% Undervalued
Against the last close at $207.50, the most followed narrative pegs Take-Two Interactive Software’s fair value at $276.97, which implies a sizeable valuation gap that investors are watching closely as the Microsoft agreement reframes platform economics.
Take-Two sits at a genuinely pivotal inflection point. Over many years it has made heavy investment, including strategic acquisitions, and is approaching the moment of payoff. GTA VI could reshape its financial profile for the better half of the next decade.
See why 92 investors see Take-Two Interactive Software as 25% undervalued.
Result: Fair Value of $276.97 (UNDERVALUED)
Still, this storyline can crack if GTA VI underwhelms or slips again, or if Take-Two Interactive Software’s heavy spending fails to translate into lasting profitability.
Find out about the key risks to this Take-Two Interactive Software narrative.
Another View On Take-Two Interactive Software’s Valuation
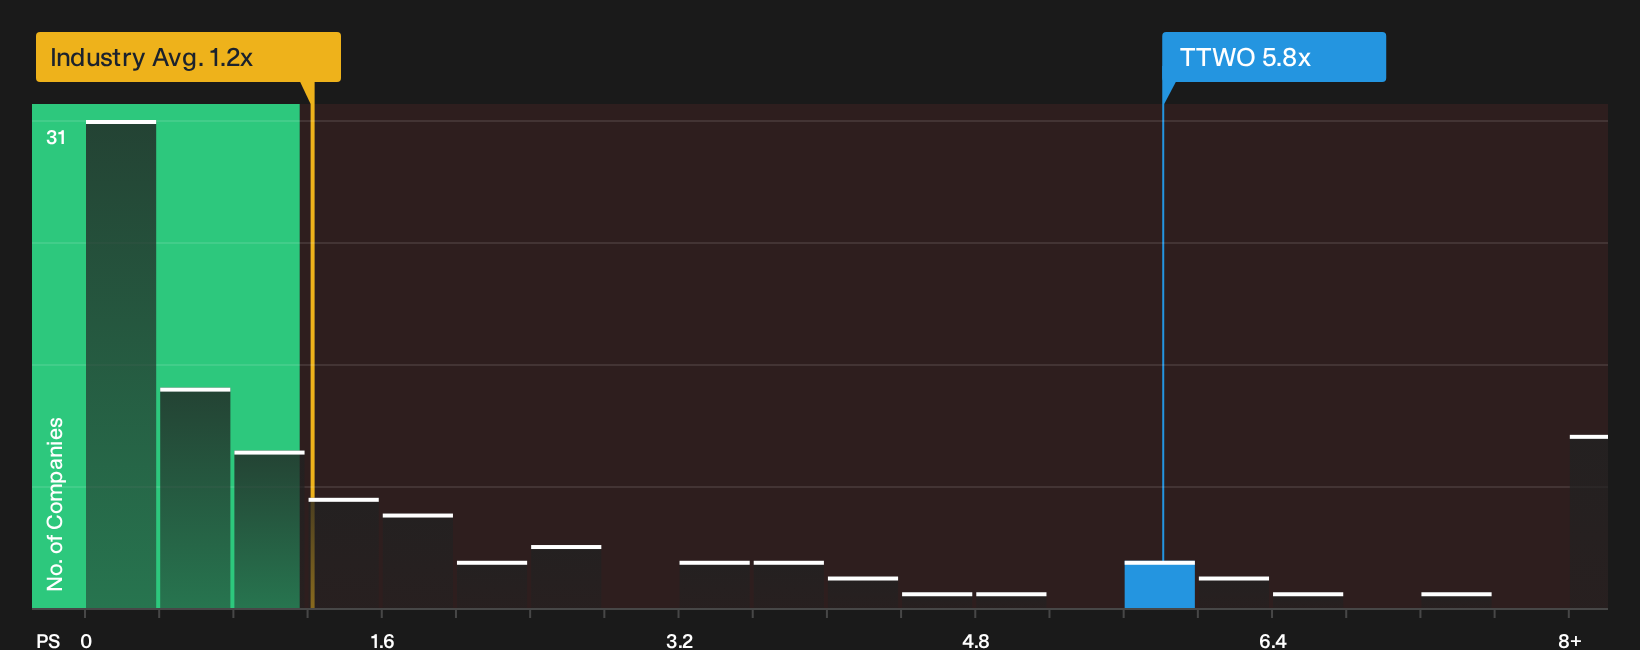
The community fair value narrative puts Take-Two Interactive Software at $276.97, which points to upside against the last close of $207.50. The market’s own pricing tells a different story. Based on a P/S of 5.8x versus a fair ratio of 3.5x, the stock screens expensive, and it also trades well above both peer and US Entertainment averages of 2.2x and 1.2x. That gap can signal room for multiples to compress if expectations cool, or for fundamentals to catch up instead. Which side of that equation do you think plays out first?
See what the numbers say about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
This mix of optimism and concern around Take-Two Interactive Software only matters if you pressure test it yourself and move before sentiment shifts. Start by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Take-Two Interactive Software?
Do not stop with Take-Two Interactive Software. Use the Simply Wall St tools to scan fresh ideas efficiently and keep your watchlist stacked with high conviction candidates.
- Hunt for potential value gaps by checking the 31 high quality undervalued stocks that filters for quality companies trading below their estimated worth.
- Prioritize resilience and capital protection by reviewing the 31 resilient stocks with low risk scores that highlights businesses with stronger risk profiles.
- Target financial strength first by working through the list of solid balance sheet and fundamentals (25 results) that focuses on companies with healthier balance sheets and fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com