
Casey's General Stores (CASY) Joins FTSE All World Index On Questions Over Value
Casey's General Stores (CASY) has been added to the FTSE All-World Index (USD), a global benchmark that often draws attention from index tracking funds and long term institutional investors.
Recent trading has been choppy for Casey's General Stores. The share price is down about 20.7% over the past 30 days and roughly 23.7% over 90 days, yet the year to date share price return of 9.4% and a 5 year total shareholder return of 230.1% indicate that longer term momentum remains positive.
Scan beyond Casey's General Stores and line up other potential index beneficiaries with the hand picked 31 high quality undervalued stocks that combine resilient balance sheets with shareholder focused fundamentals.
After a sharp pullback, Casey's General Stores now sits between two stories. Has the recent slide already absorbed most of the good news, or is meaningful upside still on the table as investors reassess what the business is worth?
Most Popular Narrative: 23% Undervalued
Against the last close of $608.46, the most followed narrative for Casey's General Stores pins fair value at roughly $790.53. This frames the recent pullback as a valuation reset rather than a broken story.
Continued store expansion, including integration of the Fikes/CEFCO acquisition and plans for ongoing new unit growth in underpenetrated rural and Midwestern markets, positions Casey's to leverage population influx to these regions and drive sustained top-line revenue growth.
Progress toward converting and remodeling acquired stores for Casey's full food/kitchen model creates a future catalyst for gross margin expansion and synergy capture, with expected benefits becoming more pronounced in the following fiscal year and supporting multi-year EPS growth.
See why 21 investors see Casey's General Stores as 23% undervalued.
Result: Fair Value of $790.53 (UNDERVALUED)
Still, Casey's General Stores faces real pressure if fuel volumes weaken faster than expected or if regional slowdowns in its core Midwest and Texas markets become more severe.
Find out about the key risks to this Casey's General Stores narrative.
Another View on Casey's General Stores Valuation
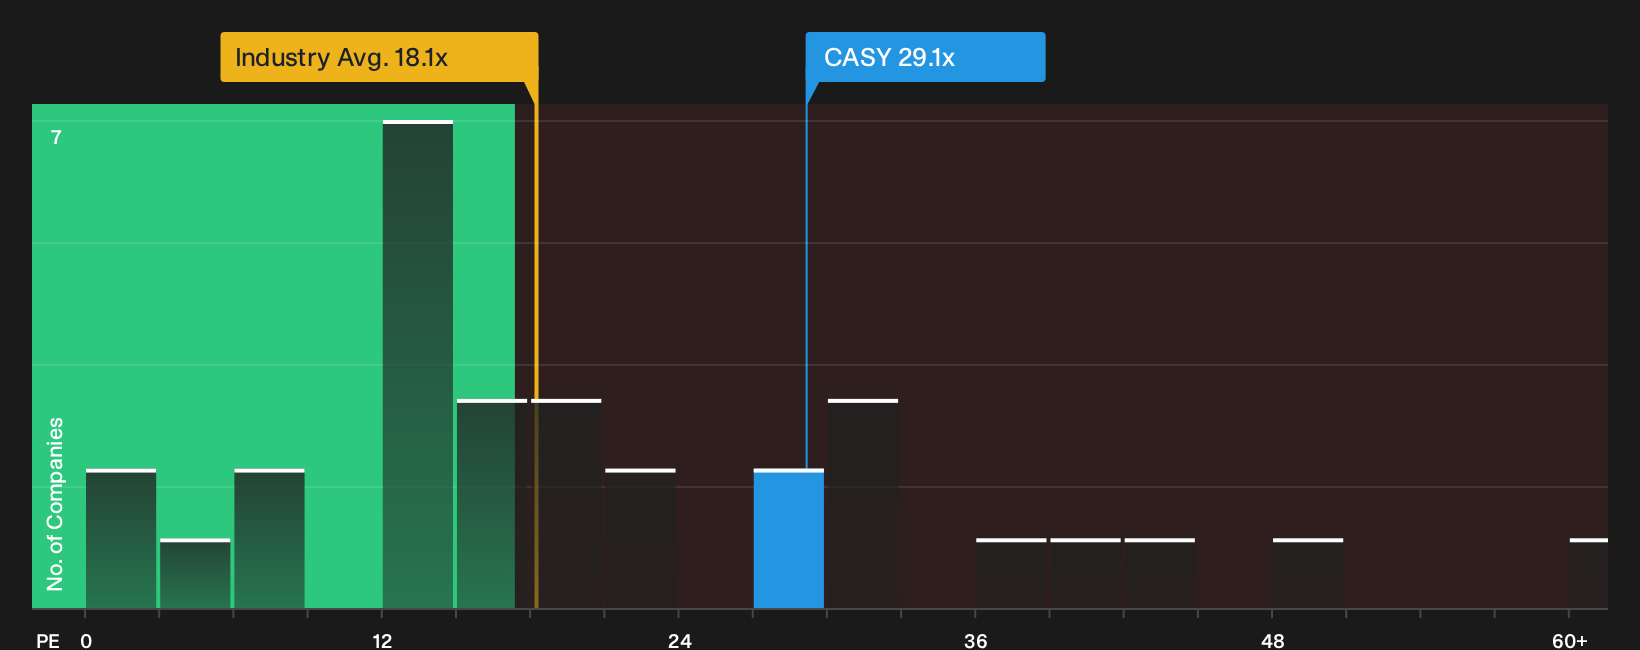
The earlier fair value work pointed to Casey's General Stores trading below modeled worth. The P/E story is less forgiving. CASY changes hands at about 29.1x earnings compared with 18.1x for the US Consumer Retailing sector, above a fair ratio of 23.5x, even though the figure sits beneath a 37.8x peer average. That gap hints at real valuation risk if sentiment cools. The question is which yardstick you consider most informative.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Casey's General Stores story so far. If you want to move quickly and form your own view, start by weighing its 4 key rewards and 2 important warning signs.
Looking for more Casey's General Stores sized ideas?
If Casey's General Stores has you rethinking what belongs in your portfolio, do not stop here. Use the same discipline to hunt for your next edge.
- Target dependable cash generators by scanning a 7 dividend fortresses that prioritizes income strength alongside balance sheet resilience.
- Spot resilient potential by filtering a 31 resilient stocks with low risk scores focused on sturdier operations with lower overall risk profiles.
- Get ahead of the crowd through a 19 high quality undiscovered gems built around underfollowed businesses with strong underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com