
NRG Energy (NRG) Stock Looks Cheap With Earnings In Focus
NRG Energy has seen a sharp pullback over the past year after a strong multiyear run, which puts fresh focus on whether the current share price is still in line with what its earnings can support. With the stock now around US$95.65, the key issue for you is how that tag stacks up against what the business actually earns.
- Over the past 3 years, NRG Energy has delivered a return of 169.8%, which raises the question of whether the earnings profile has kept pace with that kind of share price change.
- The group’s value case now rests heavily on the quality and stability of its earnings, including how reliably it can convert those profits into cash after covering capital needs in a capital intensive power business.
- The analysts covering NRG Energy have run their own numbers. See what analysts think NRG Energy's shares could be worth.
The stock’s next move may depend on whether NRG Energy’s current earnings are strong and resilient enough to justify today’s valuation.
If you want more context around whether NRG Energy’s earnings profile justifies this valuation, compare it with other companies using the 31 high quality undervalued stocks
Does NRG Energy Look Undervalued on Earnings?
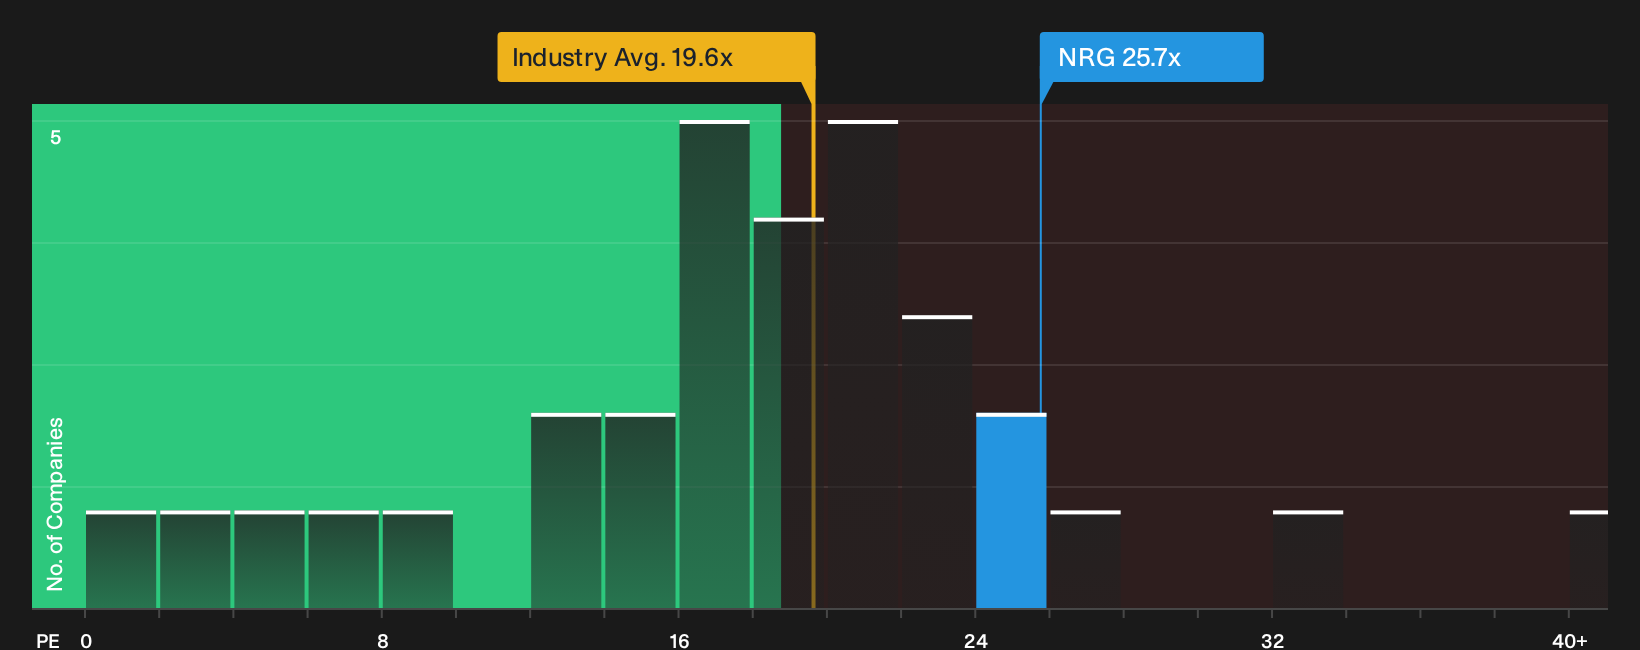
The P/E ratio suits NRG Energy because earnings remain the main anchor for how investors look at a mature utility. At around 25.7x earnings, the stock trades above the Electric Utilities industry average of about 19.6x and also above a peer group average near 15.3x, so the market is clearly placing a richer price tag on each dollar of profit.
The fair multiple that a fundamentals based model suggests for NRG Energy is higher than the current P/E. This points to the shares screening as undervalued on this earnings yardstick even after the strong run in recent years. That gap indicates the present price does not fully reflect what the model assumes about the company’s profitability profile, capital needs and risk characteristics. Anyone looking at the stock through a pure earnings lens would likely compare this P/E with the detailed fair value work behind that estimate. Explore the numbers behind NRG Energy's P/E valuation.
The NRG Energy Narrative: What Would Justify Today's Price?
For investors trying to reconcile NRG Energy's current P/E with its fundamentals, Simply Wall St Narratives act as the missing link by explaining which potential paths for future growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than today’s price. Each narrative treats its fair value as a thesis about NRG Energy's business that can be tracked over time rather than as a one-off snapshot, and all of them are hosted on Simply Wall St's Community page.
One of the top community narratives on NRG Energy: 20% undervalued
"The main thing that has to go right is that NRG Energy converts its customer-backed pipeline and BYOP model into long-duration, contracted projects at targeted returns..."
Discover why this Narrative puts NRG Energy at 20% undervalued.
The NRG Energy share price is only one piece of the decision
Even if NRG Energy’s earnings and valuation line up for you, the research also flags specific risk checks that deserve attention before any decision. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com