
Camtek (CAMT) Sees $600 Million In Orders, Is The AI Upside Priced In?
Camtek (NasdaqGM:CAMT) is drawing fresh attention after management outlined more than $600 million in order visibility through 2027, along with the acquisition of Visual Layer to build out AI-driven software revenue streams.
Recent trading has been strong, with Camtek’s share price delivering a 21.2% 1 month return and a 34.4% year to date share price gain. The 3 year total shareholder return of about 1.6x suggests momentum has been building over a longer stretch as investors reassess growth potential and risk around its semiconductor exposure and new AI software push.
Scan other potential beneficiaries of the same semiconductor and AI tailwinds that are driving Camtek by reviewing our curated list of 90 AI infrastructure stocks.
Camtek has already rewarded early believers, yet a US$7.2b valuation and US$155 share price still sit against fresh order visibility and a new AI software push. How much of that story is now reflected in the multiples?
Most Popular Narrative: 17% Undervalued
Against Camtek’s last close at $155.25, the most followed narrative pegs fair value at $187.25, implying upside that rests on very specific AI and advanced packaging assumptions rather than broad market enthusiasm.
Accelerating demand for high-performance computing (HPC) and AI-driven applications is expanding the need for advanced packaging, micro-bump, and hybrid bonding inspection, directly growing Camtek's total addressable market and supporting multi-year revenue growth.
Rapid customer adoption of newly launched Hawk and Eagle G5 platforms, which address evolving requirements such as smaller defect detection and higher throughput, are expected to drive both incremental revenue and gross margin expansion as customers prioritize advanced features and process future-proofing.
See why 35 investors see Camtek as 17% undervalued.
Result: Fair Value of $187.25 (UNDERVALUED)
Still, Camtek’s heavy exposure to Asian customers and direct competition with larger rivals like KLA could quickly challenge today’s AI driven optimism if spending or market share changes.
Find out about the key risks to this Camtek narrative.
Another View: What Camtek’s Multiples Are Saying
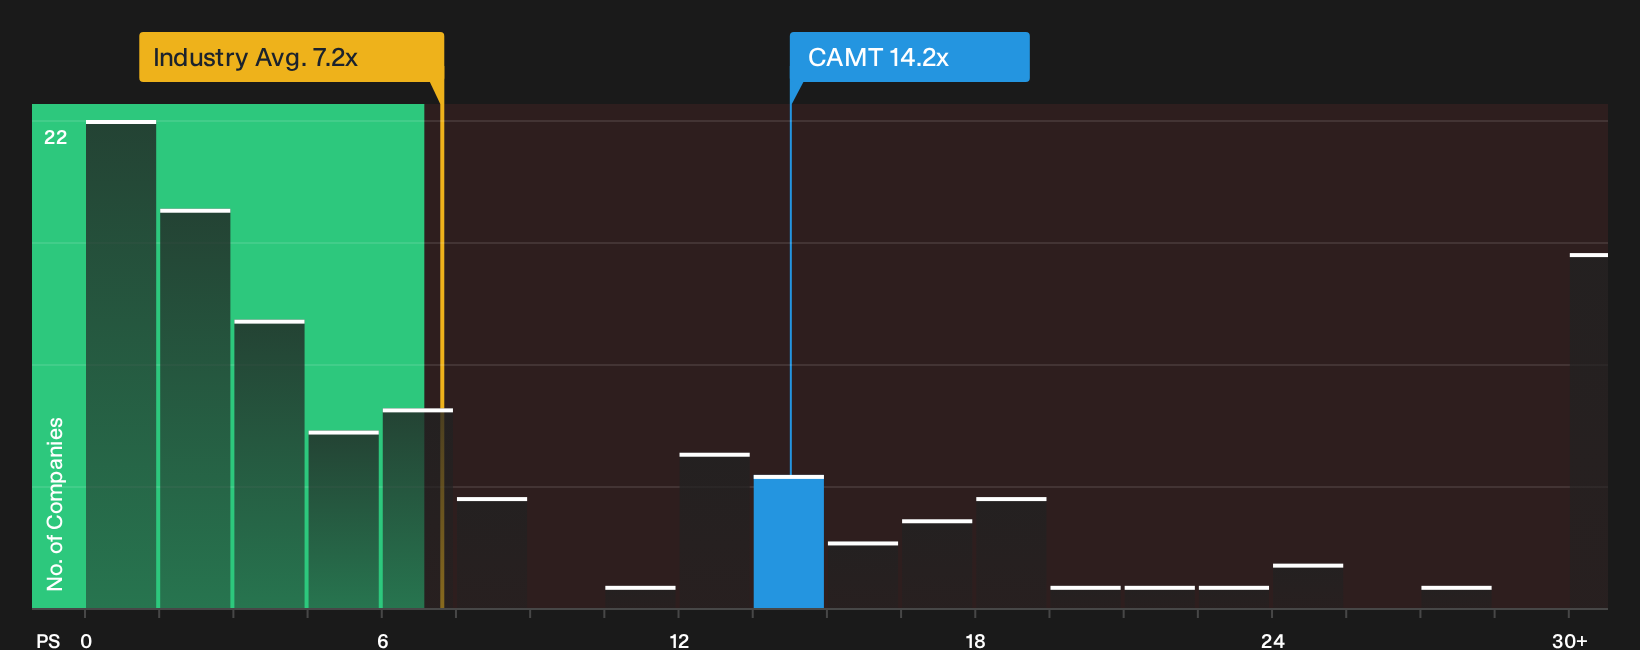
Market-based signals tell a very different story from the analyst narrative. Camtek trades on a P/S ratio of 14.2x, which is rich versus the US Semiconductor industry at 7.1x and also well above a fair ratio of 6.1x that the market could move toward over time. Even though the stock screens cheaper than its closest peers on the same metric at 17.8x, that gap still leaves investors paying a heavy premium for forecast growth and AI-driven upside. The question is simple: How comfortable are you paying more than double the sector multiple when execution risk and cyclicality are still on the table?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Camtek after all that data and narrative tension. Step in quickly, review the underlying figures, and balance the 1 key reward and 3 important warning signs.
Looking For More Investment Ideas Beyond Camtek?
If Camtek has your attention, do not stop here. Use the same structured approach to spot other clear setups before the crowd catches on.
- Target resilient balance sheets by reviewing a curated list of solid balance sheet and fundamentals (25 results) that filters for financial strength and underlying fundamentals, not just share price excitement.
- Hunt for mispriced quality through the 31 high quality undervalued stocks and compare potential upside with the risks you are already weighing in Camtek.
- Lock in potential income streams by checking the 7 dividend fortresses that focuses on higher yielding companies where payouts and durability both matter.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com