
China Resources Beverage (SEHK:2460) Stock Looks Expensive As Shares Fell 29%
China Resources Beverage (Holdings) stock has had a difficult run, and that raises a basic question for you as an investor. Is the current share price still aligned with what the business earns, or have earnings and valuation drifted apart?
- The share price has fallen 29.3% over the past year, which puts the focus squarely on whether that move now matches the strength of its earnings.
- For a consumer beverages group that relies heavily on steady cash generation and brand-driven volumes, any shift in profitability or reinvestment needs can materially change what a fair earnings-based valuation looks like.
- The analysts covering China Resources Beverage (Holdings) have run their own numbers. See what analysts think China Resources Beverage (Holdings)'s shares could be worth.
The issue now is whether China Resources Beverage (Holdings) stock is priced in line with what its earnings justify today.
To pressure test whether China Resources Beverage (Holdings) is the only consumer stock where earnings and share price seem out of sync, line it up against the 191 high quality undervalued stocks.
Is China Resources Beverage (Holdings) Getting Expensive on Earnings?
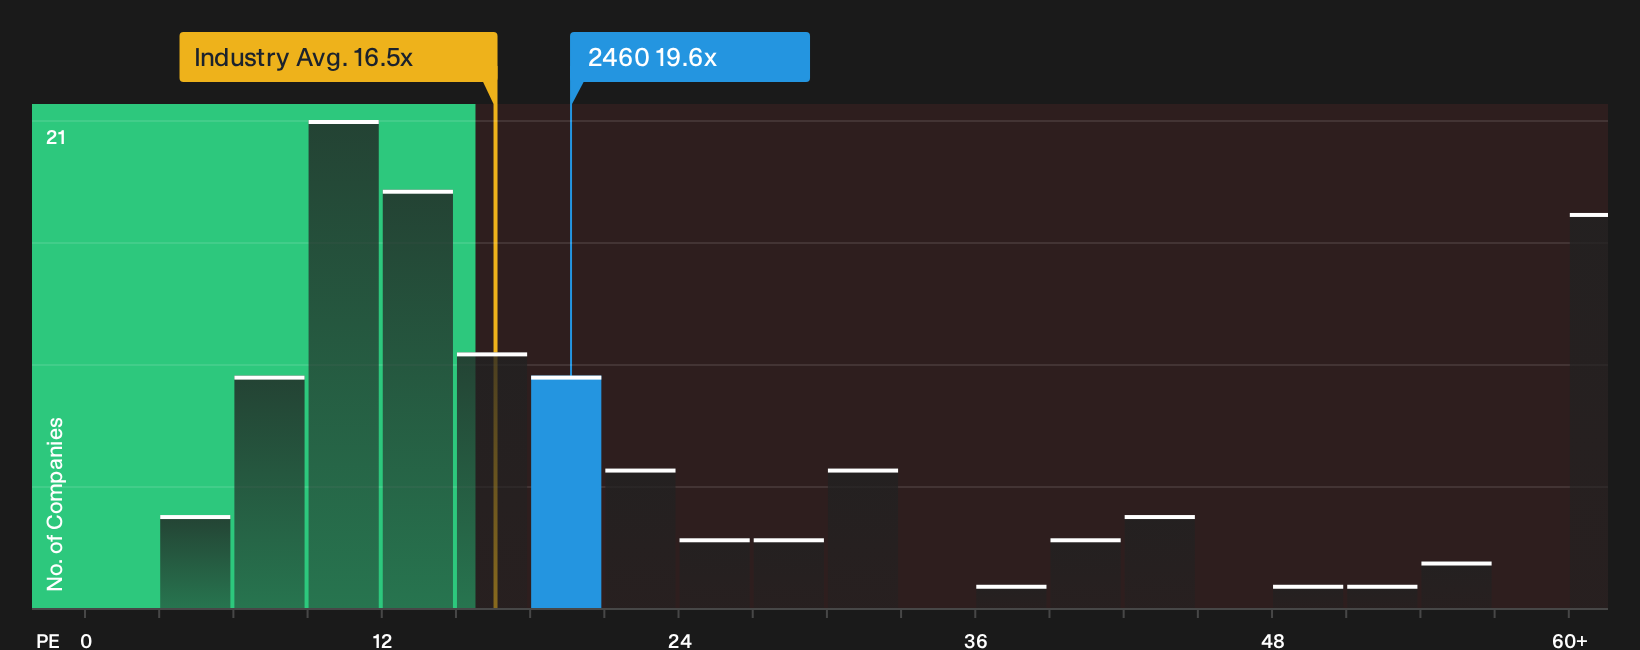
P/E is usually the cleanest way to think about China Resources Beverage (Holdings) because earnings matter more than asset values for a branded drinks group. Right now the stock trades on a P/E of 19.6x, which sits above the Beverage sector average of 16.5x and below the peer group mark of 23.7x. In other words, the market is asking you to pay more than the sector baseline but not the richest price in its peer set.
The tailored fair-value multiple for China Resources Beverage (Holdings), which factors in its own growth profile, margins, size and risk, points to a lower P/E than the current 19.6x. That gap suggests the shares screen overvalued on this earnings yardstick, so you would want strong conviction about the quality and durability of its profits to justify paying this kind of earnings premium. Explore the numbers behind China Resources Beverage (Holdings)'s P/E valuation.
The China Resources Beverage (Holdings) Narrative: What Would Justify Today's Price?
For China Resources Beverage (Holdings), Simply Wall St Narratives pick up where this valuation puzzle leaves off and explain which specific paths for growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price on the Community page. Each Narrative links its number to a clear view on how China Resources Beverage (Holdings)'s growth, margins and risks could evolve, which you can then revisit as new information becomes available.
A clear, number-driven Narrative on China Resources Beverage (Holdings) gives you a way to lock in your expectations on growth, margins and execution, and then judge them against what actually happens over time. It turns a loose view about the business into a set of concrete assumptions that can be updated as fresh results come through.
Share your own Narrative for China Resources Beverage (Holdings) and set out the assumptions behind your valuation.
Before focusing only on valuation, China Resources Beverage (Holdings) has other checks to review
Price and earnings only tell part of the story for China Resources Beverage (Holdings), because separate fundamental checks have flagged potential issues that deserve your attention before you act. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com