
Is Aecon Group (TSX:ARE) Fairly Valued On Its New Pickering Contracts?
Aecon Group stock reaction to new Pickering contracts
Aecon Group (TSX:ARE) is back in focus after announcing its joint venture and consortium have secured Pickering Nuclear Generating Station refurbishment work worth $3b, with Aecon’s share at $1.75b.
The new commitments are set to flow into Aecon’s Construction segment backlog in the third quarter of 2026, tying the contractor even more closely to Ontario’s long term clean electricity plans.
Recent trading suggests momentum has picked up for Aecon Group, with a 1-month share price return of 24.57% and a year to date share price gain of 71.64%. The 1-year total shareholder return of 120.38% points to a strong rerating over a longer stretch as investors react to contract wins like Pickering and reassess both growth potential and project risk.
Scan other infrastructure players riding similar contract momentum with our hand picked 39 power grid technology and infrastructure stocks.
Aecon Group has just sprinted higher on the Pickering win, which leaves you choosing between paying up for momentum now or waiting for a pullback that may not come. So what does the current valuation actually say?
Most Popular Narrative: 3.7% Undervalued
The most followed narrative currently pegs Aecon Group’s fair value at CA$56.20, slightly above the last close of CA$54.10. This frames the recent Pickering move as a modest premium to what analysts see in their long term models.
Aecon's strategic pivot toward a higher mix of collaborative, non-fixed price contracts (now 76% of backlog) and recurring revenue segments like utilities and concessions is improving earnings quality and margin stability, likely supporting better net margins and mitigating volatility from legacy fixed-price projects.
See why 36 investors see Aecon Group as 4% undervalued.
That narrative relies on an 8.31% discount rate and assumes annual revenue growth of around 7.5%, with net profit margins reaching just over 3% over time, to arrive at a fair value of CA$56.20. Against a CA$3.58b market cap and trailing net loss of CA$65.28m, it treats Aecon Group as a construction platform that is still early in a margin rebuild but already pricing in some of that improvement.
For you as an investor, the takeaway is that most of the recent rerating is already reflected in the narrative’s fair value, with only a small gap between the CA$54.10 share price and the CA$56.20 estimate. Analysts in this narrative still factor in earnings volatility, higher risk funding and a forecast shift from losses to profitability over the next few years.
Result: Fair Value of CA$56.20 (ABOUT RIGHT)
Still, Aecon Group’s reliance on large public infrastructure contracts and pressure on construction EBITDA margins could quickly challenge this “about right” valuation story.
Find out about the key risks to this Aecon Group narrative.
Another View: Aecon Group looks expensive on cash flows
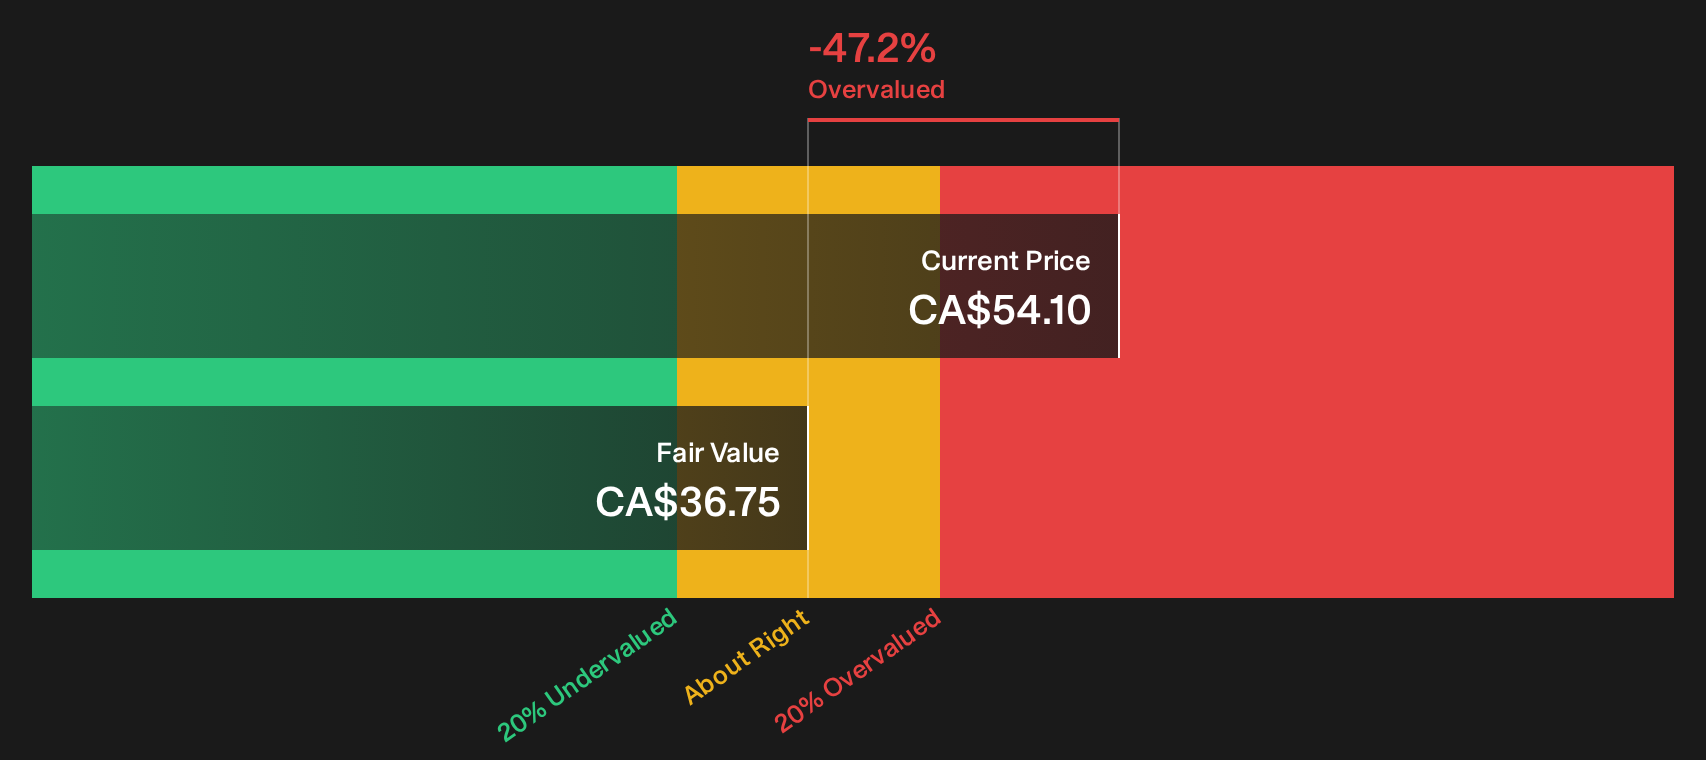
The analyst narrative frames Aecon Group as roughly fairly priced around CA$56.20, only slightly above the current CA$54.10. A different lens tells a sharper story. Our DCF model points to a future cash flow value of CA$36.75, which sits well below where the stock trades today.
That gap suggests investors are paying a meaningful premium to the SWS DCF model and leaning heavily on backlog, contracts and sentiment rather than just discounted cash flows. The question is simple: Are you comfortable paying up on the assumption that execution and margins eventually justify the higher tag?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aecon Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Aecon Group in this article, but the real test is how you weigh the upside drivers against the risks in your own research. To stress test your view against the optimistic factors already identified, review the 2 key rewards.
Looking for more Aecon Group style investment ideas?
If Aecon Group has sharpened your focus on quality and timing, do not stop here. Broaden your watchlist today and give yourself more options tomorrow.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (7 results) for companies built to handle tougher conditions.
- Hunt for quality at a reasonable price by reviewing the 7 high quality undervalued stocks that pair stronger cash generation with disciplined financial profiles.
- Seek reliable income streams by checking out 1 dividend fortresses that combine higher yields with a focus on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com