
Is Ito En (TSE:2593) Fully Valued After Its FTSE All World Index Exit?
Ito En (TSE:2593) has drawn fresh attention after being dropped from the FTSE All-World Index. This move can trigger mechanical selling by index-linked funds and prompt active investors to reassess the shares.
Recent trading has been choppy for Ito En, with a 1-day share price return of 1.37% after the FTSE removal, a 7-day share price return down 1.77%, and a 90-day share price return of 5.56%. In contrast, the 1-year total shareholder return has declined 6.36% and the 5-year total shareholder return is down 54.38%, indicating short-term momentum alongside a weaker longer-term record.
Scan how Ito En's index exit compares with other consumer stocks wrestling with similar pressures by moving through the hand-picked 17 high quality undervalued stocks in this space.
The FTSE exit, a mixed return record, and analyst targets now point in different directions. Where does fair value for Ito En really sit in that spread between the ¥3,116 price and the estimates range?
Price-to-Earnings of 83.2x: Is it justified?
On simple valuation math, Ito En looks expensive, with a P/E of 83.2x at the ¥3,116 share price even though broader analyst targets sit lower than the market quote.
The P/E ratio compares what investors are paying for each unit of earnings. For a beverage producer like Ito En it is often used as a quick gauge of how much future profit improvement the market is already baking in. A multiple this high suggests investors are assigning a rich price to current earnings, especially when stacked against the company’s own recent record.
That premium sits in sharp contrast to peers. Ito En trades at 83.2x earnings, whereas the Asian beverage industry average is 16.5x and the peer group sits at 19.8x. The firm’s estimated fair P/E of 31.1x is also far lower than the current multiple, which points to a level the market could move towards if expectations cool.
Explore the SWS fair ratio for Ito En.
Result: Price-to-Earnings of 83.2x (OVERVALUED)
Still, a prolonged disconnect between Ito En’s 83.2x P/E and its estimated fair P/E of 31.1x, along with weaker 3 and 5 year returns, could affect sentiment.
Find out about the key risks to this Ito En narrative.
Another View on Ito En’s Value
A second lens comes from the SWS DCF model. On this approach, Ito En at ¥3,116 trades well above an estimated future cash flow value of ¥263.01, which flags the shares as expensive. If both earnings and cash flow point to rich pricing, where might fresh upside come from next?
Look into how the SWS DCF model arrives at its fair value.
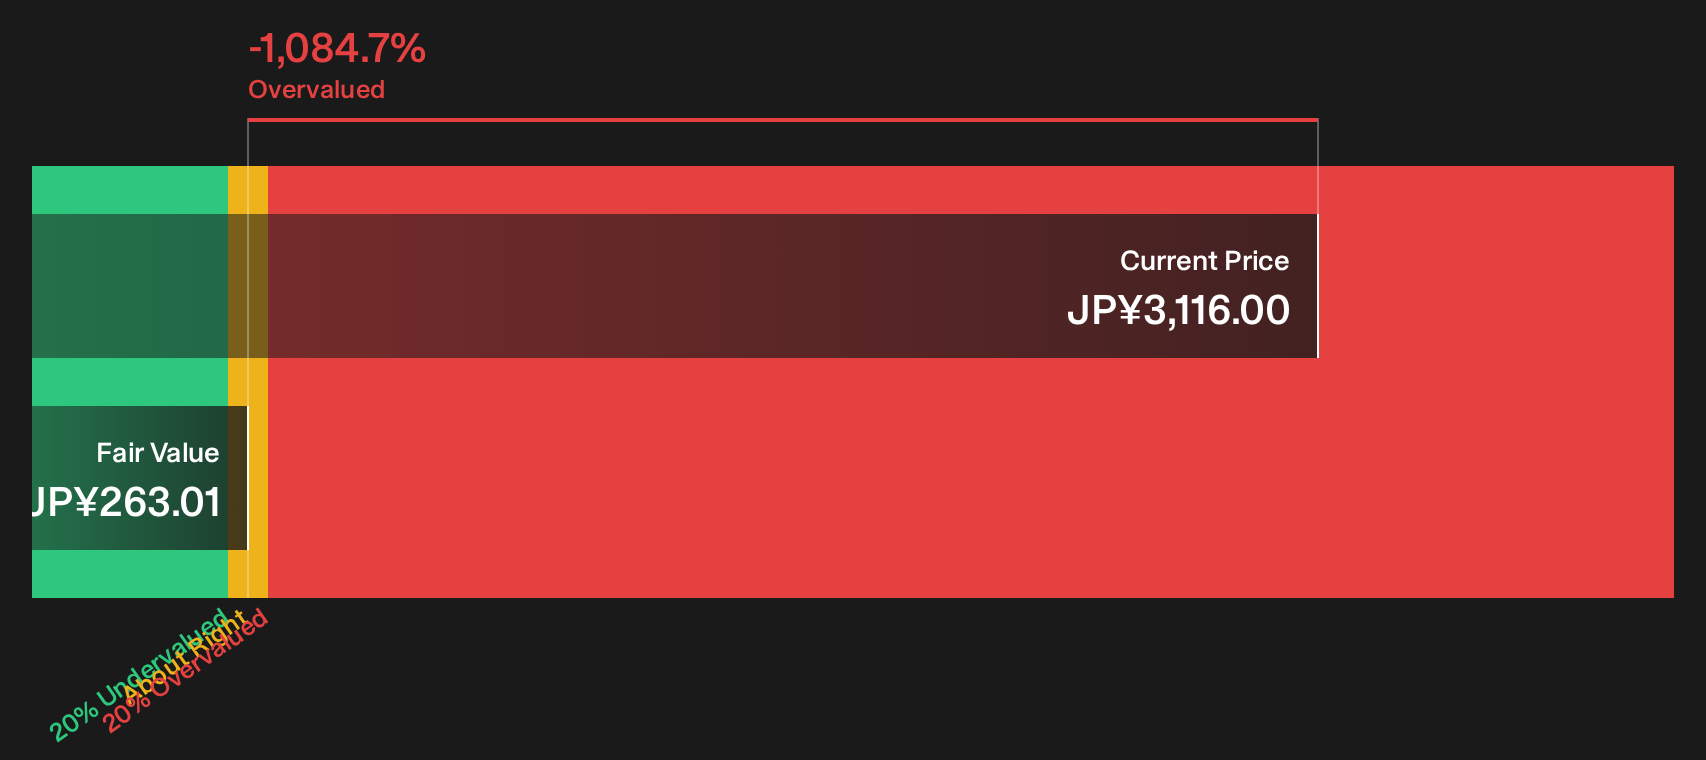
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ito En for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Ito En is clearly split, with rich valuation signals on one side and pockets of optimism on the other. Act quickly and weigh the full picture for yourself by reviewing the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Ito En?
If Ito En has you rethinking valuation, use that momentum and broaden your watchlist with other opportunities that fit your risk, income, and quality preferences.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio when markets turn choppy.
- Pursue income-focused opportunities through a curated 20 dividend fortresses that highlights payouts with the potential to meaningfully contribute to total returns.
- Spot future contenders early by working through a focused 76 high quality undiscovered gems before they land on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com