
Why Mitsui Kinzoku Company (TSE:5706) Stock Climbed On Its Latest Update
Mitsui Kinzoku stock: why a solid-state battery partnership matters now
Mitsui Kinzoku Company (TSE:5706) is back in the spotlight after Factorial Energy announced a partnership to industrialize its Solstice all solid-state battery platform using Mitsui Kinzoku’s sulfide electrolyte technology and copper foil expertise.
The sharp 8.14% 1 day share price return to ¥2,478, alongside a 7.62% 7 day share price gain but a 30 day share price decline of 14.03% and a 90 day drop of 36.04%, points to fresh momentum around the Factorial partnership after a choppy few months. At the same time, the 102.81% 1 year total shareholder return and very large 3 year and 5 year total shareholder returns suggest long term holders in Mitsui Kinzoku have already seen substantial upside.
Compare Mitsui Kinzoku's solid-state battery catalyst with other materials and energy enablers by scanning our hand picked 34 best rare earth metal stocks tied to electrification and advanced electronics demand.
Bulls point to Mitsui Kinzoku’s solid-state foothold and long term return record, while bears highlight the recent 36.04% 90 day slide. Which camp does the current valuation work harder for?
Price-to-earnings of 12.4x for Mitsui Kinzoku: is it justified?
Mitsui Kinzoku Company trades on a P/E of 12.4x, which puts the stock slightly above both its peer group on 12.3x and the broader JP Metals and Mining industry on 11.3x.
The P/E ratio compares the ¥2,478 share price with the company’s earnings per share, so it effectively shows how many years of current profits investors are willing to pay for. For a materials group with solid-state battery exposure, that earnings multiple provides a quick snapshot of how much optimism is already embedded in the price.
Against that backdrop, the current level appears somewhat higher than sector averages. At the same time, the estimated fair P/E of 18.1x from the fair ratio work suggests that the current valuation sits between industry levels and that fair ratio reference. Compared with the industry, the existing 12.4x P/E is above the JP Metals and Mining sector but below the 18.1x fair level, so the stock screens as expensive versus peers but cheaper than the fair ratio benchmark.
Explore the SWS fair ratio for Mitsui Kinzoku Company.
Result: Price-to-earnings of 12.4x (ABOUT RIGHT)
Still, the recent 36.04% 90 day slide and reliance on successful execution of Mitsui Kinzoku’s solid-state battery partnership could easily challenge this valuation story.
Find out about the key risks to this Mitsui Kinzoku Company narrative.
Another view on Mitsui Kinzoku’s value
The SWS DCF model paints a cooler picture for Mitsui Kinzoku. At ¥2,478 per share, the stock trades above an estimated future cash flow value of ¥1,904.46, which implies the shares look expensive on this lens. Which signal do you treat as the anchor: earnings multiple or cash flow math?
Look into how the SWS DCF model arrives at its fair value.
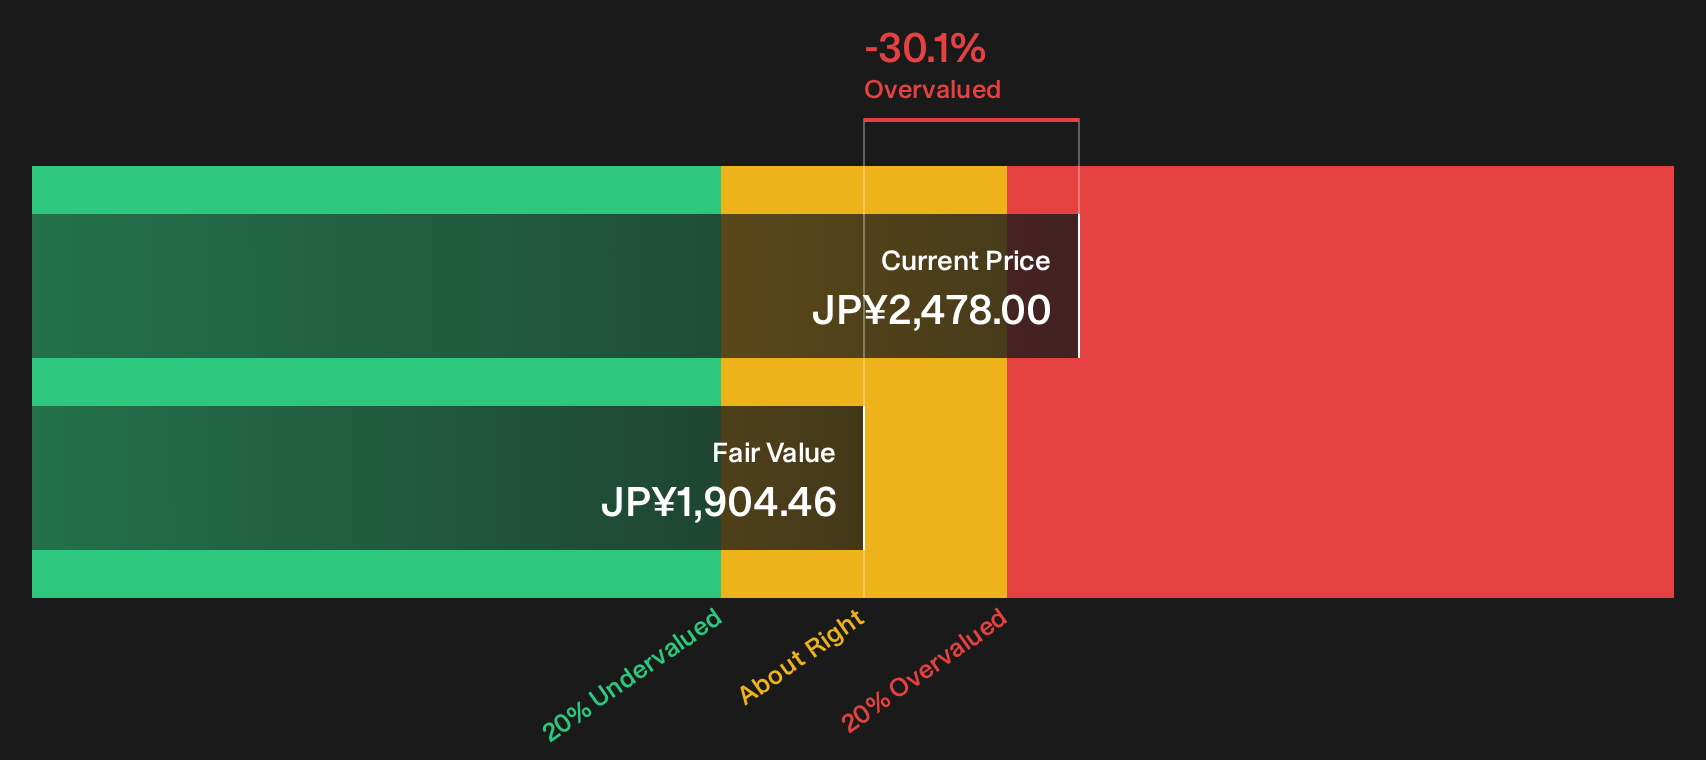
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsui Kinzoku Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Mitsui Kinzoku can be useful if you use them. Look at the same numbers, challenge the mood in the share price, and weigh up both the potential upsides and the issues that could hold the business back by checking the 3 key rewards and 1 important warning sign
Looking for more Mitsui Kinzoku sized ideas?
If Mitsui Kinzoku has you thinking harder about opportunities, do not stop at a single stock. Broader idea hunting can sharpen your portfolio decisions.
- Target potential mispricings by scanning the 17 high quality undervalued stocks that combine solid fundamentals with room for the market to reassess expectations.
- Anchor your income plan by reviewing the 20 dividend fortresses that focus on higher yields with supporting balance sheets and cash flows.
- Dial down portfolio stress by checking the 21 resilient stocks with low risk scores built around businesses with more resilient risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com