
China Feihe (SEHK:6186) Weighs A Special Dividend, Is The Stock Still Cheap?
China Feihe (SEHK:6186) has proposed a special dividend, with its board scheduled to meet on 29 September 2026 to consider both declaring and paying the payout.
The special dividend discussion arrives after a mixed run for China Feihe. The share price has risen 3.02% over the past day and 6.43% over the past week, yet the year-to-date share price return is down 32.26% and the 5-year total shareholder return is down 71.61%. This suggests that short-term momentum is improving while longer-term performance has remained weak.
Scan how the proposed China Feihe special dividend compares with other potential comeback stories by reviewing hand picked 191 high quality undervalued stocks across global markets.
The special dividend talk and recent bounce in China Feihe sharpen a basic timing question. Is it better to step in after this announcement, or to wait and see what the current valuation really implies?
Preferred P/E of 11.6x: Is it justified for China Feihe?
For China Feihe, the current picture starts with price. The shares last closed at HK$2.73, and on that price the stock trades on a P/E of 11.6x, while internal fair value work suggests the equity is trading at a 62.8% discount to a cash flow based estimate of worth.
The P/E ratio compares what investors are paying today for each unit of current earnings. For a dairy and nutrition producer like China Feihe, that lens is often used because profit quality, brand power, and pricing all feed directly into earnings, and the business already generates net income rather than being purely in build out mode.
China Feihe is flagged as good value on two fronts. The P/E of 11.6x screens below an estimated fair P/E of 13.6x. This implies the multiple could have room to move closer in that direction if earnings and cash flows track internal expectations. The same 11.6x is also described as attractive relative to a peer average of 18.8x, which is a strong gap if those peers share similar risk and growth profiles.
The comparison within the Hong Kong Food industry is far tighter. On that measure, the stock is described as slightly expensive, with its 11.6x P/E just above the sector average of 11.5x. That framing suggests the bigger divergence sits between China Feihe and its specific peer set rather than the broad industry grouping.
Explore the SWS fair ratio for China Feihe.
Result: Price-to-earnings of 11.6x (UNDERVALUED).
Still, China Feihe carries clear risks, including pressure on long term share returns and reliance on Mainland China as the dominant revenue base.
Find out about the key risks to this China Feihe narrative.
Another View: What the SWS DCF Model Says About China Feihe
The P/E points to value in China Feihe, but the SWS DCF model goes further. At HK$2.73, the stock is assessed as trading 62.8% below an estimated fair value of HK$7.34. That is a big gap. The question is whether the cash flow assumptions behind it prove realistic.
Look into how the SWS DCF model arrives at its fair value.
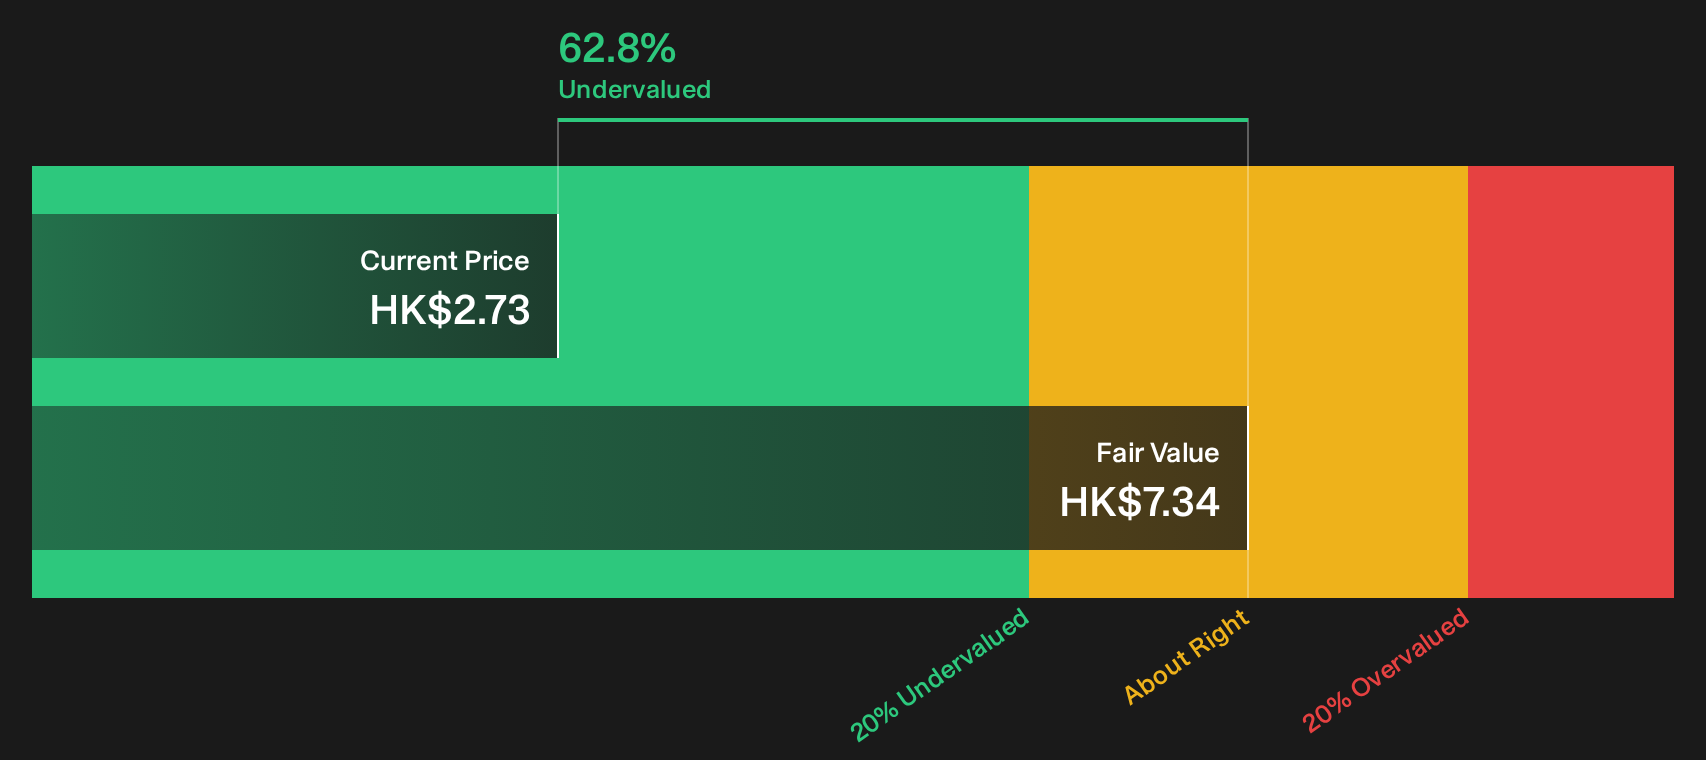
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Feihe for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on China Feihe is split, with clear concerns and some genuine bright spots. Investors may want to move quickly, review the data, and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond China Feihe?
If China Feihe has your attention, do not stop here. Broader opportunities may be only a few clicks away, and waiting could mean watching others move first.
- Explore potential rebounds in companies with compressed valuations and stronger fundamentals by scanning the 191 high quality undervalued stocks.
- Review the 159 dividend fortresses to find higher yielding businesses with more resilient payout profiles.
- Filter for the 224 resilient stocks with low risk scores to prioritize companies that combine sturdier balance sheets with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com