
DHT Holdings Heads 3 High Yield Dividend Stocks To Watch
Bond yields are hitting levels not seen in decades, which means income focused assets suddenly have real competition from government bonds. That is exactly when long term dividend payers get interesting. You are not just chasing a headline yield; you are looking at businesses that have kept cash flowing through different cycles. This article highlights three high yield dividend veterans that may deserve a closer look now.
The stocks profiled below are a sample of the high yield dividend veterans on the radar, while the full Dividend Aristocrats screen surfaced 4 more companies with similarly compelling income stories that are not covered here. To identify and analyze those additional Aristocrats where stability meets high yields, go straight to the Dividend Aristocrats screener.
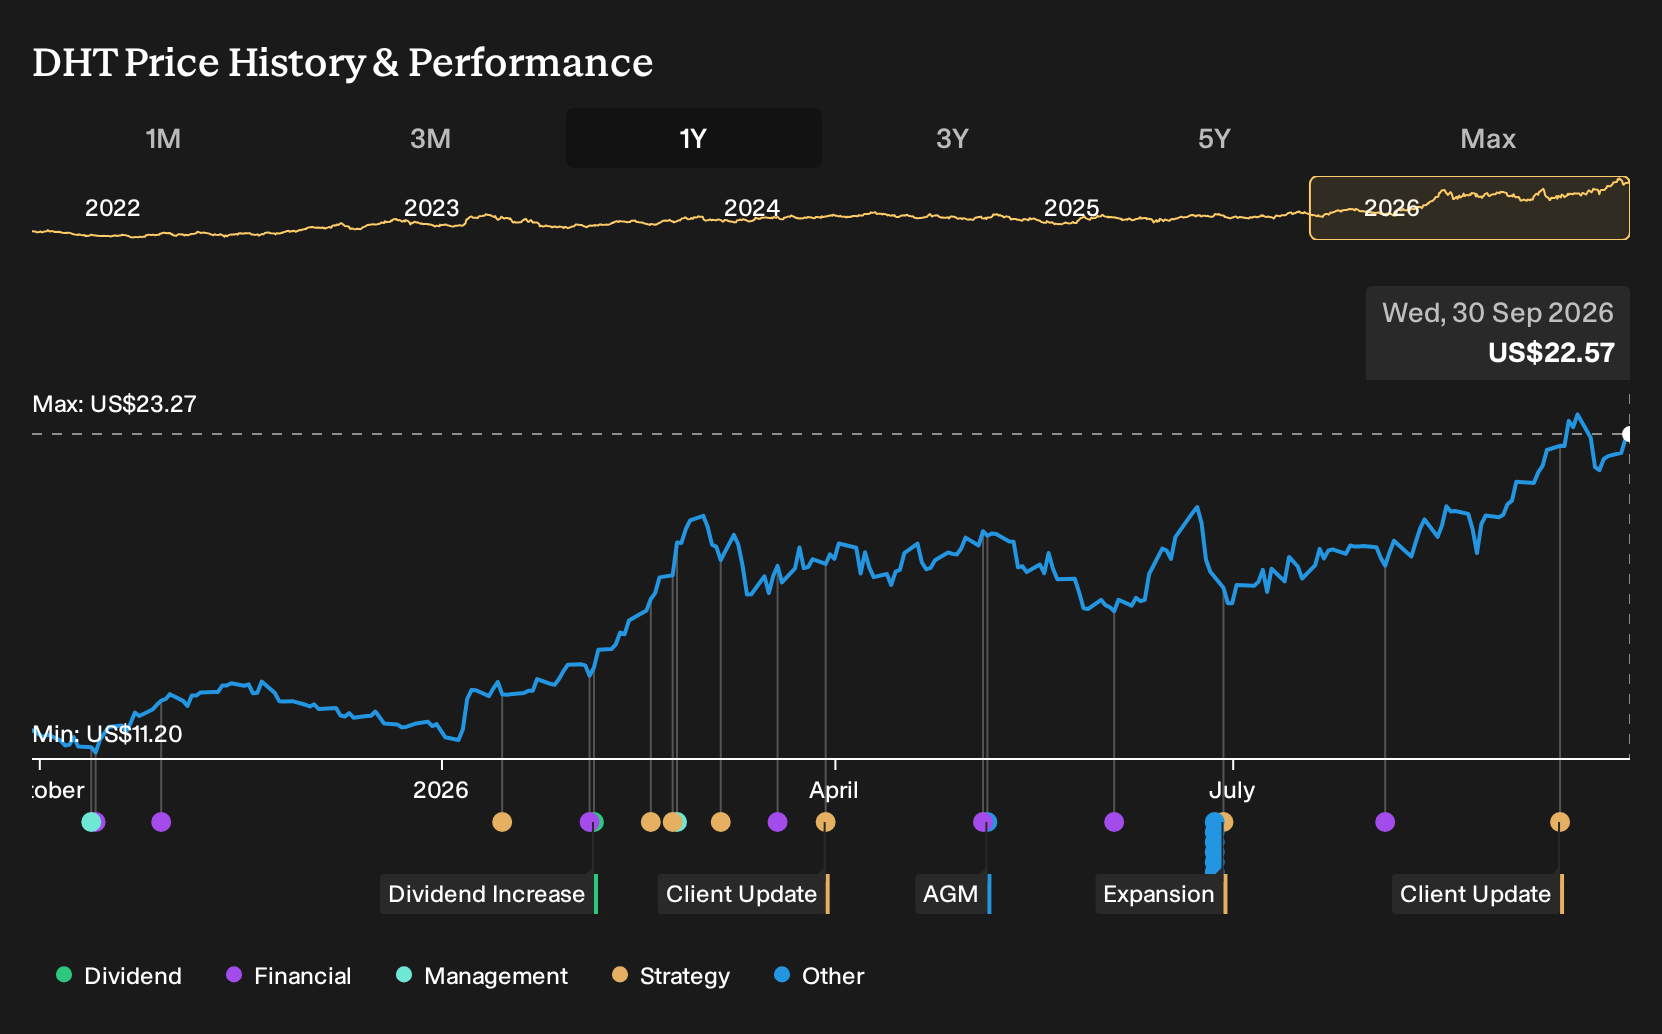
DHT Holdings (DHT)
DHT Holdings focuses on very large crude carriers that generate the cash flow supporting its high dividend policy. This is exactly what the Dividend Aristocrats screen is looking for when bond yields are giving income investors more options.
DHT Holdings runs a fleet of crude oil tankers, generating about US$799 million from its vessels and technical management services, and has a market value of roughly US$3.6b. This gives it meaningful scale for sustaining a high yield through cycles.
"Starting February 28 2026, The escalation of US-Israel strikes on Iran, including the assasination of Iran's Supreme Leader, Khamenei. This have triggered Iranian retaliation which include effective disruptions or closures in the Strait of Hormuz that serves as a vital chokepoint for global oil trade, handling about 25% of the world's crude oil trade."
What happens if one unseen pressure keeps VLCC day rates elevated for longer than the market currently dares to price in?
If that pressure interests you, read the full narrative for DHT Holdings to see how DHT Holdings' income story could evolve as trade routes and day rates keep shifting.
Adams Diversified Equity Fund (ADX)
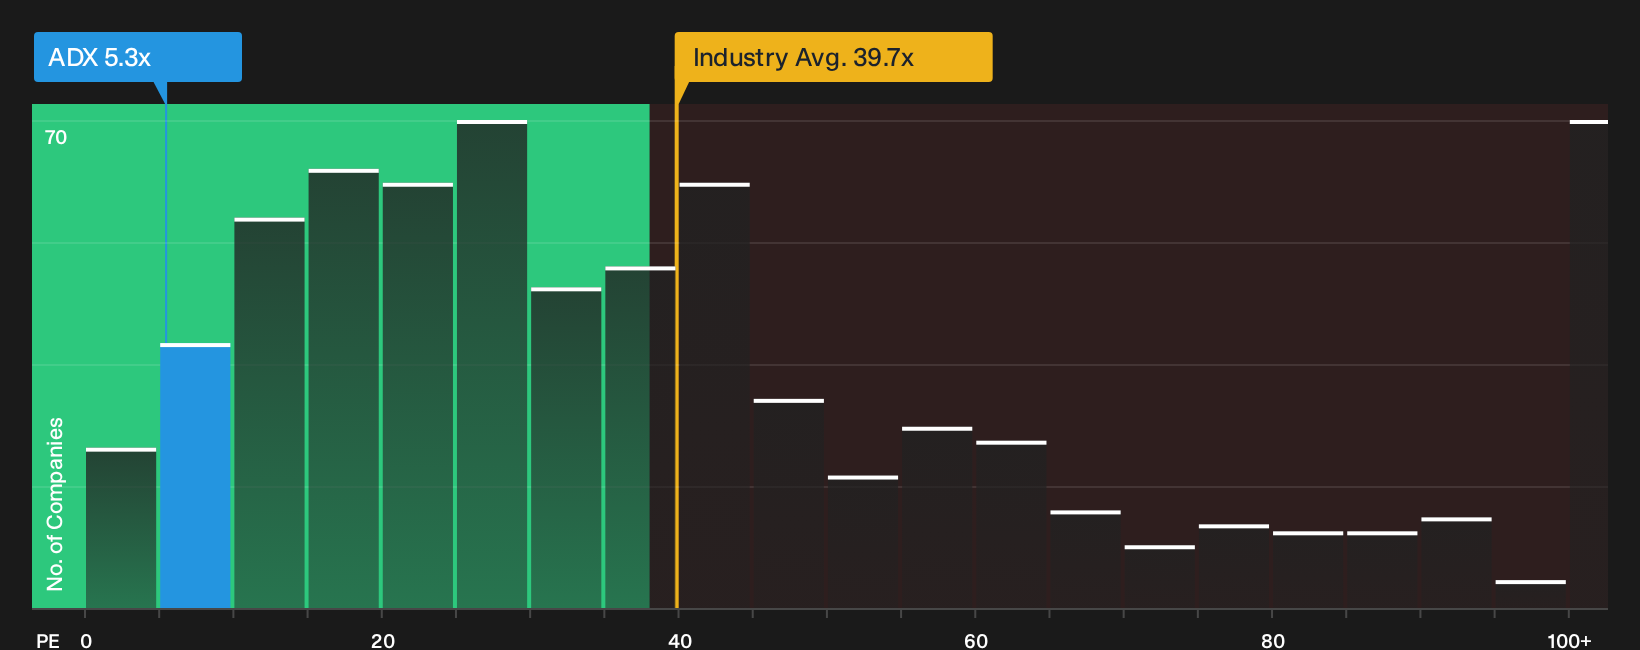
Adams Diversified Equity Fund is a closed end fund built around paying regular dividends from a broad US equity portfolio, which is why it fits a high yield Dividend Aristocrats theme. It earns about US$34 million from closed end fund activities and has a market value near US$3.2b.
ADX brings together a long income paying history, recent half year revenue of US$18.94 million and US$320.68 million in net income, and a P/E of 5.3x that is far below US capital markets peers. That mix of high yield appeal and discounted valuation is only effective if one key pressure on future distributions develops in your favor.
If that pressure on future distributions is what you are testing, start with the 2 key rewards and 2 important warning signs to see what might be masking or amplifying ADX's yield story.
First National Bank Alaska (FBAK)
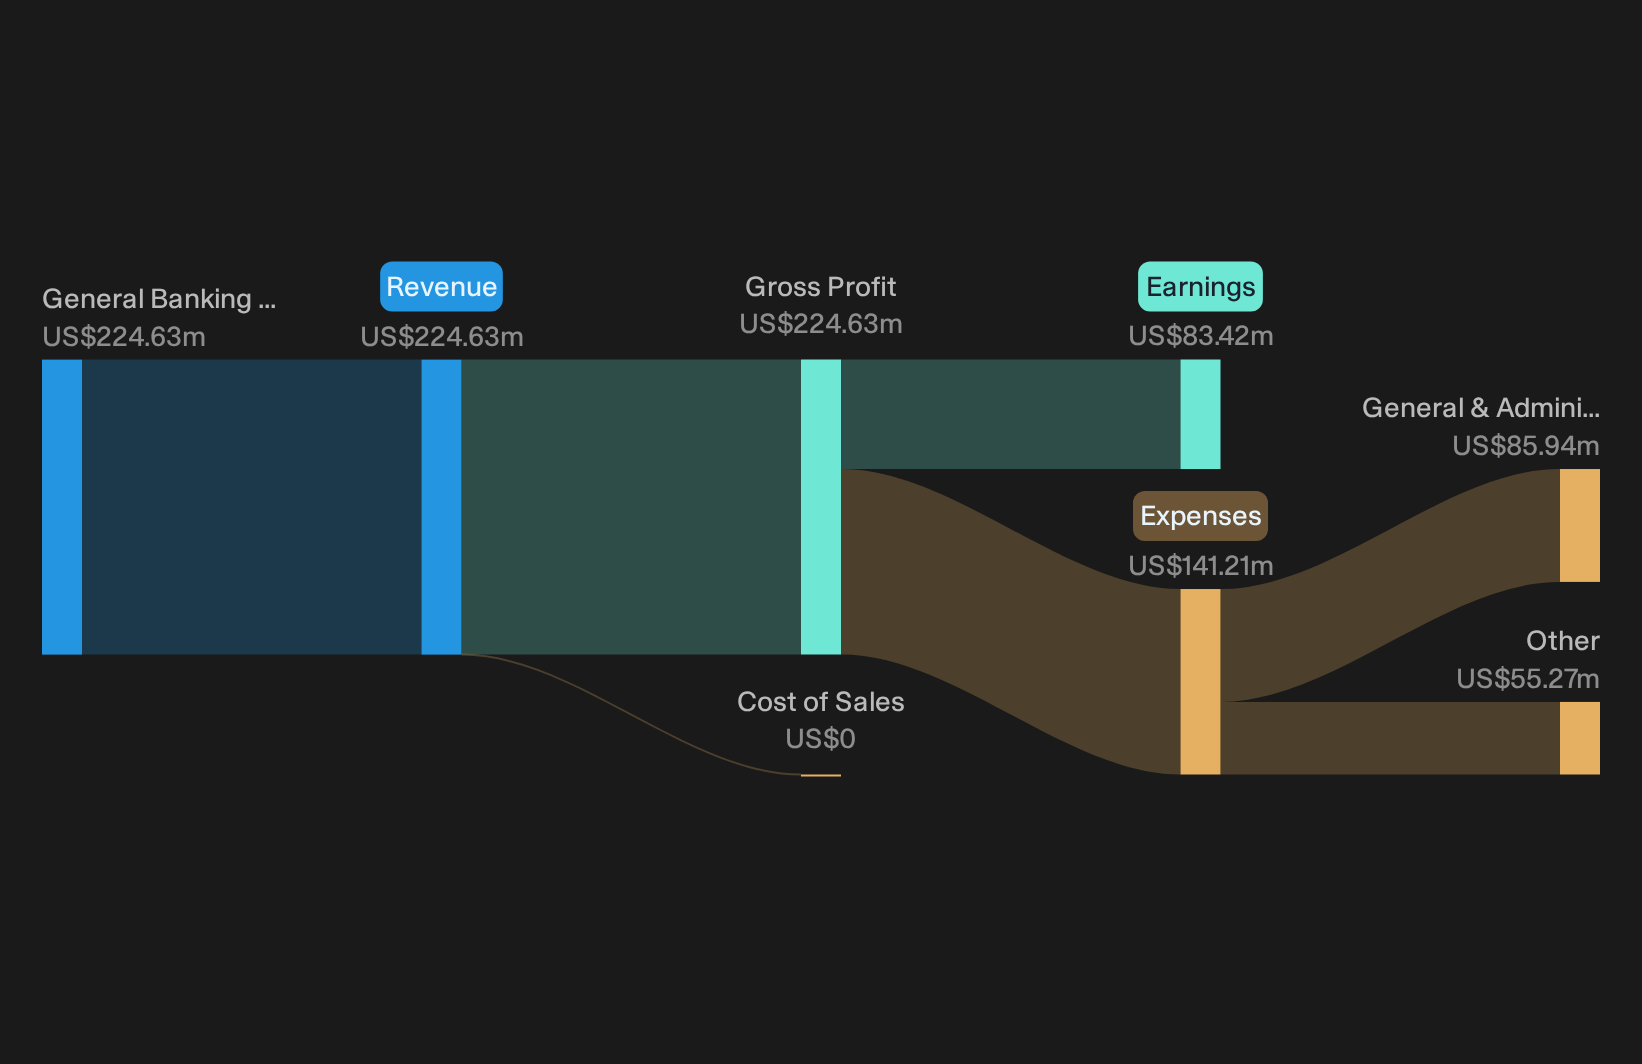
First National Bank Alaska runs a traditional deposit and lending franchise that fits a high yield dividend theme. Almost all of its US$224 million in revenue comes from general banking and trust services in the United States, and the stock carries a market value of about US$1.03b.
First National Bank Alaska pairs a 5%+ income story with classic commercial banking, where deposits and a diversified loan book generate the cash flow that can support sizeable payouts. Strong profitability and a fresh Q3 2026 dividend signal may be appealing, depending on how one unresolved dividend stability question is answered.
That dividend stability question starts with the balance sheet and the income engine behind it, so check the First National Bank Alaska financial health report for what could quietly shift the payout trajectory.
Curious About Dividend Alternatives?
Fresh ideas move first, and by the time momentum stories are flying, early entries are gone. Scan under the radar for now, before the crowd arrives, and act now.
- Spot robust balance sheets before they get fully priced by checking the list of solid balance sheet and fundamentals (25 results) while the strongest fundamentals are still being overlooked by most investors.
- Ride early AI momentum by filtering for 37 profitable AI stocks that aren't just burning cash that already generate real earnings instead of burning cash on promises that may not hold up.
- Position ahead of potential commodity sentiment swings by reviewing the 36 elite gold producer stocks while these producers remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com