
Almirall (BME:ALM) Showcased New Dermatology Data, Is The Stock Still A Bargain?
Almirall (BME:ALM) is back in focus after unveiling extensive new clinical data for its dermatology pipeline at the 35th EADV Congress in Vienna. Long-term results for lebrikizumab and tildrakizumab drew particular attention.
For investors, the clinical headlines arrive alongside a mixed price picture, with a 1-day share price return of 2.33% and a 7-day gain of 1.54%. This is set against a year-to-date share price decline of 18.14% and a 1-year total shareholder return down 9.63%, which hints at improving short-term momentum after a weaker stretch for Almirall.
Scan beyond Almirall and compare this dermatology-focused story with other healthcare specialists by reviewing a curated set of 133 healthcare AI stocks.
The recent uptick in Almirall’s share price sits against a weaker 1-year picture, which raises a simple question. Are investors reassessing the underlying dermatology franchise, or is this just sentiment chasing fresh clinical headlines before valuation catches up?
Most Popular Narrative: 28% Undervalued
Almirall's most followed valuation narrative points to a fair value of €14.58 against the last close of €10.56. This frames the recent clinical news against a stock that this framework views as trading at a discount.
Strong and sustained expansion of the dermatology portfolio (notably Ebglyss and Ilumetri) is supported by growing prevalence of chronic skin and autoimmune diseases due to demographic shifts. Aggressive pipeline launches and label expansions are expected to drive double-digit net sales growth through 2030.
See why 15 investors see Almirall as 28% undervalued.
Result: Fair Value of €14.58 (UNDERVALUED)
Still, concentration in a few key dermatology drugs and ongoing pressure on biologic margins could quickly weaken the Almirall narrative if competition or pricing shifts.
Find out about the key risks to this Almirall narrative.
Another View: What Almirall's P/E Is Telling You
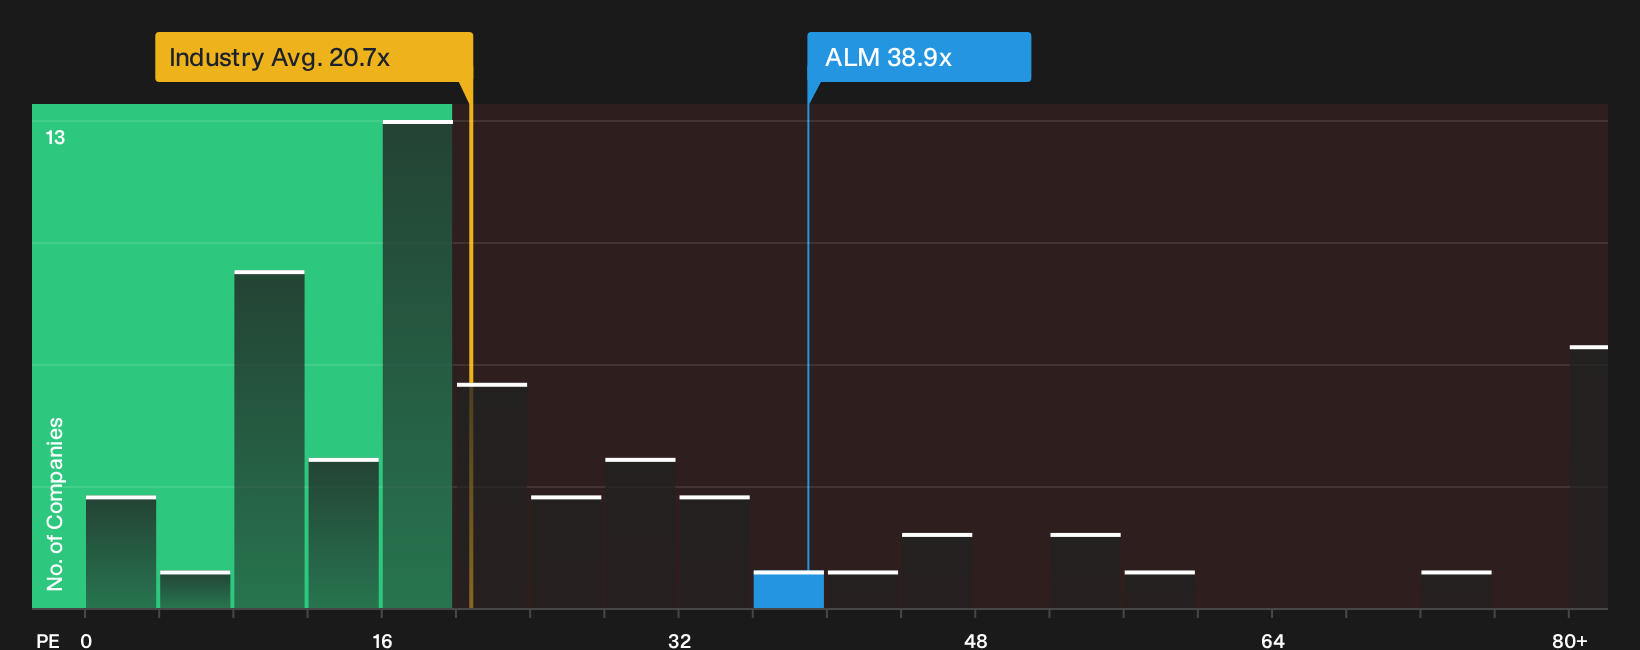
The discount story around Almirall looks different once you switch to simple earnings multiples. The stock trades on a P/E of 38.9x, while the European pharmaceuticals group sits at 19.8x, peers average 20.7x, and the fair ratio sits at 24.8x based on regression work.
That gap signals investors are already paying a much richer price per euro of current earnings than both sector and peer norms, even though one model points to a discount to fair value. The key question is whether that premium narrows toward the fair ratio and peer levels, or whether earnings grow enough to justify staying above the pack.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Almirall is split, which makes this a moment to move quickly on your own homework instead of following the crowd. To see what investors are finding attractive about the story, review the 4 key rewards.
Looking For More Investment Ideas Beyond Almirall?
If Almirall has sharpened your focus on where capital goes next, do not stop here. Fresh opportunities often emerge where investors are not yet looking.
- Target steadier potential outcomes by scanning 224 resilient stocks with low risk scores that aim to keep drawdowns under tighter control.
- Spot mispriced opportunities early by reviewing the 191 high quality undervalued stocks that combine solid fundamentals with discounted valuations.
- Hunt for under-the-radar potential by checking the 617 high quality undiscovered gems that most portfolios have not yet touched.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com