
Pop Mart (SEHK:9992) Stock Looks Reasonable After Its 7x Three Year Run
Pop Mart International Group has given long term holders a very large three year share price gain, yet more recent declines have investors asking whether the current Hong Kong$152.60 price is still backed by its earnings power. With short term returns turning negative, the focus has shifted to what the profit line alone can justify.
- Over the past three years the share price has climbed by roughly 7x. This puts the current earnings based valuation debate front and center for anyone considering the stock today.
- The business now leans heavily on how efficiently it can turn its pop culture franchises and retail footprint into sustainable profit margins. This can shape what investors are willing to pay for each dollar of earnings.
- The analysts covering Pop Mart International Group have run their own numbers. See what analysts think Pop Mart International Group's shares could be worth.
The stock's next move may depend on whether Pop Mart International Group's earnings are strong enough to justify the price investors are currently paying.
To stress test whether Pop Mart International Group's earnings justify its recent run up, it can help to line it up against 191 high quality undervalued stocks.
Does Pop Mart International Group Look Fairly Valued on Earnings?
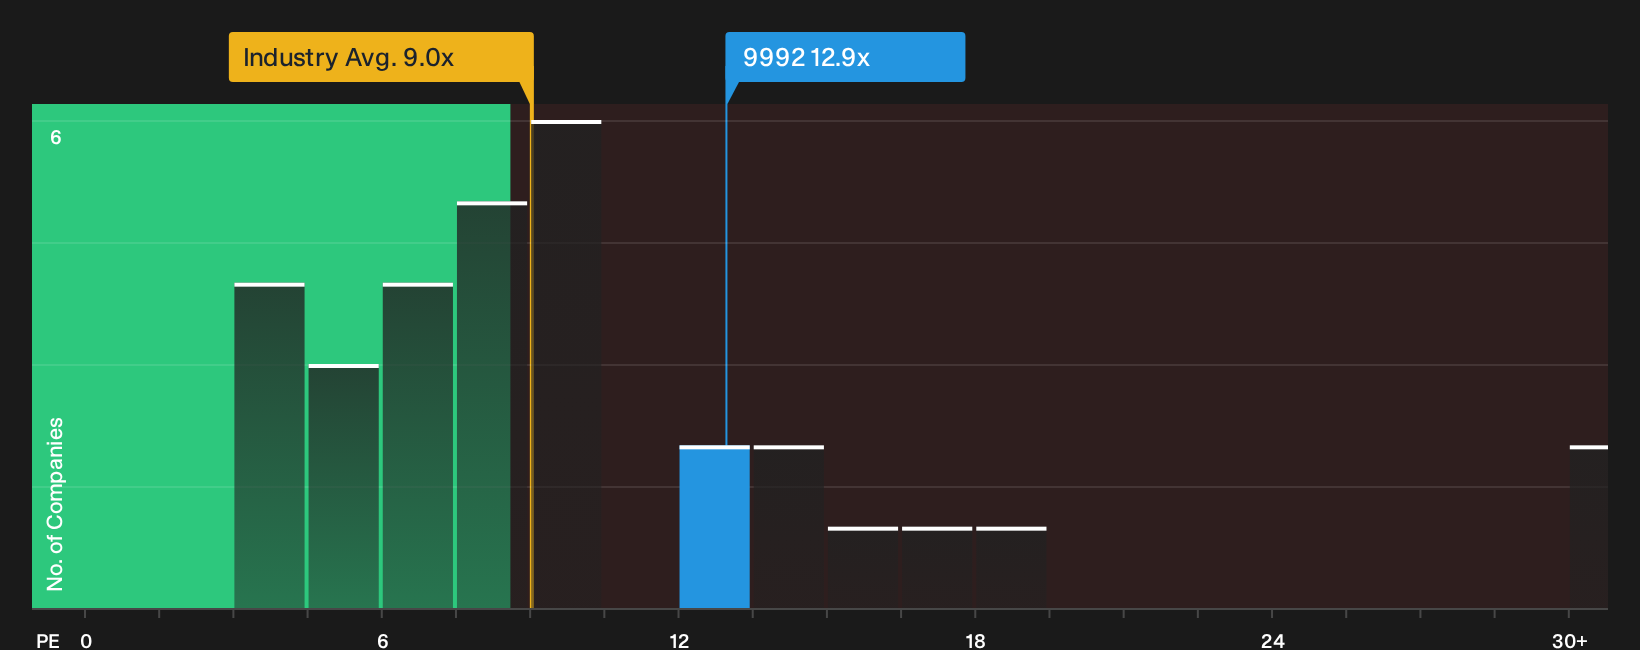
The P/E ratio fits Pop Mart International Group because earnings are a central focus for consumer brands that rely on franchises and merchandising. At around 12.9x earnings, the stock trades above the Specialty Retail industry average of about 9.0x and also above the peer group near 10.2x. That premium suggests investors are paying more for each unit of current profit than they do for many other retailers.
The fair P/E level implied by a more tailored model that blends Pop Mart International Group's business profile, profitability and risk sits very close to where the shares trade today, so the present multiple looks about right rather than clearly stretched or obviously cheap. For anyone weighing an entry or exit, the key question is whether the earnings base that underpins this mid-teens multiple feels robust enough, given the company’s reliance on hit product cycles and retail execution, to keep justifying that pricing. Explore the numbers behind Pop Mart International Group's P/E valuation.
The Pop Mart International Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E debate on Pop Mart International Group leaves off, by spelling out what kind of future earnings, margins and growth path would need to unfold for the stock to trade meaningfully above or below today's level. Each scenario ties a fair value to a clear story about Pop Mart International Group's potential catalysts and key risks, so you can track over time which version of events appears to be taking shape on the Community page.
A clear, numbers based narrative on Pop Mart International Group is useful now because it pins down exactly what kind of future earnings, margins and execution would justify paying a premium P/E to peers. It also gives you a benchmark that can be checked against each new result so you can see whether Pop Mart International Group's actual progress tracks, exceeds or trails those assumptions over time.
Share your own Narrative for Pop Mart International Group and set out the assumptions behind your valuation.
One more angle on Pop Mart International Group that could change your view
Valuation only tells part of the story, because Simply Wall St checks have also highlighted potential pressure points in Pop Mart International Group that deserve a closer look before you lean on the current multiple. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com