
Is Bellevue Gold (ASX:BGL) Undervalued Following Its Full Year Profit Turnaround?
Bellevue Gold (ASX:BGL) just posted full year 2026 results, reporting a shift from a prior loss to a net profit of A$7.08 million on A$576.26 million in sales.
Despite the profit turnaround, Bellevue Gold’s recent share price has cooled, with the stock down over the past month but still showing a 90 day share price return of 18.05% and a 1 year total shareholder return of 29.75%. This suggests that momentum has slowed rather than reversed.
Scan how Bellevue Gold compares with other hand-picked producers by reviewing the 36 elite gold producer stocks that meet strict financial and operational filters.
Bellevue Gold now trades at a meaningful discount to both analyst targets and an intrinsic value estimate after a soft patch in the share price. Is that caution about the fresh A$7.08 million profit justified?
Preferred Price-to-Sales Multiple of 4.1x: Is It Justified?
Bellevue Gold now carries a P/S of 4.1x at a last close of A$1.57, which screens as expensive versus its own fair multiple estimate yet cheaper than many peers. That tension between the current tag and the underlying cash generation story is what investors are weighing after the recent profit milestone.
The P/S ratio looks at the market value of the equity relative to revenue, so it is often used for miners and other resource groups where earnings can be noisy but sales are easier to compare. For Bellevue Gold, the 4.1x figure is being applied to A$576.26 million of annual revenue, so the quoted valuation is closely tied to how durable that production profile appears.
On peer comparison, the 4.1x P/S is above a peer average of 2.5x, which points to a richer tag than similar producers. At the same time, it is far below the 92.4x average across the broader Australian Metals and Mining sector, and well above an estimated fair P/S of 1.1x that the market could move toward if sentiment cools. That mix of signals suggests the stock is priced for stronger prospects than a typical producer even though wider sector valuations appear stretched.
Explore the SWS fair ratio for Bellevue Gold.
Result: Price-to-sales of 4.1x (OVERVALUED)
Still, the story can change quickly if production volumes, costs or the A$7.08 million profit come under pressure and sentiment toward Bellevue Gold turns sharply colder.
Find out about the key risks to this Bellevue Gold narrative.
Another View On Bellevue Gold’s Valuation
Price to sales paints Bellevue Gold as expensive next to peers, yet the SWS DCF model points the other way. At A$1.57, the stock sits well below an estimated future cash flow value of A$3.23, which frames the shares as undervalued on that lens. Which signal should carry more weight for you?
For investors who want to see how that cash flow based estimate is built and stress tested over time, Look into how the SWS DCF model arrives at its fair value.
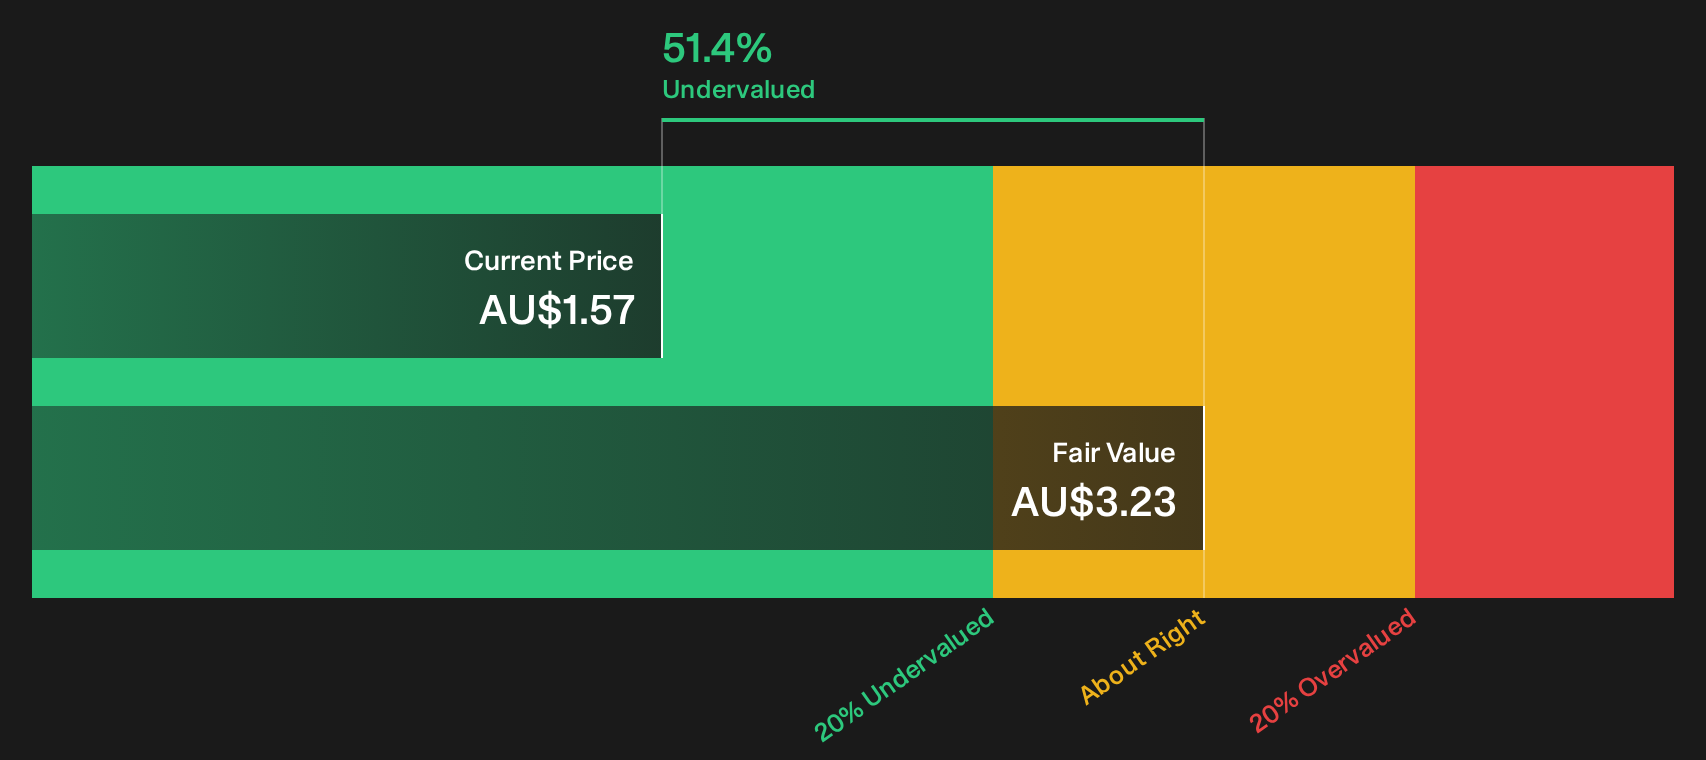
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bellevue Gold for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The signals on Bellevue Gold are mixed enough that no single metric tells the full story, so it helps to move quickly and check the underlying data directly. To see why some investors are optimistic, take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Bellevue Gold?
If you stop with Bellevue Gold, you miss a wider field of opportunities. Put the Simply Wall St screener to work and let the data widen your radar.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (12 results) that combine financial strength with fundamentals many investors overlook.
- Hunt for mispriced quality by reviewing the 5 high quality undervalued stocks that blend strong cash flows with supportive valuations.
- Spot future market favourites early by checking the 15 high quality undiscovered gems that strong fundamentals already back, even if wider attention has not arrived yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com