
How Investors Are Reacting To Mirvac Group (ASX:MGR) Defensive Dividend Shift
- Recent commentary highlights how rising interest rates, sticky inflation and a weaker Australian dollar are pushing investors toward Australian defensive dividend stocks, with Mirvac Group offering large cap REIT exposure through rental cashflows and development earnings.
- Mirvac Group’s blend of income producing assets and development projects is being treated as a potential ballast when funding costs and macro risks become harder to predict.
- We will now explore how this renewed interest in Mirvac Group as a defensive dividend option shapes the broader investment narrative for the business.
Compare Mirvac Group with a curated pool of income-focused property players by scanning the 3 dividend fortresses for ideas that could complement your defensive dividend watchlist.
Mirvac Group Investment Narrative Recap
For Mirvac Group, the big picture to consider is that an integrated mix of investment properties and a sizeable development book can still support dependable cashflows even as interest costs move around. The key near-term swing factor is how funding costs feed through to returns on that A$1.98b Development segment, alongside tenant demand across the A$976m Investment portfolio.
The biggest operational risk right now is the potential for more project-level issues or impairments across the pipeline, coupled with softer housing sentiment affecting build-to-sell or build-to-rent settlements. Recent macro noise around rates and inflation does not fundamentally alter those core drivers, although it can make execution and timing on disposals and new launches more demanding.
With no fresh company announcements tied directly to this latest macro backdrop, the most useful disclosure to focus on is still Mirvac Group’s recent reported result. The group booked A$2,971m of revenue and A$677m of net income, with net margins improving from 2.5% to 22.8%, and earnings increasing significantly year on year.
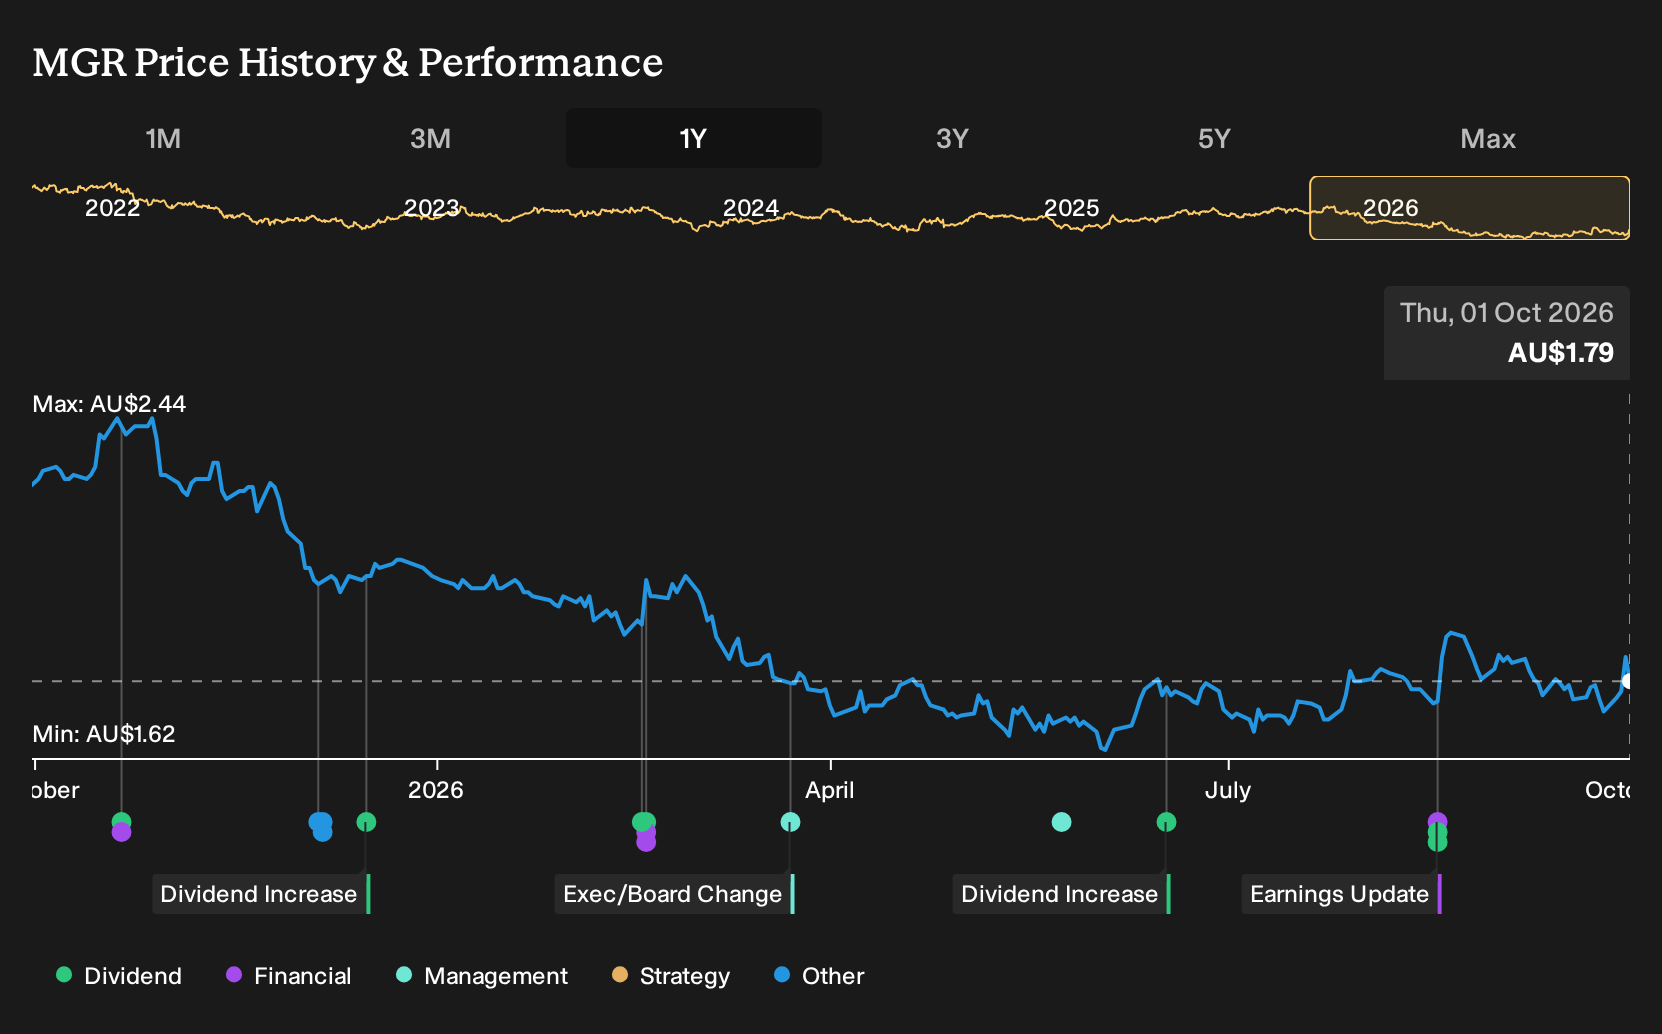
Those figures sit next to a share price of A$1.79 and a P/E of 10.4x, which screens below both peer and sector averages. For a yield-focused holder, the tension is clear. Analysts expect revenue to decline over the next three years while earnings rise, so any thesis rests heavily on project returns, capital partnering discipline and how reliably Mirvac can translate that recent earnings recovery into cash that supports its dividend profile.
Mirvac Group's narrative projects A$1.1b revenue and A$640.2m earnings by 2028. This assumes revenue will decline 26.1% per year and requires earnings to rise by about A$572m from A$68.0m today.
Uncover why Mirvac Group's fair value indicates a 38% potential upside to its current price, which could materialize faster than many income investors expect.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between A$2.35 and about A$3.41, which is a wide spread for Mirvac Group. Those private forecasts were made before the latest rate and inflation shifts, so factor in project risks, construction costs and housing demand yourself, and compare several contrasting viewpoints.
Explore 2 other Mirvac Group fair value estimates, including one that suggests as much as 91% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your own analysis and judgment.
- A great starting point for your Mirvac Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mirvac Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mirvac Group's overall financial profile at a glance.
Looking for more Mirvac Group sized ideas?
If Mirvac Group has put income resilience and risk control on your radar, it can help to widen the lens and compare it with other parts of the market that offer different mixes of yield, balance sheet strength and potential upside. The Simply Wall St Screener is built for exactly that sort of side by side work, letting you filter by dividends, financial footing and valuation in a few clicks.
- For investors who want staying power to come first, filter for companies with robust finances and steady fundamentals using the list of solid balance sheet and fundamentals (12 results).
- If value is your starting point and you are hunting for quality at a reasonable price, line up potential ideas through the 5 high quality undervalued stocks.
- When income is your anchor and you are building a watchlist around dependable payouts, scan the market using the 3 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com