
Undervalued Small Caps With Insider Activity To Explore In October 2026
In the last week, the United States market has been flat, although it has seen an overall increase of 11% over the past year with earnings forecast to grow by 18% annually. In this context, identifying stocks that are considered undervalued and exhibit insider activity can provide intriguing opportunities for investors seeking to capitalize on potential growth within small-cap companies.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.0x | 0.4x | 38.89% | ★★★★★☆ |
| Financial Institutions | 9.5x | 3.2x | 24.91% | ★★★★★☆ |
| Cardinal Infrastructure Group | NA | 0.9x | 36.24% | ★★★★★☆ |
| Enovis | NA | 0.5x | 44.26% | ★★★★★☆ |
| Surgery Partners | NA | 0.5x | 27.73% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.2x | 33.07% | ★★★★☆☆ |
| Union Bankshares | 9.4x | 2.0x | 47.19% | ★★★★☆☆ |
| German American Bancorp | 12.8x | 4.8x | 29.50% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 10.57% | ★★★☆☆☆ |
| Orion Group Holdings | 96.1x | 0.4x | 47.86% | ★★★☆☆☆ |
Let's uncover some gems from our specialized screener.
LCNB (LCNB)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: LCNB operates as a commercial banking and insurance agency with a focus on providing financial services, and it has a market capitalization of approximately $0.18 billion.
Operations: The company's revenue is primarily derived from its commercial banking and insurance agency operations, with recent figures reaching $92.04 million. Operating expenses have shown a significant increase over time, reaching $59.59 million in the latest period. The gross profit margin has consistently been at 100%, indicating that the cost of goods sold is negligible or not reported, allowing all revenue to be recognized as gross profit. Net income has experienced fluctuations, with a net income margin of 26.49% in the most recent quarter ending September 2026, reflecting profitability after accounting for operating expenses and other costs.
PE: 10.8x
LCNB, a smaller player in the financial sector, demonstrates potential with its recent strategic moves. The company reported increased net interest income of US$19.79 million for Q2 2026, up from US$17.54 million the previous year, and net income rose to US$7.49 million from US$5.92 million. Insider confidence is evident through share purchases over time, indicating belief in future growth prospects. Additionally, leadership transitions and debt financing initiatives aim to support ongoing expansion and operational efficiency improvements.
- Get an in-depth perspective on LCNB's performance by reading our valuation report here.
Evaluate LCNB's historical performance by accessing our past performance report.
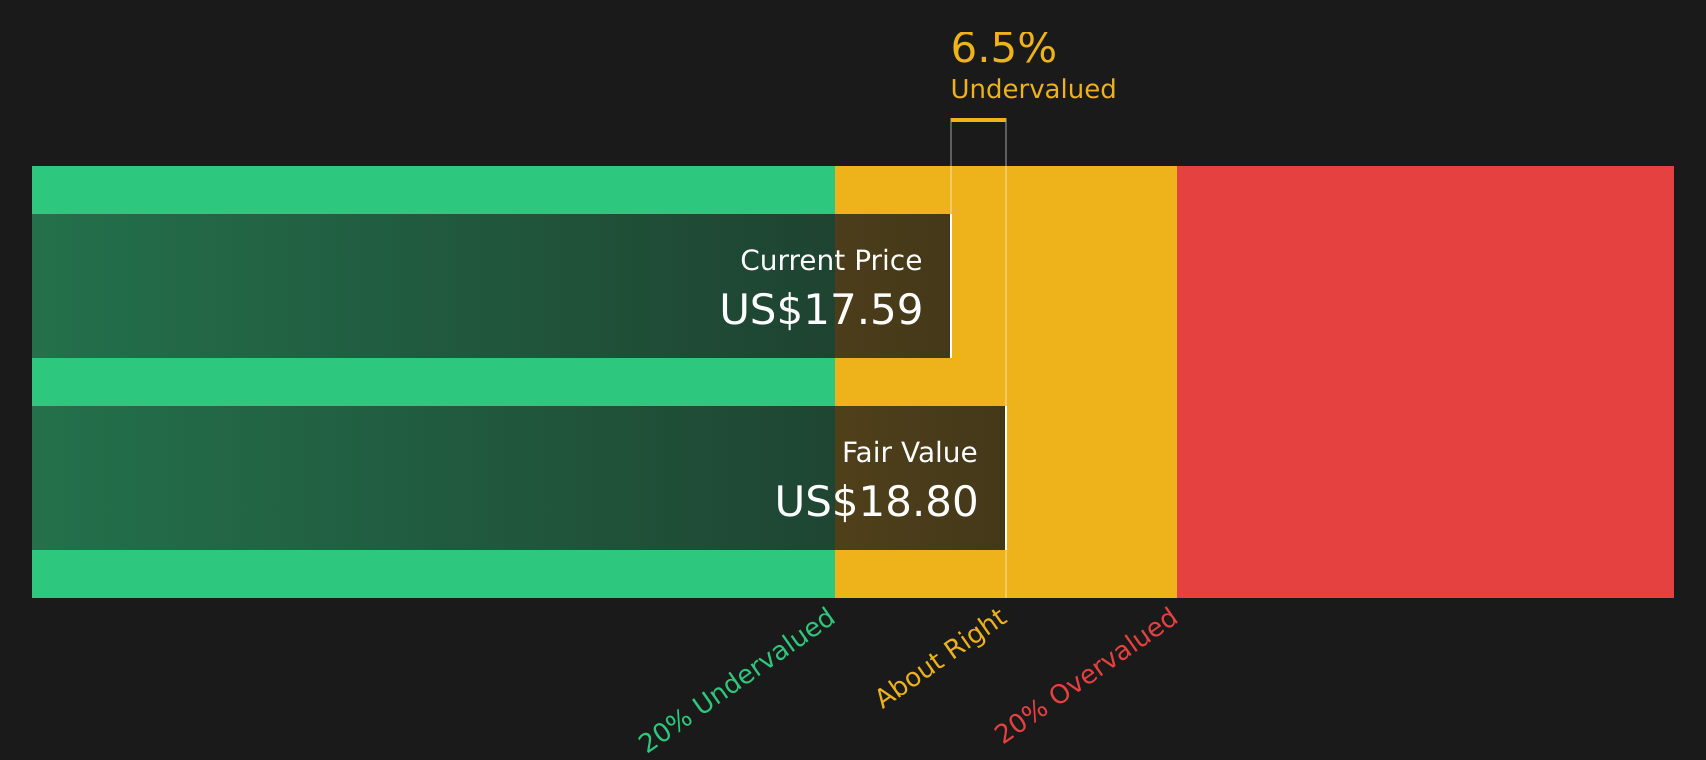
Cardinal Infrastructure Group (CDNL)
Simply Wall St Value Rating: ★★★★★☆
Overview: Cardinal Infrastructure Group specializes in heavy construction projects and has a market capitalization of $662.58 million.
Operations: Cardinal Infrastructure Group's revenue is primarily derived from its heavy construction segment, totaling $662.58 million. The company experienced fluctuations in its gross profit margin, peaking at 21.08% before declining to 19.21%. Operating expenses and non-operating expenses have shown an upward trend, impacting net income margins negatively over the periods analyzed.
PE: -169.5x
Cardinal Infrastructure Group, a smaller U.S. company, recently reported a notable increase in sales to US$226.93 million for Q2 2026 from US$106.11 million the previous year, though net income fell to US$4.68 million from US$7.17 million. Despite relying entirely on external borrowing for funding, they raised their 2026 revenue guidance to between $880-$900 million and anticipate significant earnings growth of over 150% annually. Insider confidence is evident with recent share purchases, suggesting optimism about future prospects despite current volatility and funding risks.
- Take a closer look at Cardinal Infrastructure Group's potential here in our valuation report.
Understand Cardinal Infrastructure Group's track record by examining our Past report.
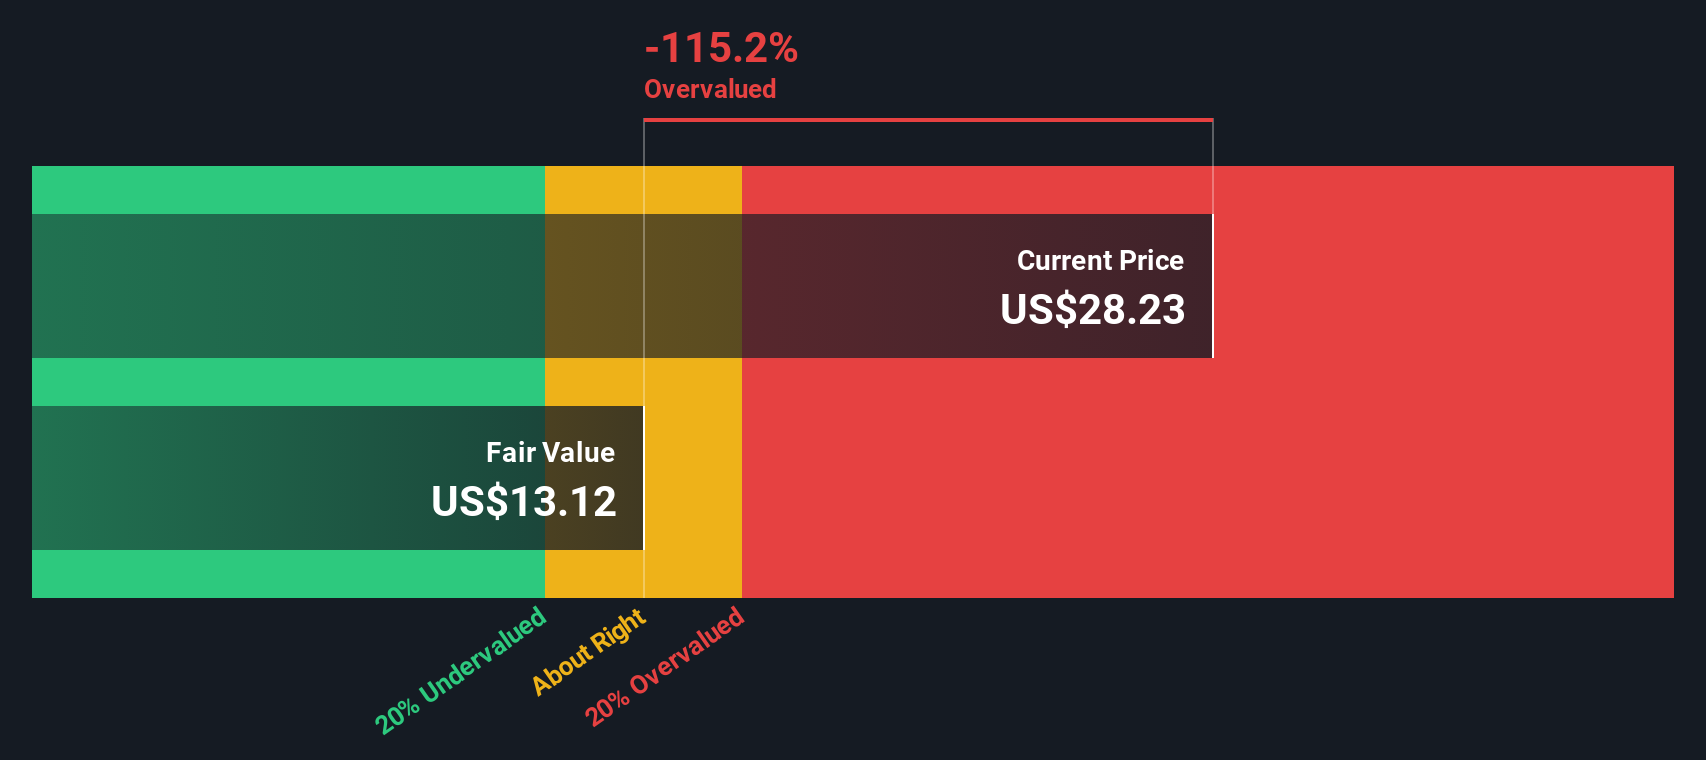
Fluence Energy (FLNC)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Fluence Energy specializes in providing battery energy storage systems and solutions, with operations generating $2.63 billion in revenue from this segment.
Operations: Fluence Energy's revenue is primarily derived from its Batteries / Battery Systems segment, with the latest figure standing at $2.63 billion. The company has experienced fluctuations in its gross profit margin, which recently reached 12.64%. Operating expenses are significant and include substantial allocations to R&D and sales & marketing activities.
PE: -13.6x
Fluence Energy, operating in the energy storage sector, has faced a challenging year with legal issues and financial setbacks. Despite reporting a revenue of US$649.8 million for Q3 2026, production delays have impacted its profit margins significantly. The company lowered its full-year revenue guidance to US$2.4 billion due to ongoing supply chain issues. However, insider confidence remains evident through recent share purchases by executives, indicating belief in long-term growth potential amid industry demand for energy solutions.
- Dive into the specifics of Fluence Energy here with our thorough valuation report.
Gain insights into Fluence Energy's historical performance by reviewing our past performance report.
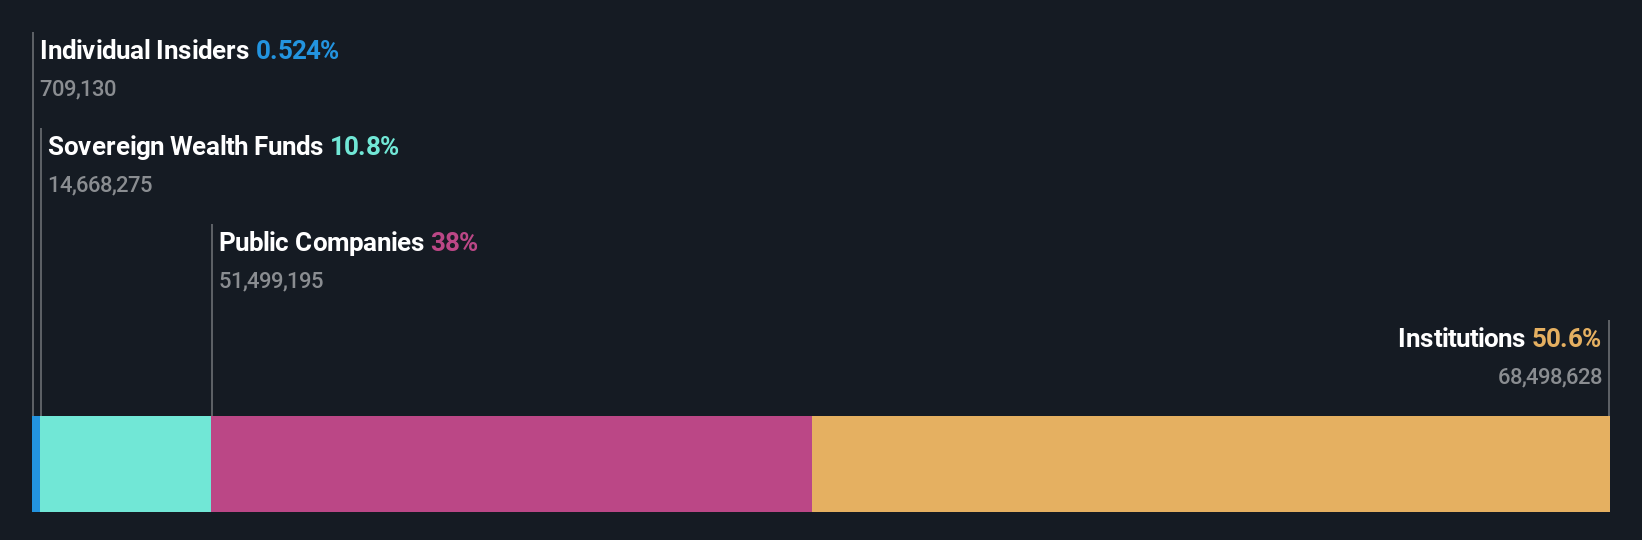
Summing It All Up
- Access the full spectrum of 67 Undervalued US Small Caps With Insider Buying by clicking on this link.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com