
Wolters Kluwer (ENXTAM:WKL) Stock May Trade At A Discount Despite Fresh AI Workflow News
Wolters Kluwer shares have fallen sharply over the past year, and that pullback puts fresh focus on whether the current price still lines up with what the business is earning. With new product launches in auto finance and AI-enabled workflows now in the mix, the key issue is how those efforts compare with the stock’s recent slide.
- The share price is down 38.3% over the past 12 months. This raises the question of whether earnings expectations have shifted as much as the stock price has.
- Recent launches in AI driven legal and compliance tools and new vehicle financing documentation can influence how investors think about future profitability and the durability of Wolters Kluwer’s earnings base.
- There is a second opinion on Wolters Kluwer worth weighing. See what analysts think Wolters Kluwer's shares could be worth.
The issue now is whether today’s Wolters Kluwer share price is adequately supported by its earnings profile.
To pressure test whether Wolters Kluwer’s earnings story still fits its share price slide, you can compare it with a wider set of 190 high quality undervalued stocks
Is Wolters Kluwer Still Cheap on Earnings?
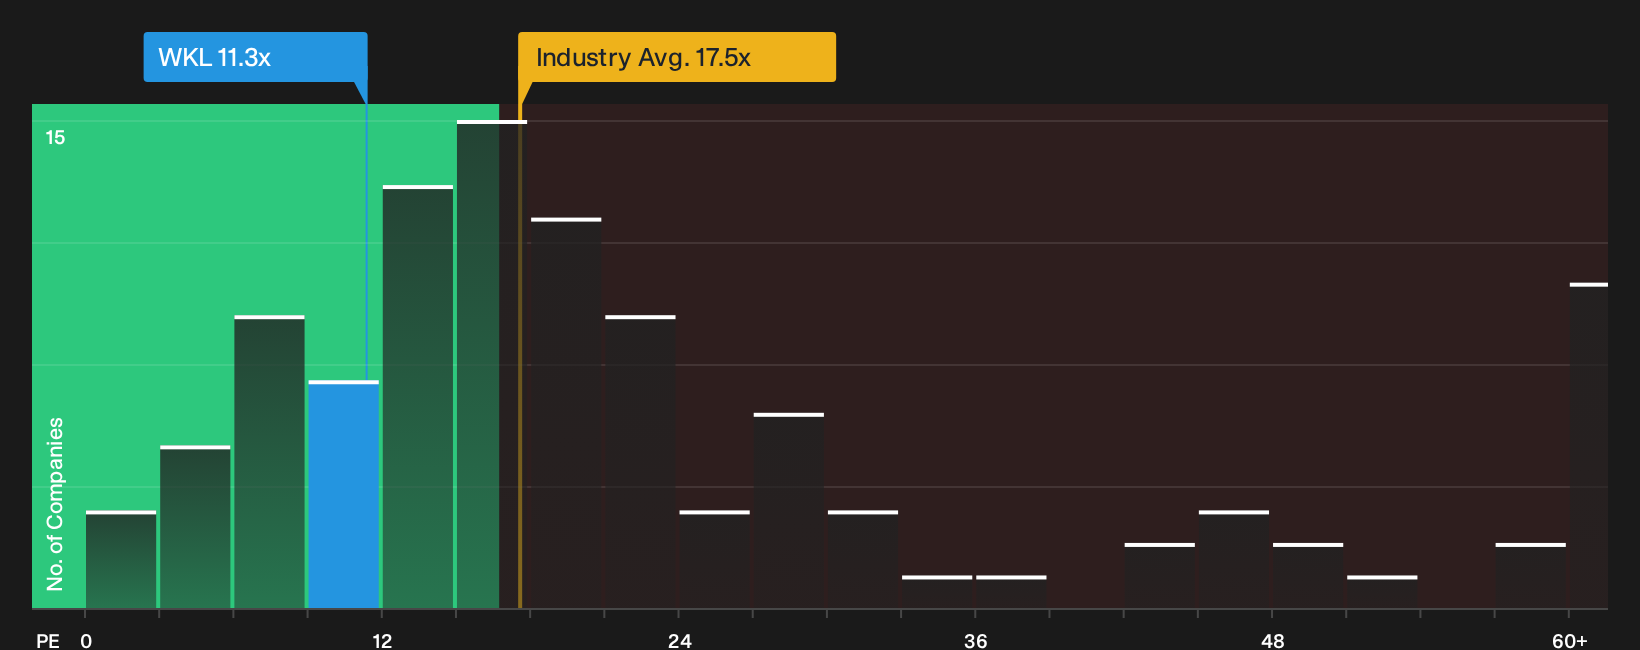
The P/E ratio fits Wolters Kluwer because earnings still drive how investors look at this kind of information and software group. On this measure, the stock trades at about 11.3x earnings, which is well below the Professional Services industry average of roughly 16.4x and also under the broader peer group on about 25.9x. That gap indicates the market is putting a lower earnings multiple on Wolters Kluwer than on a typical listed rival.
Because of the new Libra AI workflow rollouts and auto finance documentation launches, the discount looks even more striking when set against the tailored fair P/E level that accounts for Wolters Kluwer’s margins, risk profile and sector. The current ratio comes in below that customised benchmark, which suggests the shares are pricing in a weaker earnings profile than the model indicates. For anyone weighing whether the recent share price drop has overshot, this P/E gap is a key piece of the puzzle. Explore the numbers behind Wolters Kluwer's P/E valuation.
The Wolters Kluwer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Wolters Kluwer valuation puzzle leaves off, since each scenario spells out what kind of growth path, margin profile, and earnings power would need to hold for the stock to be worth materially more or less than today's price on the Community page. Each narrative treats Wolters Kluwer's fair value as a clear thesis about the business that you can revisit over time to see how it holds up against new information.
Community views on Wolters Kluwer are split between those who see resilient economics and those who see AI and mix shift weighing on the story.
Bull case: 27% undervalued
"Currently the company demonstrates strong operating margins of 26%, evidencing both competitive advantages and pricing power…"
Discover why this Narrative puts Wolters Kluwer at 27% undervalued.
Bear case: 12% overvalued
"Despite rapid proliferation of generative and Agentic AI features across major product suites, the heavy upfront R&D and platform costs, combined with uncertain willingness of customers to pay explicit AI premiums, could dilute the contribution of these innovations to net margins and earnings over the next few years…"
Explore why this Narrative puts Wolters Kluwer at 12% overvalued.
The Wolters Kluwer share price is only one piece of the decision
Price and earnings tell part of the story for Wolters Kluwer, but the research checks also highlight specific risk signals that deserve a closer look before you commit fresh capital. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com