
Sustainable Dividend Might Change The Case For Investing In KDDI Stock (TSE:9433)
- KDDI recently paid a total dividend of $0.26 per share, with a payout ratio of 0.42 that is supported by existing profitability and retained earnings.
- The combination of a moderate payout ratio and ongoing service expansion indicates that KDDI is seeking to balance shareholder income with internal reinvestment capacity.
- Next, attention will turn to how this dividend, backed by a 0.42 payout ratio, could influence KDDI's broader investment narrative.
Scan beyond KDDI and line up other income-focused opportunities by reviewing our curated list of 20 dividend fortresses in similar mature, cash-generating sectors.
KDDI Investment Narrative Recap
To own KDDI, you need to be comfortable with a telecom group that relies on a mature domestic market while seeking to generate more value from each user through 5G and bundled services such as au PAY, banking and energy. The recent $0.26 per share dividend with a 0.42 payout ratio fits that story as a steady, sustainability focused cash return rather than a new direction.
The near term swing factor is execution on high capacity, data heavy plans and digital services that support customer loyalty and average revenue per user in a saturated market. Rising churn, intense price competition and reliance on higher risk funding sources remain the key operational pressure points, and this dividend decision does not meaningfully change those.
The most relevant update tied to this dividend is the indication that KDDI is using current profitability and retained earnings to keep a regular cash distribution while still leaving room for reinvestment. A 0.42 payout ratio sits in the context of earnings that analysts expect to grow, which gives an indication of how management is pacing cash returns against business needs.
Income focused investors may interpret this as a signal of consistency, given commentary that KDDI pays a 2.87% dividend and has high quality earnings. The operational test from here is whether developments in 5G connectivity, fintech partnerships and enterprise services offset slow subscriber additions and tight pricing, so that this kind of dividend decision remains manageable alongside debt and ongoing capital spending.
KDDI's analyst narrative projects ¥6,895.0b in revenue and ¥830.4b in earnings by 2029, based on assumptions of 3.9% yearly revenue growth and an earnings increase of about ¥87.9b from current earnings of ¥742.5b.
Uncover why KDDI's fair value suggests that KDDI is trading roughly in line with its current price.
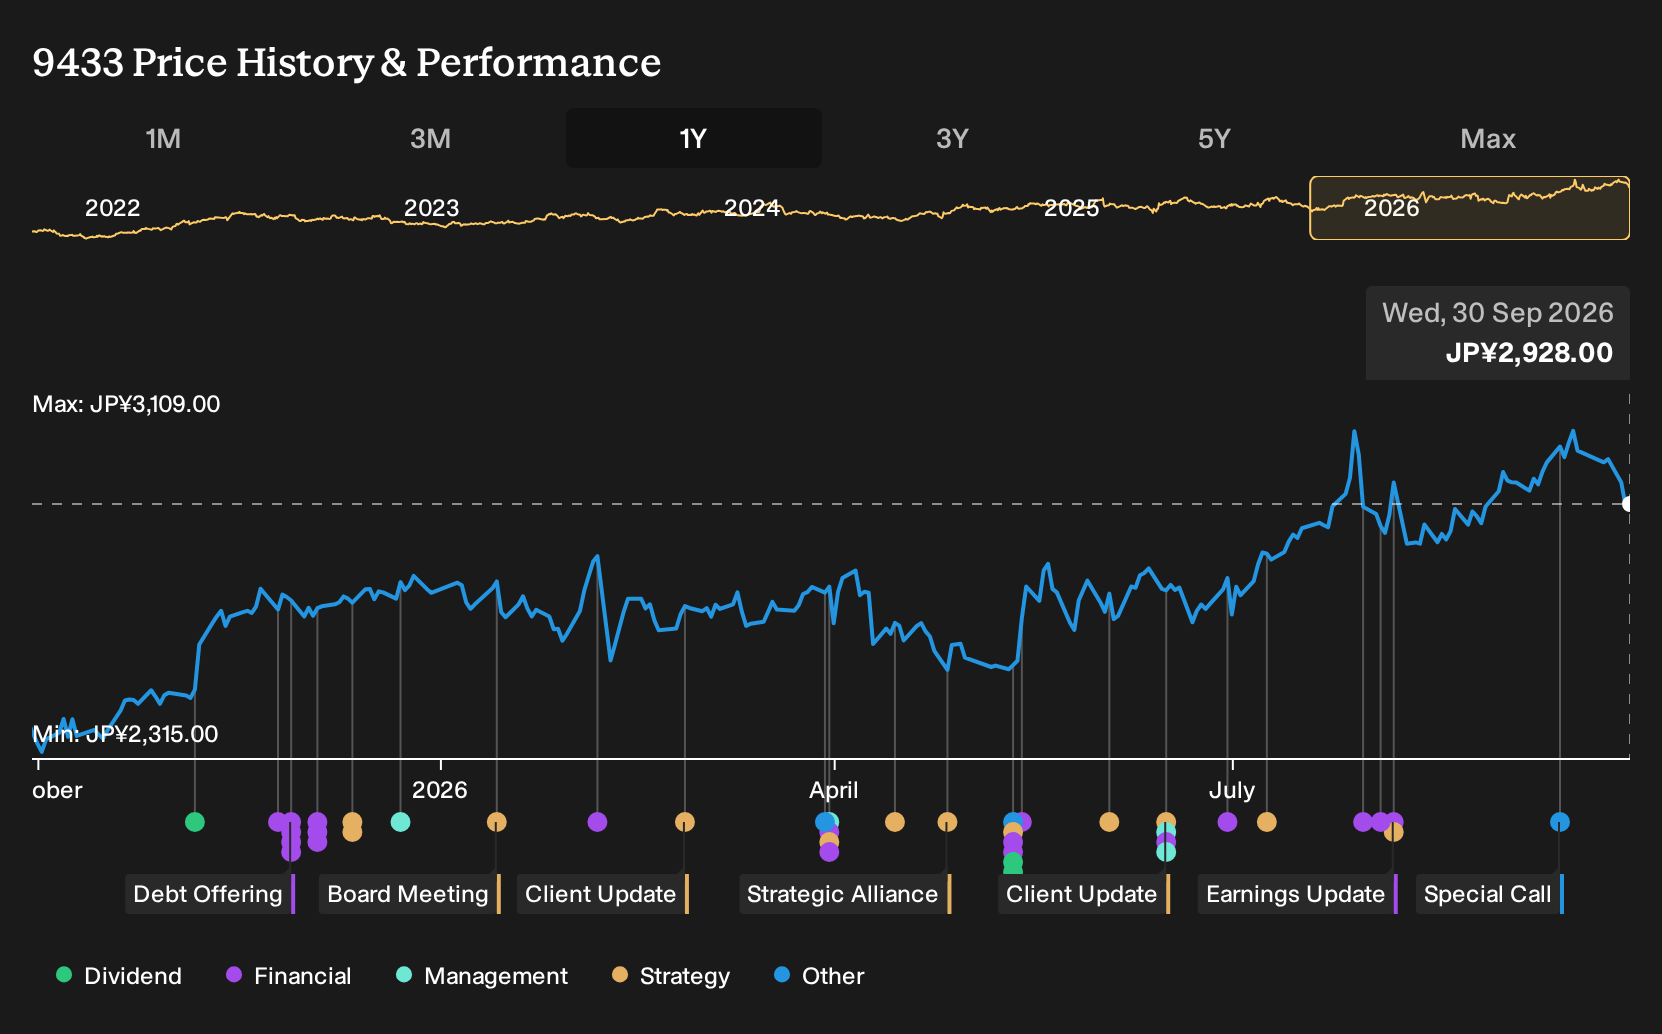
Exploring Other Perspectives
The most cautious analysts focus on execution risk around KDDI’s large-scale digital belt and data center build, arguing that heavy investment might not translate into matching revenue. Their earlier forecasts assumed revenue of ¥6,677.0b and earnings of ¥732.7b by 2029. Use those more pessimistic views to test how this dividend news could reshape expectations.
Explore another KDDI fair value estimate, including one that suggests it could be worth just ¥2,998.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your KDDI research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for KDDI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KDDI's overall financial health at a glance.
Looking for more investment ideas beyond KDDI?
If you want to put KDDI in context and build a broader watchlist, use the Simply Wall St Screener to compare this telecom group with other businesses that match your income, quality or risk profile.
- For investors who want resilient balance sheets and steady fundamentals, filter for companies using our list of solid balance sheet and fundamentals (23 results).
- If you are hunting for strong businesses that the market may be overlooking, scan through the 76 high quality undiscovered gems to spot ideas that rarely hit mainstream lists.
- If you prefer to keep downside risk in tighter check, even if it means a shorter idea list, then focus on companies highlighted in the 21 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com