
ABM Industries (ABM) Stock Could Be A Bargain Following Its 28% Run
ABM Industries has delivered a solid 3 year share price gain while expanding into higher growth areas such as semiconductor facilities and data centers, which puts the focus firmly on whether the current US$48.10 price is adequately supported by the cash the business can generate. Recent headlines around record revenue and a higher earnings outlook only sharpen the question of how much of that story is already reflected in today's valuation.
- The stock is up 27.6% over 3 years, so a meaningful part of any future return could hinge on how closely the cash flows match what is already implied in the price.
- Record revenue and growth in higher value segments like semiconductor services can shift expectations for margins and capital needs, which directly affects the timing and durability of future cash inflows.
- What if you looked at ABM Industries through its earnings instead? See why ABM Industries's 16.9x P/E tells a different valuation story.
For investors, the debate is whether ABM Industries' current share price is justified by the intrinsic value suggested by its cash flows under a Discounted Cash Flow (DCF) view.
If you want a broader watchlist while you assess whether ABM Industries' cash flows justify the current price, you may want to start with a focused screen of 31 high quality undervalued stocks.
Does ABM Industries Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here uses ABM Industries' projected free cash flows to estimate what the equity could be worth today. Over the last twelve months the group produced roughly $326.9 million in free cash flow, and the forecast path points to levels in a similar range over the next decade rather than steep expansion or collapse. That profile fits a business that investors might treat as relatively steady, where the DCF outcome becomes very sensitive to the discount rate and long term growth assumption baked into the model.
The projections used in this DCF show ABM Industries' estimated intrinsic value substantially above the current share price of $48.10. Recent news around record $2.3b revenue and a raised earnings outlook helps explain why analysts are paying close attention to how much of the semiconductor and data center opportunity is already reflected in that gap. The DCF result suggests the market price has not fully closed it yet, which is where the detailed cash flow work becomes most useful for your own view. Find out what ABM Industries could be worth using our Discounted Cash Flow (DCF) estimate.
The ABM Industries Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the ABM Industries valuation puzzle leaves off and spell out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today, all on the Community page. Each Narrative treats ABM Industries' fair value as a thesis you can track over time, so you see how well the underlying logic holds up as new information arrives.
One of the top community narratives on ABM Industries: 13% undervalued
"Expansion in electrification and data centers, plus cost efficiencies and contract wins, are cited by some observers as potential drivers of earnings and margins for ABM…"
Discover why this Narrative puts ABM Industries at 13% undervalued.
One more piece of the ABM Industries puzzle
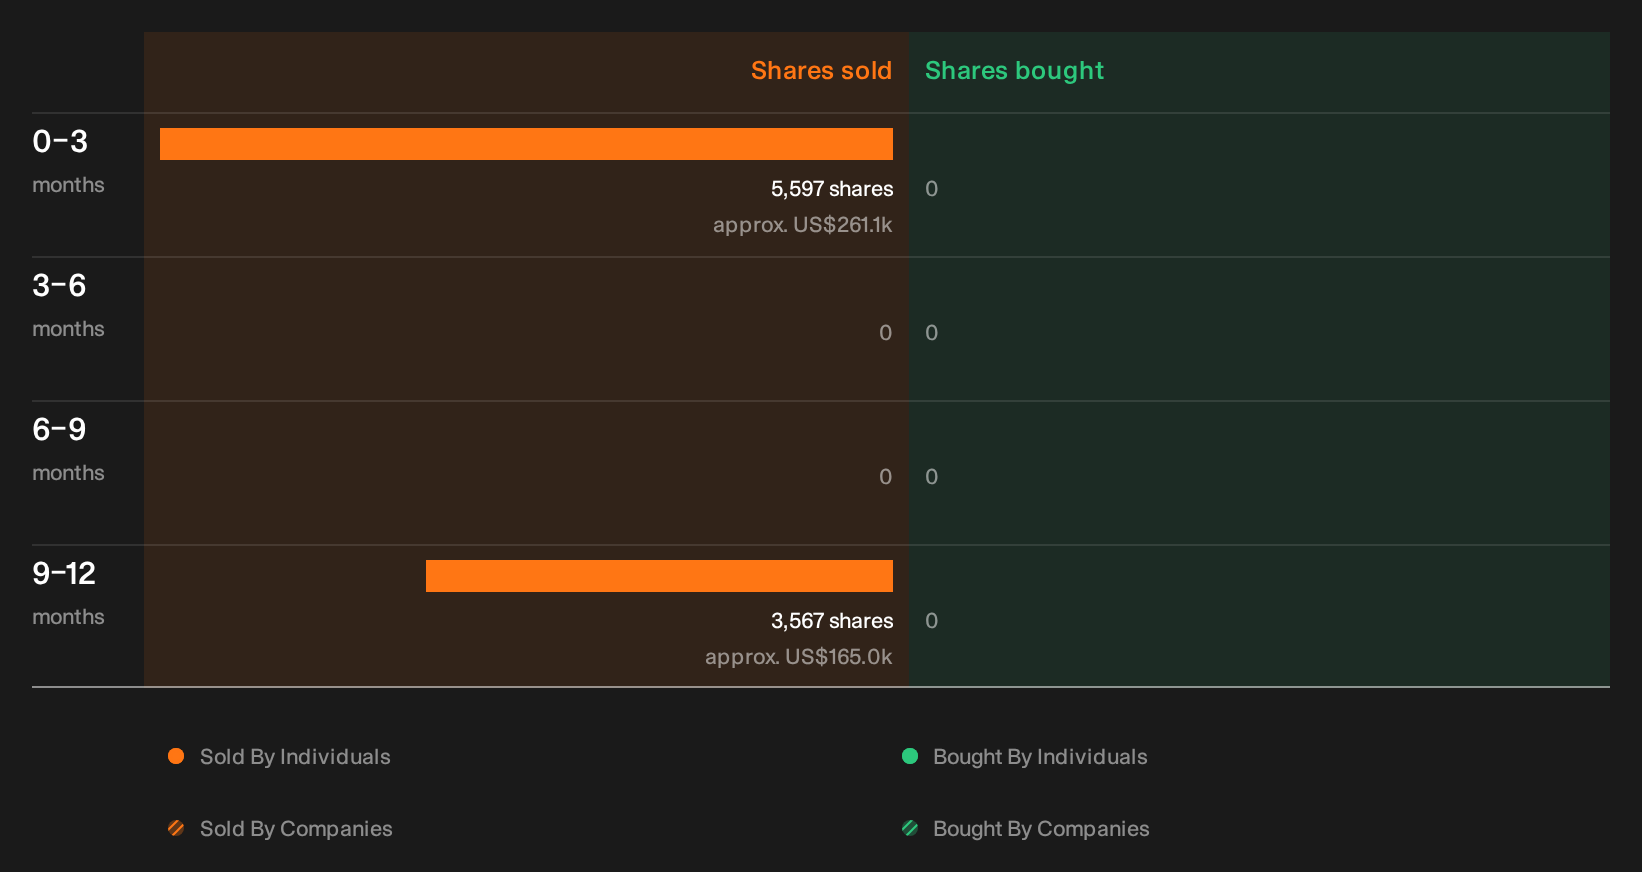
Valuation work is only part of the picture for ABM Industries, and the recent insider share sales flagged by our checks raise a separate line of questions about who sold, how much, and why. See the recent insider selling flagged for ABM Industries.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com