
Did Earnings Upgrades Just Shift Materion (MTRN) Stock's Investment Narrative?
- Materion has recently been highlighted with a top-tier Zacks Rank #1 (Strong Buy), reflecting improving consensus EPS expectations supported by strength across key end markets such as semiconductors, energy infrastructure, and aerospace.
- The key insight is that analysts are rewarding Materion’s shift toward higher value engineered materials and operational efficiencies, which together reinforce the view that earnings quality is improving rather than relying solely on volume growth.
- We will now look at how Materion's earnings outlook could influence the existing investment narrative built around its end markets.
Scan how Materion’s earnings story compares with other Basic Materials opportunities by reviewing our hand picked 19 high quality undiscovered gems in the sector.
Materion Investment Narrative Recap
To own Materion, you need to be comfortable with a business that leans heavily on semiconductors, aerospace, and energy, and is pushing deeper into higher value engineered materials rather than pure volume. The near term swing factor is how cleanly that mix shift turns into steadier margins as demand in chips and defense holds up or softens.
The biggest operational risk right now sits in that same concentration. Any slowdown in those key customers, added pressure from lower priced Chinese semiconductor suppliers, or raw material issues in specialty metals can quickly show up in earnings volatility. The latest news does not seem to alter those core drivers in a material way.
The most relevant recent development for this update is the stronger earnings outlook that has Materion ranked alongside Methanex in the Basic Materials group, with Materion carrying the stronger Zacks rating. That recognition ties directly back to its push into engineered solutions and operational efficiency, which matters more than short term volume swings.
For catalysts, that improving earnings profile sits next to several watchpoints. Materion still carries a relatively high P/E versus peers, relies on higher risk funding through external borrowing, and faces concentrated exposure to cyclical end markets. Execution on margin quality and capital discipline will likely be what investors track most closely against that backdrop.
Materion Earnings Outlook and Embedded Assumptions
Materion's narrative projects US$3.0b revenue and US$296.8m earnings by 2029. This implies 12.9% yearly revenue growth and an earnings increase of about US$206.7m from US$90.1m today.
Uncover why Materion's fair value indicates a 12% potential upside to its current price, which could close sooner than many investors expect.
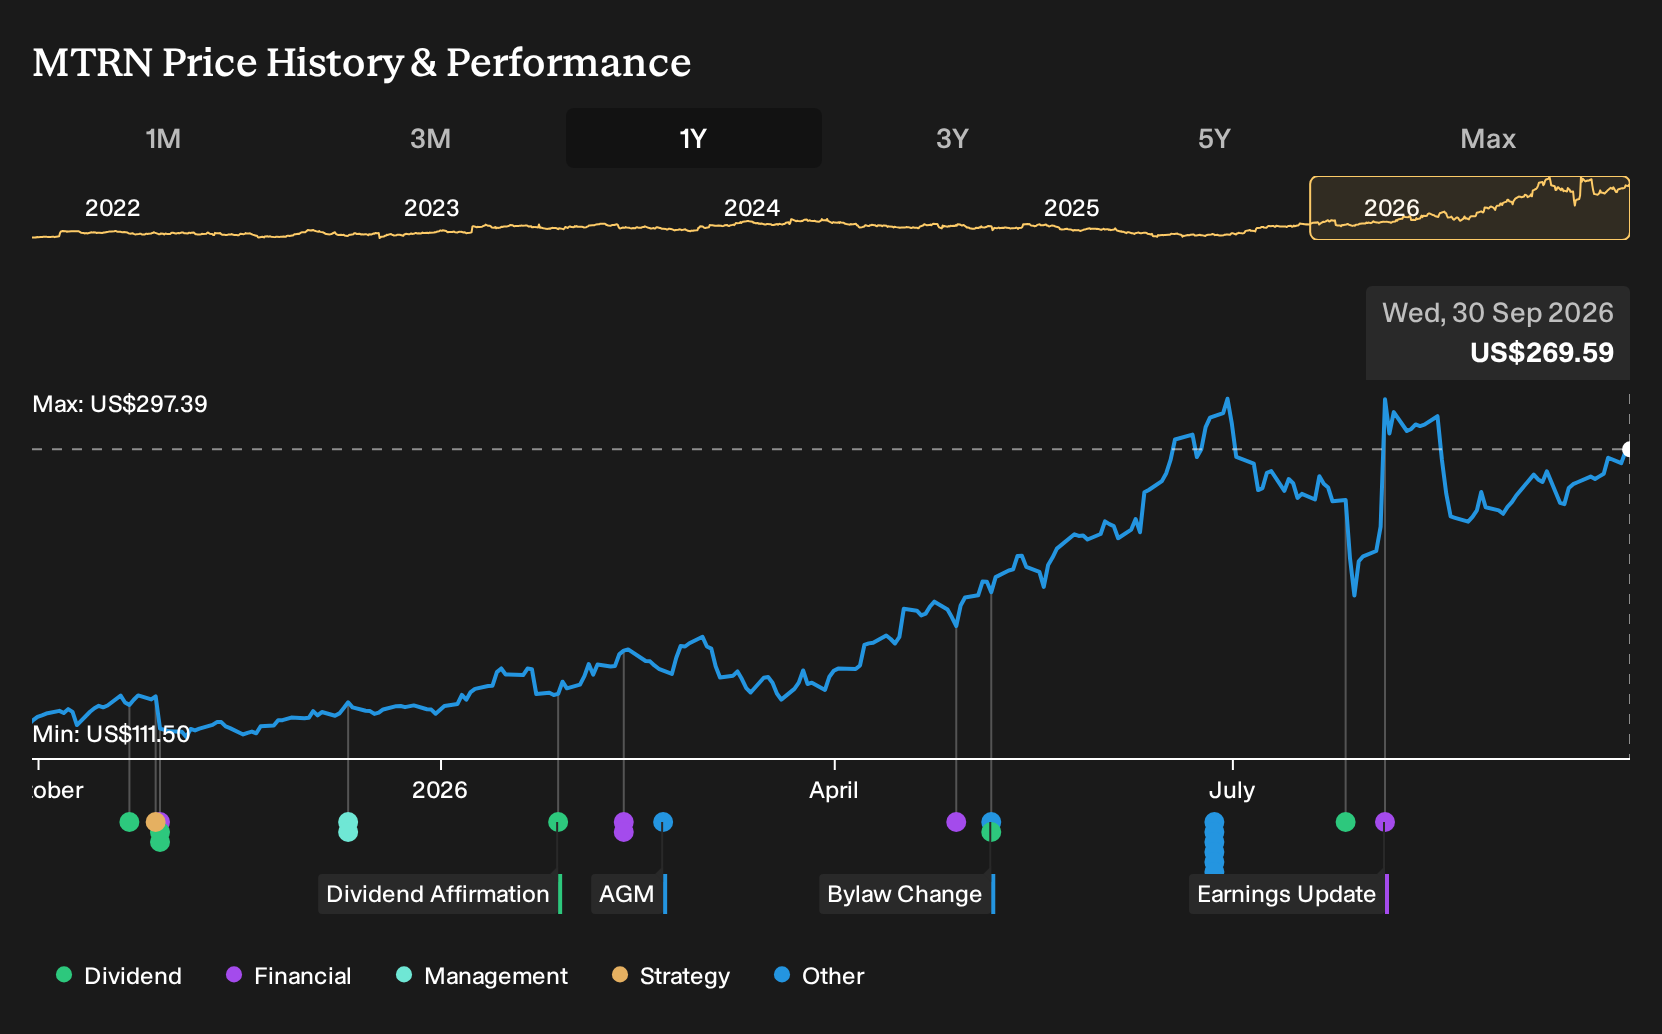
Exploring Other Perspectives
The lowest analysts on Materion focus on capital intensity as the swing factor. They see US$2.9b revenue and US$282.3m earnings by 2029 as more realistic, with a 27.0x P/E on those numbers. That is a more cautious story than consensus, and the fresh earnings news could push either side to revisit those assumptions.
Explore 2 other Materion fair value estimates, including one that suggests it could be worth just $301.18.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Materion research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Materion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Materion's overall financial health at a glance.
Looking For More Ideas Beyond Materion?
If Materion has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can surface other opportunities that fit the kind of risk and quality mix you care about.
- If you want potential mispricing with quality to back it up, scan a curated 31 high quality undervalued stocks that combine robust fundamentals with room for a re rating.
- If capital preservation and balance sheet strength matter most to you, start with a list of solid balance sheet and fundamentals (25 results) that have the financial resilience to handle tougher conditions.
- If you are hunting for overlooked opportunities, filter through a 19 high quality undiscovered gems that pair solid business profiles with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com