
Solaris Energy Infrastructure (SEI) Beat Estimates And Bought Mobile Energy Rentals, Is It Still Undervalued?
Solaris Energy Infrastructure (SEI) has drawn fresh attention after beating analyst expectations on both revenue and earnings in its latest quarter, along with its acquisition of Mobile Energy Rentals and its growing exposure to distributed power.
The recent Q2 beat and Mobile Energy Rentals deal have coincided with a sharp shift in mood around Solaris Energy Infrastructure, with a 1 month share price return of 40.2% and a 1 year total shareholder return of 69.6% indicating strong momentum alongside a very large 5 year total shareholder return that is close to 10x the initial investment.
Scan other energy infrastructure stocks that show similar momentum and balance sheet scale to Solaris Energy Infrastructure by using the hand picked 39 power grid technology and infrastructure stocks
After a 40% jump in a month and a 1 year total return near 70%, is Solaris Energy Infrastructure still offering meaningful upside at a US$71.18 share price, or has most of the opportunity already played out in the stock?
Most Popular Narrative: 27% Undervalued
At a last close of $71.18 versus a widely followed fair value estimate of $97.20, Solaris Energy Infrastructure screens as materially cheaper than that narrative implies, which puts the recent rally in a different light for anyone focused on longer term cash flows.
The accelerating demand for grid resiliency, electrification of industries, and AI-driven data center power needs is creating strong, ongoing demand for Solaris's modular, scalable power generation solutions, which some observers view as positioning the company for significant revenue growth as delivery of new capacity ramps through 2026 and beyond.
See why 23 investors see Solaris Energy Infrastructure as 27% undervalued.
Result: Fair Value of $97.20 (UNDERVALUED)
Still, the bullish Solaris Energy Infrastructure story can be knocked off course if the strength of one-off Power Solutions fades, or if project delays and cost overruns bite.
Find out about the key risks to this Solaris Energy Infrastructure narrative.
Another View On Solaris Energy Infrastructure’s Price Tag
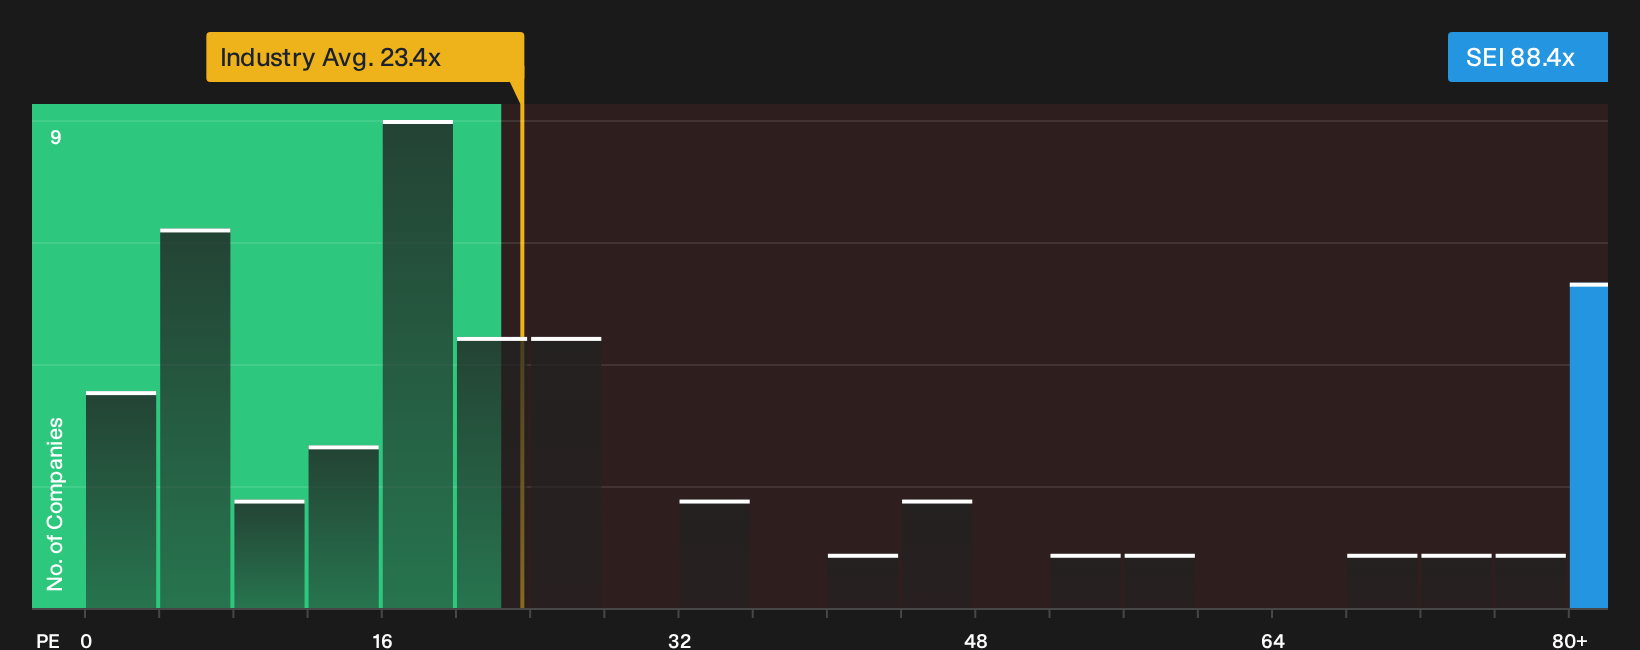
The first story paints Solaris Energy Infrastructure as undervalued on fair value and cash flow estimates. A very different picture appears when you look at the P/E. SEI trades on 88.4x earnings, compared with a fair ratio of 28.2x, the US Energy Services sector at 23x and peers at 38.5x. That is a steep premium. The question is whether you think future execution and growth justify paying that kind of mark up.
See what the numbers say about this price in our valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Solaris Energy Infrastructure is split, with clear optimism and some pointed concerns sitting side by side. It makes sense to review the full picture yourself now and pressure test the story from both angles using the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Solaris Energy Infrastructure?
If Solaris Energy Infrastructure has sharpened your focus on pricing, risk and quality, broaden your watchlist now so you are not relying on a single opportunity.
- Target potential mispricing by scanning a curated set of quality companies that look cheap on fundamentals through the 31 high quality undervalued stocks.
- Strengthen your income stream by hunting for resilient payers using the 7 dividend fortresses.
- Dial down portfolio stress and focus on resilience with the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com