
AXT (AXTI) Gets Earnings Upgrades, Is It Fully Priced?
AXT (AXTI) has been drawing fresh attention after analysts recently raised earnings estimates without any offsetting cuts, a shift in expectations that coincides with strong Zacks rankings and renewed interest in the stock’s momentum profile.
AXT’s share price has climbed 27.72% over the past 30 days and 36.72% over 90 days, with the stock now at US$77.41. The year-to-date share price return of 361.87% sits alongside a very large 1-year total shareholder return and multi-year gains in the thousands of percent, which together indicate strong momentum built over time rather than a short-term spike in sentiment.
Scan for other momentum stories with earnings upgrades similar to AXT by checking our hand picked list of 19 high quality undiscovered gems.
AXT has already delivered enormous gains on the chart, yet analyst targets and earnings upgrades still point to further optimism. How much of that enthusiasm does the current valuation already capture?
Most Popular Narrative: 16% Undervalued
AXT’s most followed narrative points to a fair value of $91.60 against the last close at $77.41. This frames the recent rally as still short of what that framework considers full value when applying an 11.31% discount rate to future cash flows.
Accelerating global demand for high-speed data center connectivity and AI infrastructure is driving increased adoption of indium phosphide substrates, where AXT is a top supplier with 40% share. As export permit headwinds ease, this pent-up demand is expected to produce sharp revenue growth and improved utilization of manufacturing capacity.
See why 42 investors see AXT as 15% undervalued.
Result: Fair Value of $91.60 (UNDERVALUED)
Still, AXT’s heavy exposure to Chinese customers and ongoing export permit uncertainty could quickly unsettle that optimism if orders slow or shipments are delayed.
Find out about the key risks to this AXT narrative.
Another View: AXT Looks Expensive On Sales
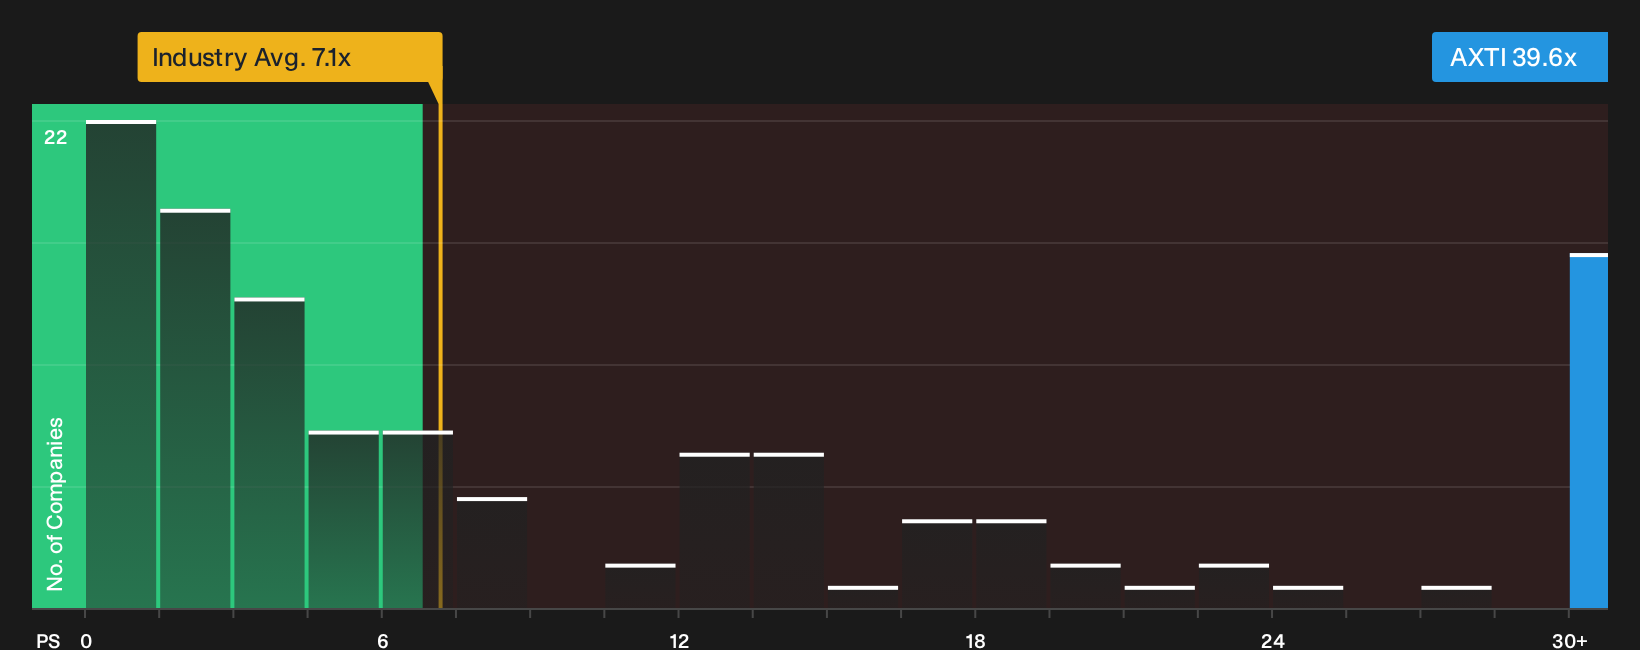
The SWS DCF model sees AXT as undervalued at $91.60, yet the P/S picture points in a different direction. At 39.6x sales versus a US Semiconductor average of 7.1x and a peer mark of 6.6x, the stock trades at a substantial premium to today’s revenue base.
The fair ratio is estimated at 25.6x, which is still well above industry and peer levels but below the current 39.6x. That gap highlights valuation risk if sentiment cools or growth expectations reset. How comfortable are you paying this kind of multiple for the current business mix?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Momentum in AXT divides opinion. This is exactly why it helps to review the underlying data yourself, weigh both the optimism and the caution, and then ground your decision in the 2 key rewards and 3 important warning signs.
Looking for more AXT-style investment ideas?
If AXT has sharpened your focus on momentum and valuation, do not stop here. Use the tools at your disposal and give yourself more quality options.
- Hunt for stronger value opportunities by scanning a curated pool of companies on our 32 high quality undervalued stocks.
- Prioritise durability by checking out a list of solid balance sheet and fundamentals (25 results) that can help you focus on financial strength first.
- Dial back risk by filtering for 31 resilient stocks with low risk scores that can help keep your portfolio from depending on a single high volatility story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com