
Ingram Micro Holding (INGM) On Upgrade And Opengear Deal Still Looks Undervalued
Ingram Micro Holding (INGM) is back in focus after two catalysts hit in quick succession. An analyst upgrade highlighted a brighter earnings outlook, and a fresh Opengear distribution deal broadened its European reach.
Recent trading has cooled slightly, with Ingram Micro Holding’s share price down 4.83% over the past 30 days and 1.83% over the last week, even after the analyst upgrade and Opengear deal headlines. Yet the 25.81% year to date share price return and 22.69% one year total shareholder return suggest that momentum has been building over the longer stretch, as investors weigh a stronger earnings outlook against short term position adjustments around the news flow.
Compare Ingram Micro Holding’s recent upgrade and Opengear catalyst with other potential breakouts by scanning our curated list of 19 high quality undiscovered gems in similar segments.
The question now is whether Ingram Micro Holding’s pullback after strong year to date gains reflects a cooler view on the business itself or simply sentiment resetting around the upgraded earnings story and the new Opengear deal.
Most Popular Narrative: 19% Undervalued
Ingram Micro Holding’s most followed narrative points to a fair value of about $33.17 per share compared with the recent $26.81 close. This frames the pullback as a gap between current pricing and what analysts expect the business to earn over time.
Rapid adoption of AI driven enterprise solutions, supported by Xvantage, IDA and the new Sales Briefing Assistant, is expected to convert current proof of concept activity into scaled deployments that lift advanced solutions and services revenue while supporting higher quality earnings over time.
See why 1 investors see Ingram Micro Holding as 19% undervalued.
Result: Fair Value of $33.17 (UNDERVALUED)
Still, the narrative can break if low margin GPU and server deals crowd out higher margin categories, or if cloud growth lags broader software spending trends.
Find out about the key risks to this Ingram Micro Holding narrative.
Another View: Cash Flows Paint A Stricter Picture
The first story around Ingram Micro Holding leans on earnings forecasts and P/E based fair value. A second lens tells something different. Our DCF model points to a future cash flow value of $17.15 per share, which sits well below the recent $26.81 price and flags the stock as overvalued on this metric.
That gap implies investors may be putting a richer price on INGM’s cash generation than the model supports, which raises a question for you: Is the cash flow profile simply being underestimated, or is the earnings based upside already baking in a lot of hope?
Look into how the SWS DCF model arrives at its fair value.
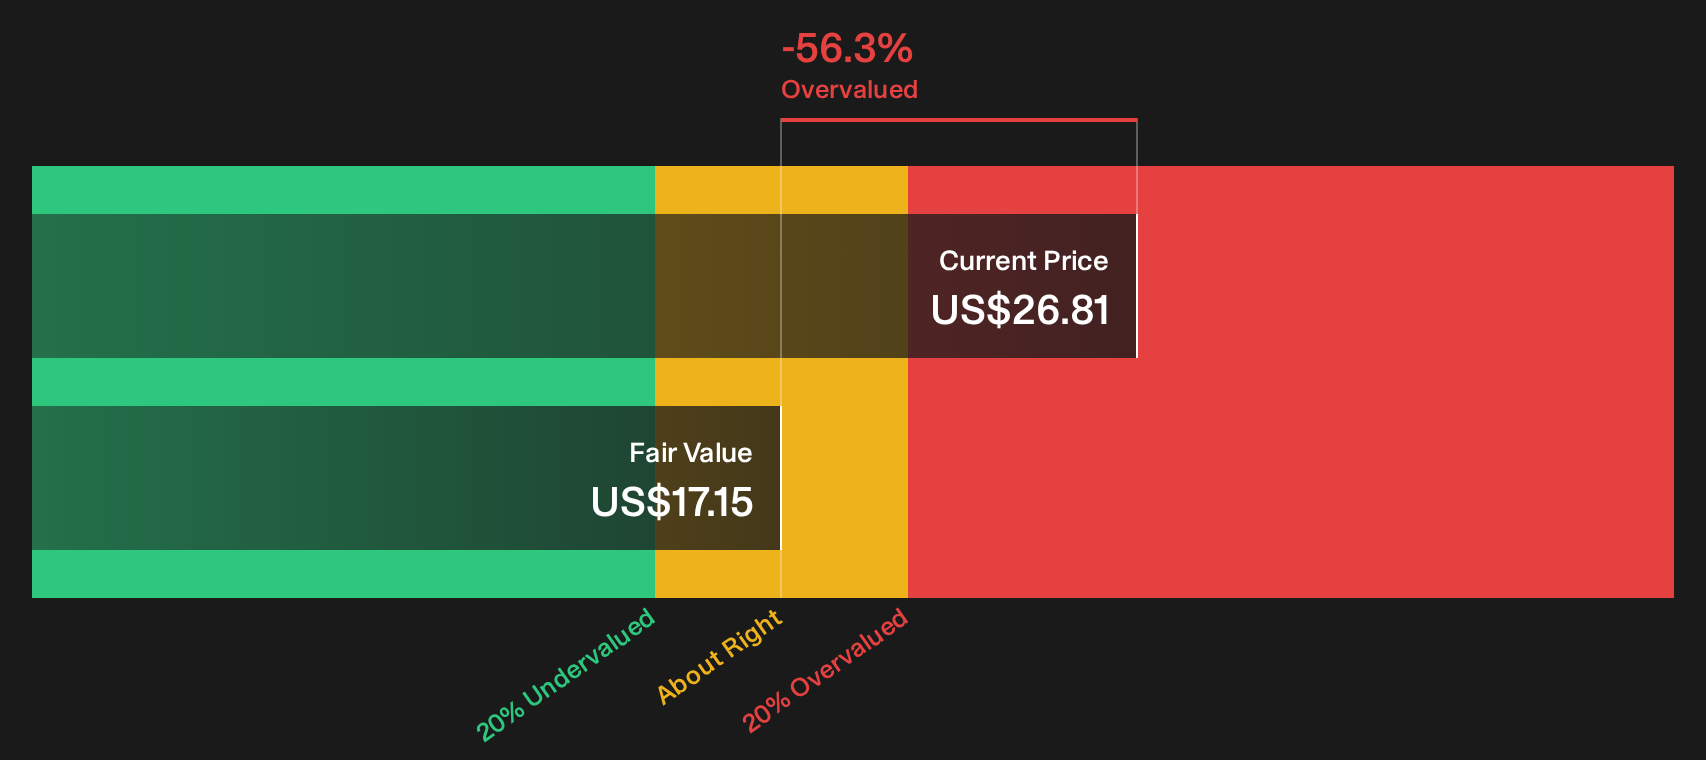
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ingram Micro Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Ingram Micro Holding so far, right. If you want to move before the next headline hits, start by weighing both sides of the story and scrutinising the 5 key rewards and 1 important warning sign.
Looking for more Ingram Micro Holding investment ideas?
If you want to keep your edge after reviewing Ingram Micro Holding, use fresh stock ideas from targeted screeners so you are not relying on one story.
- Target potential upside with high quality companies that combine solid fundamentals and discounted prices through the 32 high quality undervalued stocks.
- Prioritise resilience and sleep easier at night by filtering for businesses with stronger balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Lock in income focused opportunities by scanning companies with robust yields and consistent payouts using the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com