
Verizon (VZ) Stock Looks Cheap Following Its 78% Three Year Run
Verizon Communications has delivered a strong multi year share price run, and after a softer recent patch the question is whether the current US$45.87 price is still well supported by what the business earns.
- The stock has returned 77.8% over the past 3 years, which puts real pressure on the idea that its present valuation can be explained by earnings alone.
- Verizon's US$70 million commitment to free AI training and broader digital skills programs may support expectations for future connectivity demand and, in turn, the durability of its earnings base.
- The analysts covering Verizon Communications have run their own numbers. See what analysts think Verizon Communications's shares could be worth.
The issue now is whether Verizon's current share price is appropriately aligned with the earnings power that investors can see today.
If you are weighing Verizon Communications against other ways to play this theme, it can help to compare it with companies in the 90 AI infrastructure stocks.
Does Verizon Communications Look Undervalued on Earnings?
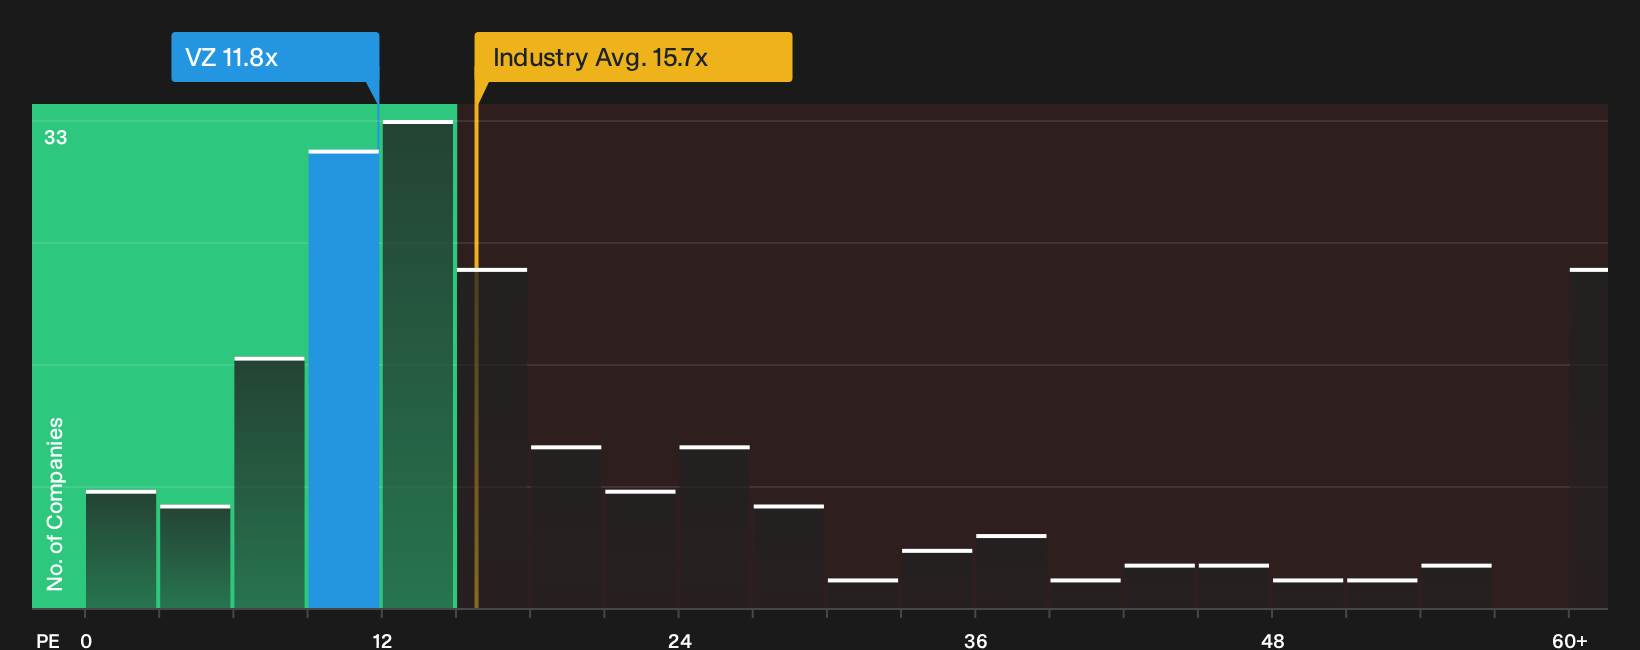
The P/E ratio suits Verizon Communications because earnings are still the main anchor for how investors frame this telecom giant. Verizon trades on a P/E of 11.8x, which sits above the peer average of 9.1x but below the wider Telecom industry on 15.7x. That suggests the stock is priced richer than closer competitors yet not as heavily as some larger sector players.
On this framework, the multiple sits below what a tailored fair P/E would suggest for Verizon once factors like its margins, scale and risk profile are blended in. As a result, the shares screen undervalued on earnings. Because the recent US$70 million AI skills initiative aims to support long term connectivity demand and digital adoption, the P/E discount to that fair yardstick implies the market is not fully crediting those ambitions in the current price. Explore the numbers behind Verizon Communications's P/E valuation.
The Verizon Communications Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that valuation puzzle around Verizon Communications and spell out which expectations on growth, margins and earnings would need to hold for the stock to be worth meaningfully more or materially less than today’s price. These Narratives sit on the company’s Community page. Each one treats fair value as a thesis you can track over time so investors can see how the underlying business case holds up.
Community views on Verizon Communications are split between holders who see more upside in the current setup and others who think expectations are already well reflected.
Bull case: 11% undervalued
"Digital transformation among enterprises and increased remote work are sustaining demand for Verizon Communications private network and AI enabled connectivity offers…"
Discover why this Narrative puts Verizon Communications at 11% undervalued.
Bear case: roughly fairly valued
"The plan to reach 40 million to 50 million fiber passings over the medium term, including at least 2 million new passings in 2026 and continued fixed wireless access expansion, could require sustained heavy capital and integration spending that constrains revenue growth if broadband demand or pricing do not keep pace…"
Explore why this Narrative puts Verizon Communications at roughly fairly valued.
Before acting on Verizon Communications valuation, there is one more angle to weigh
Who actually steers Verizon Communications, how their pay is structured, and whether those incentives truly line up with long term shareholders is the next piece to examine. See who runs Verizon Communications and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com