
Is Barrick Mining (B) Cheap After Its US$1.5b Shareholder Payout?
Barrick Mining (NYSE:B) put capital returns in focus in Q2 2026, sending US$1.5b back to shareholders through dividends and buybacks, while keeping funds available for future projects.
The recent Q2 cash return sits against a softer near term share price backdrop, with Barrick Mining’s stock down 9.28% on a 1 month share price basis and 7.74% year to date. At the same time, total shareholder return reaches 23.17% over 1 year and more than doubles over 3 and 5 years, suggesting long term holders have been rewarded while short term momentum has cooled.
Scan beyond Barrick Mining and compare its capital return story with a curated group of peers through the 7 dividend fortresses to see how other cash returning businesses stack up.
Barrick Mining is throwing off cash and rewarding long term holders, yet the share price has cooled in recent months. Does that combination still leave you paying a fair price today?
Price-to-Earnings of 10.3x: Is it justified?
Barrick Mining closed at $40.67, and on a P/E of 10.3x it is being valued well below several comparison points, including peers, the broader US market, and an estimated fair P/E level.
The P/E ratio compares the share price to earnings per share, so it gives you a simple shorthand for how much investors are paying for each dollar of profit. For a miner like Barrick Mining that already generates earnings and cash returns, P/E is a direct way to see what the market is willing to pay for its current profit stream.
On the numbers provided, the stock trades on a P/E of 10.3x, which is lower than the US Metals and Mining industry average of 20x, below the peer average of 17.4x, and beneath the estimated fair P/E of 21.8x. That combination indicates the market is pricing Barrick Mining more conservatively than both sector benchmarks and the level suggested by the fair ratio analysis.
Explore the SWS fair ratio for Barrick Mining.
Result: Price-to-Earnings of 10.3x (UNDERVALUED)
Still, the Barrick Mining story can be knocked off course if commodity prices weaken or if large projects consume more cash than expected.
Find out about the key risks to this Barrick Mining narrative.
Another View: Our DCF Model Says Overvalued
The P/E points to value for Barrick Mining, but the SWS DCF model tells a different story. At $40.67, the shares sit above an estimated future cash flow value of $34.34, which, on that lens, signals overvaluation. Which lens you lean on depends on how much weight you put on long term cash flow forecasts.
Look into how the SWS DCF model arrives at its fair value.
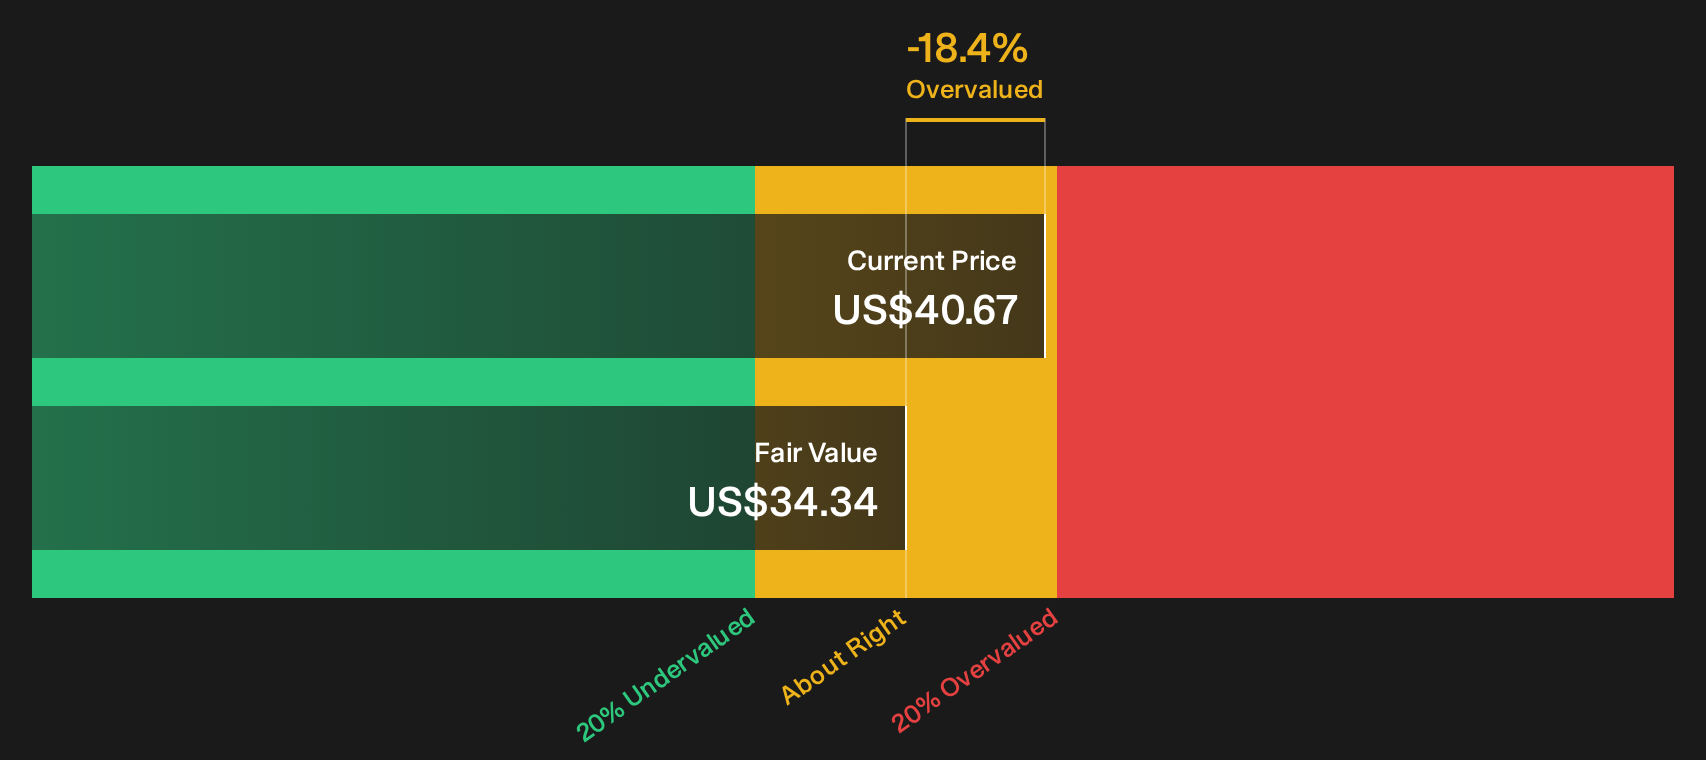
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barrick Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Barrick Mining can feel messy, so move quickly, dig into the numbers, weigh the risks and rewards, then test your view against the 4 key rewards and 2 important warning signs.
Looking for more Barrick Mining sized ideas?
You have seen how mixed readings on Barrick Mining can sharpen your thinking. Now push that edge further by hunting for other opportunities before the crowd notices.
- Scan for quality at a discount and see which companies pass the high bar in the 33 high quality undervalued stocks.
- Zero in on resilience and stress test your defensives against the 31 resilient stocks with low risk scores.
- Get ahead of the herd and uncover future standouts hiding in the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com