
Main Street Capital (MAIN) Stock Looks Overvalued Despite Its 96% Five Year Gain
Main Street Capital has delivered a strong 5 year share price gain, yet the question now is whether the returns it earns on its capital still justify where the stock trades today. Recent pullbacks sit against a longer record of gains and steady income headlines, which puts the focus squarely on how efficiently the business is compounding shareholders' money.
- The share price has gained about 95.8% over the past 5 years, which raises the issue of whether that performance is fully backed by the returns the business generates on its invested capital.
- Recent coverage has highlighted a long history of monthly and supplemental dividends supported by investments in secured debt and equity of smaller private companies, which can influence how much value Main Street Capital extracts from every dollar it commits to these deals over time.
- Prefer to judge Main Street Capital on earnings? See what Main Street Capital's 11.4x P/E says about the price.
The issue now is whether the level and durability of returns Main Street Capital earns on its capital are strong enough to support the current share price after this mix of long term gains and recent softness.
To assess whether Main Street Capital's return on capital profile is unusual or fairly typical, it is helpful to compare it with a broader group of companies screened for 32 high quality undervalued stocks.
Is Main Street Capital Getting Expensive on Excess Returns?
The Excess Returns model looks at how efficiently Main Street Capital turns its equity base into profits above its estimated cost of equity. In this case, the business is assumed to generate stable earnings of $3.37 per share on a stable book value of $31.65 per share, with an average return on equity of 10.66%. Against an implied equity charge of $2.95 per share, that leaves excess return of $0.42 per share on book value of $33.92. This suggests the franchise relies on modest value creation rather than outsized profitability.
The dividend framework in the same toolkit uses recent dividends of $4.29 per share, a payout ratio of 55.49%, and a capped growth rate of 3.7%. It arrives at a present value that sits substantially below the current share price of $55.05. The long history of growing monthly and supplemental dividends highlighted in recent coverage helps explain why investors appear comfortable paying a premium to these modelled excess returns. Find out what Main Street Capital could be worth using our Excess Returns estimate.
The Main Street Capital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle on Main Street Capital leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today. Each narrative sets out the assumptions that sit behind its implied value, so you can track those inputs against Main Street Capital's reported numbers as they come through over time on the Community page.
One of the top community narratives on Main Street Capital: 7% undervalued
"Main Street Capital's robust financial foundation and diversified investment successes suggest potential for continued share price growth contrary to decrease expectations..."
Discover why this Narrative puts Main Street Capital at 7% undervalued.
One more Main Street Capital signal worth checking before you move on
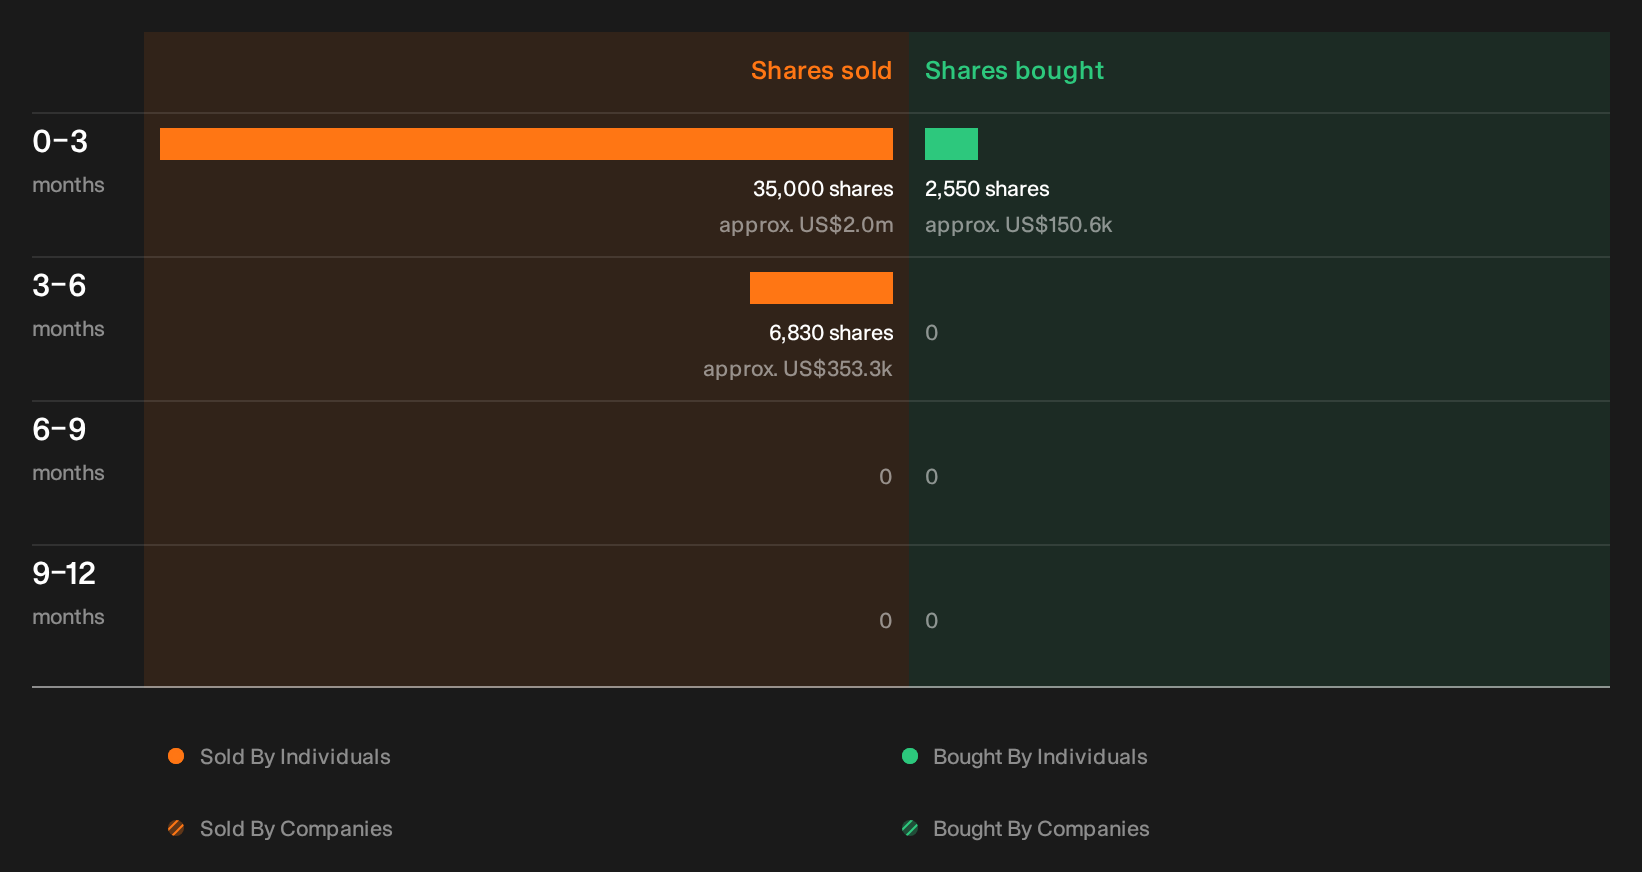
There is one angle on Main Street Capital that this valuation work has not touched yet. Recent checks have picked up insider share sales, and the specific sellers, sizes and possible read throughs are all there for you to review. See the recent insider selling flagged for Main Street Capital.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com