
Argan (AGX) Gains On JP Morgan Support, Is The Valuation Still Too Rich?
Argan (AGX) came into focus after JP Morgan reaffirmed its bullish rating, even as it slightly trimmed its target, and the stock responded with a 6.2% gain on the day.
Beyond the one day reaction, Argan’s 1 year total shareholder return of 35.81% and very large 3 and 5 year total shareholder returns contrast with a share price that has fallen 11.07% over the past month and 46.48% over the past quarter. This signals fading short term momentum after a powerful multi year run.
Scan beyond Argan and see how other engineering and infrastructure contractors with strong recent returns and solid balance sheets stack up in our hand picked list of solid balance sheet and fundamentals (25 results).
Argan just handed shareholders a huge multi year payoff, then gave back almost half the value in a single quarter. Is the real upside already cashed in, or does the recent slide reset the entry math?
Most Popular Narrative: 53% Undervalued
Argan’s most followed narrative pegs fair value at $800, well above the last close of $377.95, and anchors that gap on a very specific growth, margin and discount rate profile.
A consolidated backlog of more than US$2.9b, with about 77% in natural gas projects and a mix of renewable and industrial work, provides multi year project coverage. This can underpin revenue stability and support EBITDA and net income consistency as projects convert from backlog to sales.
See why 3 investors see Argan as 53% undervalued.
Result: Fair Value of $800 (UNDERVALUED)
Still, the bullish Argan story relies heavily on a gas weighted backlog and clean execution on a handful of large projects, where policy shifts or cost overruns could quickly bite.
Find out about the key risks to this Argan narrative.
Another View on Argan’s Valuation
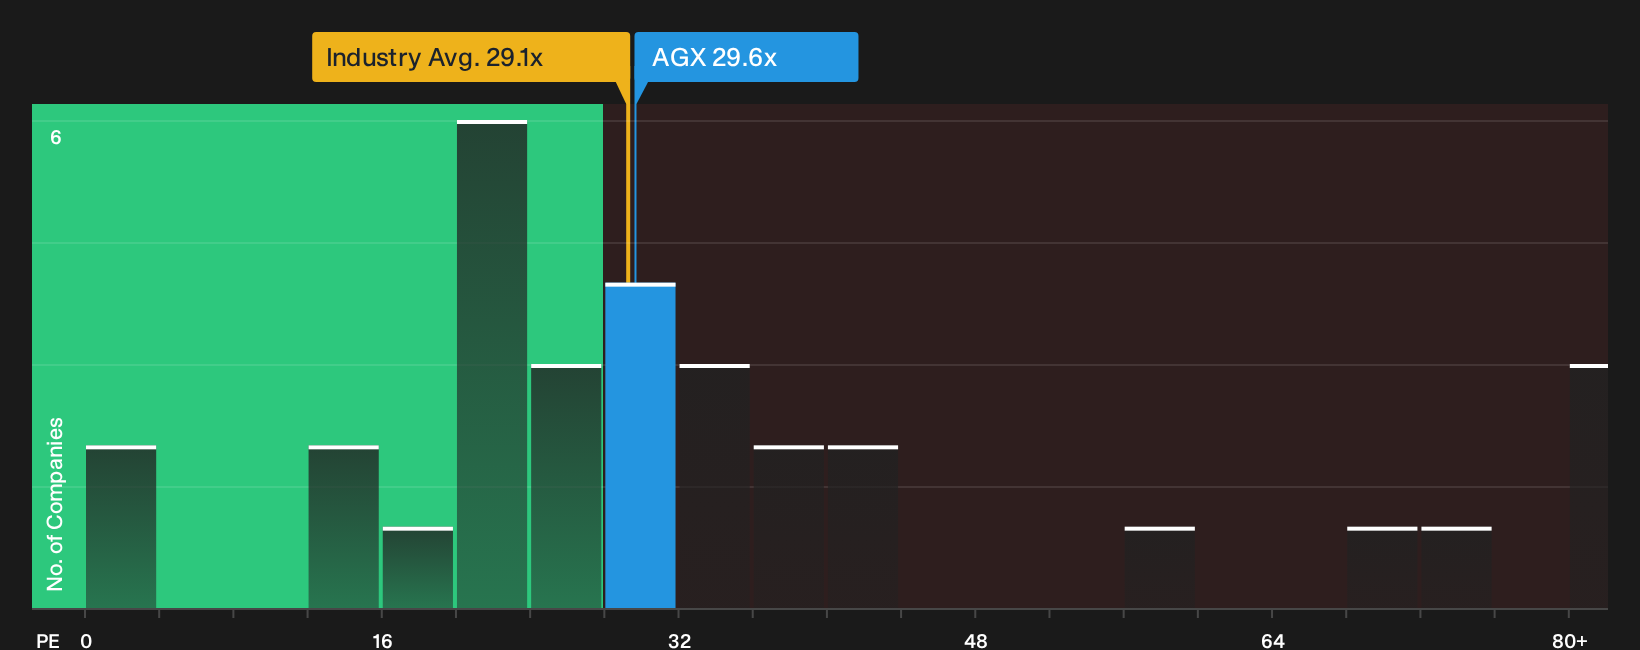
That $800 fair value hinges on growth and margin assumptions. The multiples check paints a cooler picture. Argan trades on a P/E of 29.6x, slightly above the US Construction industry at 29.1x and above its own fair ratio of 26.3x, which points to valuation risk rather than a clear bargain.
The question for you is simple. Does paying more than both sector and fair ratio levels feel justified by Argan’s earnings profile, or is patience the better move while the market decides where that P/E should settle?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Argan story so far feels split between enthusiasm and caution, treat that as your cue to move fast and test the numbers yourself. The most balanced starting point is to weigh both the upside potential and the downside flags side by side using 2 key rewards and 2 important warning signs.
Ready for more ideas beyond Argan?
Argan gives you one angle, but the real edge comes from lining it up against other opportunities that fit clear, disciplined criteria using the Simply Wall Street Screener.
- Target stronger risk control by scanning for companies with resilient finances and muted volatility through the 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by zeroing in on financially sound businesses that screen as priced below estimated worth via the 32 high quality undervalued stocks.
- Lock in potential income ideas by reviewing companies that pair higher yields with balance sheet strength inside the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com