
Alstom (ENXTPA:ALO), What Is Behind The Fresh Attention?
Alstom (ENXTPA:ALO) just secured two sizable rail contracts, including 35 additional Avelia Stream Nordic X80 trains for Västtrafik and new driverless metro units for Riyadh, which together expand its long-term order book.
Alstom’s latest contracts land against a mixed share performance, with the 1-day and 7-day share price returns of 0.64% and 0.84% offering a small bounce, while the 30-day share price return is down 8.59% and the year-to-date share price return is down 41.79%, pointing to momentum that has yet to fully recover despite ongoing commercial wins.
Scan how Alstom’s latest contract wins compare with other rail and infrastructure players by reviewing a curated set of 40 power grid technology and infrastructure stocks in a single view.
Alstom’s contract pipeline keeps filling while the share price is still working off a heavy year to date slide. Is more of the opportunity now in the backlog, or still in the valuation that investors assign to it?
Most Popular Narrative: 29% Undervalued
On the most followed view of Alstom, a fair value of €21.10 compares with the recent €14.96 close. This puts a sizable gap between the narrative valuation and where the market currently prices the shares.
Alstom's strategy of focusing on high-quality, margin-accretive orders, especially in Services and Signaling, is expected to improve revenue growth and increase future gross margins. The company is conducting industrial restructuring to optimize its manufacturing setup, which aims to enhance operational efficiency and potentially improve net margins and earnings.
See why 28 investors see Alstom as 29% undervalued.
Result: Fair Value of €21.10 (UNDERVALUED)
Still, if supply chain setbacks deepen or low margin legacy contracts linger longer than expected, the bullish Alstom narrative could quickly lose credibility.
Find out about the key risks to this Alstom narrative.
Another View: What Alstom’s P/E Is Telling Investors
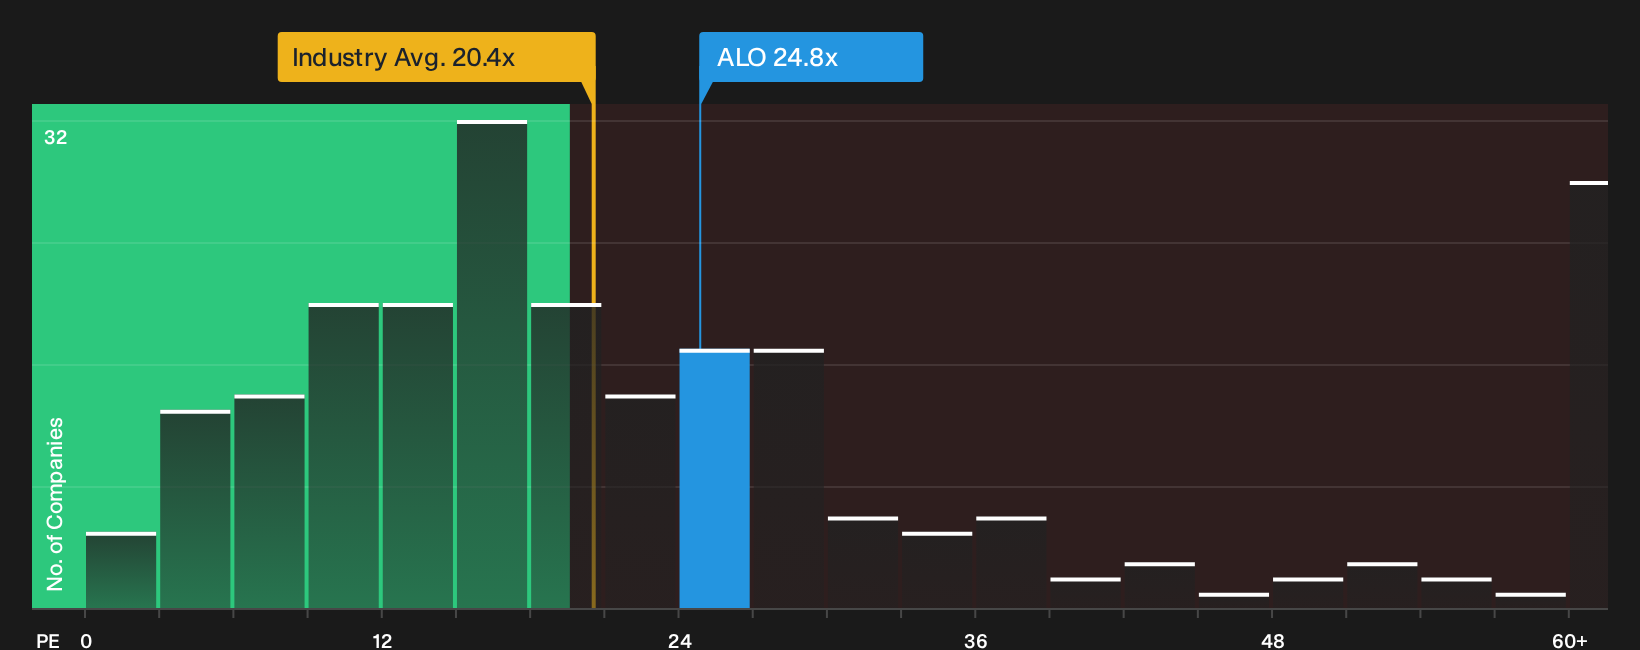
The analyst narrative frames Alstom as 29% undervalued, yet the current P/E of 24.8x is higher than the European Machinery group at 20.4x and its peer average of 15.9x. The fair ratio sits at 32.2x. The question for investors is whether the main risk lies in expectations drifting down or the market moving toward that fair ratio over time.
Before leaning too heavily on any single ratio, it can help to see how the numbers compare with a fuller valuation breakdown, including peers, sector and the fair ratio trend over time: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Alstom’s valuation and risk profile demand fresh eyes. Act while sentiment is still split, and weigh both sides of the story with 2 key rewards and 1 important warning sign
Looking for more Alstom sized investment ideas?
If Alstom’s story has you thinking bigger about your portfolio, do not stop here. Broader opportunity often sits with the ideas you have not checked yet.
- Prioritize resilience and sleep easier at night by scanning a curated set of 225 resilient stocks with low risk scores that aim to keep volatility in check.
- Target quality at a discount and widen your opportunity set with a focused batch of 560 high quality undiscovered gems before they attract wider attention.
- Strengthen your foundation by reviewing a list of solid balance sheet and fundamentals (205 results) so you are not caught off guard when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com