
TransUnion (TRU) Stock May Be Undervalued Following CFO Transition News
TransUnion shares have retreated sharply over the past few years, which puts fresh focus on whether the current US$61.12 price still lines up with what the company earns. With the business also planning a Chief Financial Officer succession, the question is how well the stock price reflects the earnings power behind the credit data and analytics franchise.
- The share price has fallen 44.9% over the past 5 years, which puts pressure on the case that the current valuation can be explained by its earnings profile.
- The planned CFO transition through early 2027, alongside a reaffirmed medium term financial outlook, may support investor confidence in how TransUnion expects to convert its data assets into future profit and cash generation.
- Your read on TransUnion is one view; the desks covering it have another. See what analysts think TransUnion's shares could be worth.
The stock's next move may depend on whether the current market price is well supported by TransUnion's earnings when set against the Fair Ratio benchmark.
If you are weighing whether TransUnion's current earnings justify its recent share price slide, it can help to cross check against a focused list of 32 high quality undervalued stocks.
Is TransUnion Still Cheap on Earnings?
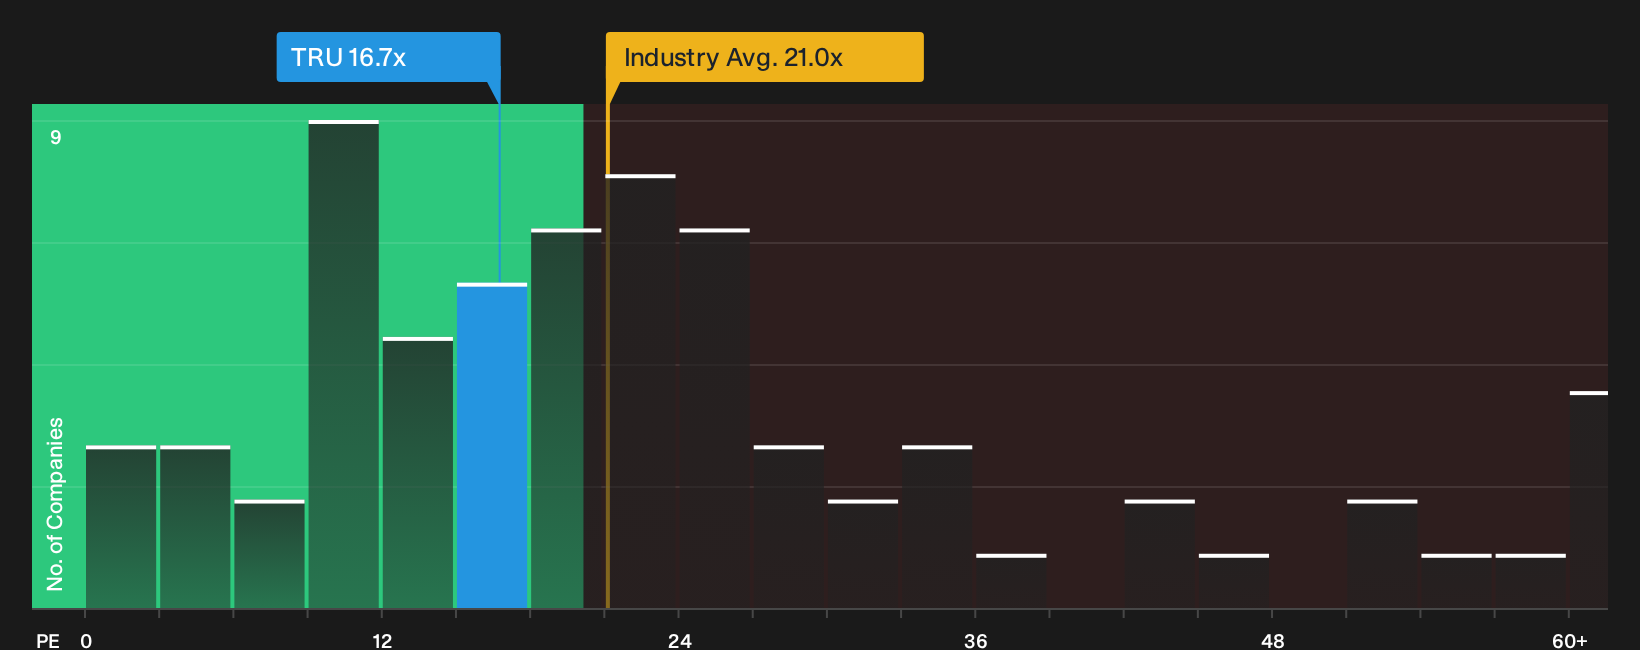
The P/E ratio works well for TransUnion because profit is a central lens for how credit data businesses are usually judged. At the current share price, TransUnion trades on a P/E of about 15.9x. That sits below the Professional Services industry average of roughly 21.0x and also below the peer group on about 26.6x. Based on the Fair Ratio benchmark, which reflects what investors might typically pay for a business with TransUnion's mix of growth profile, margins, size and risk, the current P/E screens on the low side.
Because management recently reaffirmed the 2026 financial outlook alongside the CFO transition, this gap suggests the stock price is not fully aligned with how similar earnings streams are valued elsewhere on the market. For a shareholder, the key question is whether the earnings that support that 15.9x multiple are durable enough to close part of that valuation gap over time, or whether the discount is a sign that investors want a larger margin of safety. Explore the numbers behind TransUnion's P/E valuation.
The TransUnion Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for TransUnion pick up where the P/E puzzle leaves off. They spell out what would need to be true about TransUnion's future growth, profitability and earnings profile for the current market value to look either too low or too high. Each one also treats fair value as a thesis about the business that can be revisited over time rather than a single static number.
One of the top community narratives on TransUnion: 21% undervalued
"The company highlights large long term opportunities from AI, TruIQ Analytics, Trusted Call Solutions and broader use of proprietary, regulated data…"
Discover why this Narrative puts TransUnion at 21% undervalued.
TransUnion's value still hinges on who is steering it
Price multiples tell you what the market is willing to pay, but they do not tell you whether the people in charge are rewarded for the same outcomes you care about as a shareholder. See who runs TransUnion and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com