
e.l.f. Beauty (ELF), Why Is It Back In The Spotlight?
Elf Beauty (ELF) drew fresh investor attention after third party sales data showed e.l.f. Cosmetics outpacing the broader beauty category, with unit volumes and the Naturium skin care label posting especially strong year on year gains.
Against that strong third party sales backdrop, e.l.f. Beauty’s share price has cooled in the short term, with a 30 day share price return down 7.41%, even as the 90 day share price return is up 32.13% and the 5 year total shareholder return is 238.60%. This suggests that longer term momentum has been strong, while more recent trading reflects a reset in expectations rather than a collapse in confidence.
Scan other beauty and personal care stocks with strong brand momentum using our hand picked 17 high quality undiscovered gems for ideas beyond e.l.f. Beauty.
e.l.f. Beauty appears to be operating effectively based on recent sales data, while the share price has cooled after a significant multi-year run. Is that reset enough to make the valuation appear attractive today?
Most Popular Narrative: 1% Undervalued
On the latest narrative workup, e.l.f. Beauty carries a fair value estimate of $101.75 against a last close of $100.97. This frames the recent pullback as a marginal discount rather than a sharp disconnect.
The expansion into new international markets and rapid growth in existing ones (e.g., 30% international net sales growth, top rankings in new geographies, global Sephora rollout) provides significant runway for future revenue growth and increased diversification, which is likely under-appreciated by the market.
See why 106 investors see e.l.f. Beauty as 1% undervalued.
Result: Fair Value of $101.75 (UNDERVALUED)
Still, the e.l.f. Beauty story depends on key assumptions holding steady, including tariff exposure tied to heavy China sourcing and execution risk around higher marketing and Rhode integration spending.
Find out about the key risks to this e.l.f. Beauty narrative.
Another View on e.l.f. Beauty’s Valuation
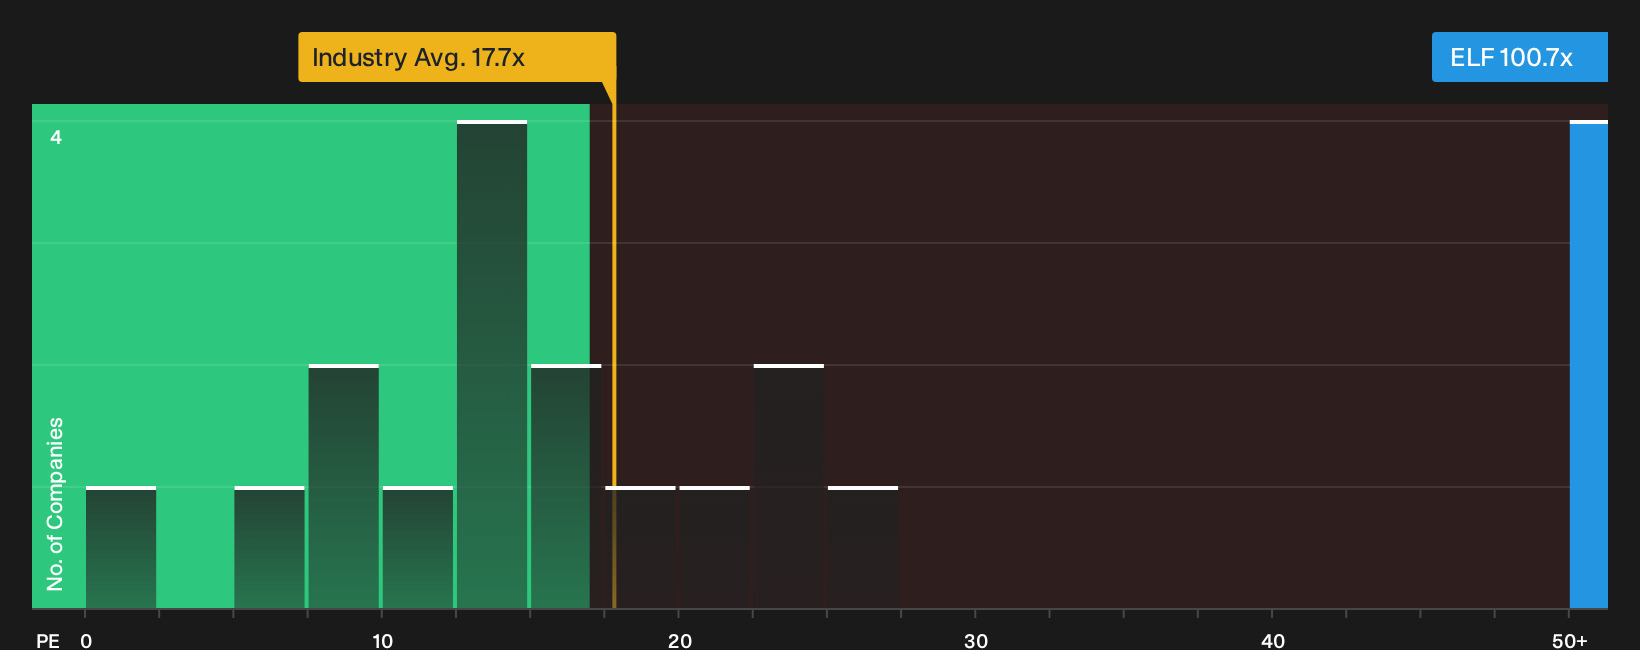
The initial narrative leans on a fair value of $101.75 per share, which frames e.l.f. Beauty as only 1% undervalued. Using simple pricing ratios gives a very different angle. The stock currently trades on a P/E of about 100x, while the fair ratio is 25.1x and the peer group and global Personal Products industry sit near 22.1x and 17.7x. That wide gap points to meaningful valuation risk if expectations cool or growth stumbles, so the real question is how confident you are that current enthusiasm can hold up over time.
For a closer look at how this pricing stacks up against earnings and peers, including how far the current multiple sits above the fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on e.l.f. Beauty’s price and narrative can create a lot of noise, so act quickly, review the underlying data, and weigh both the upside and the red flags through 2 key rewards and 3 important warning signs.
Looking for more e.l.f. Beauty investment ideas?
You have a clear picture of e.l.f. Beauty, so now widen the lens. Use focused stock lists to research new opportunities.
- Explore mispriced businesses by scanning our hand picked 31 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
- Prioritize managing risk by starting with 32 resilient stocks with low risk scores that score well on resilience.
- Find financially healthy operators by filtering through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com