
How Workforce Shortage Forecast At Covista Has Changed Its Investment Story
- Covista released its Covista Healthcare Workforce Index, which now projects that the U.S. healthcare workforce shortage could nearly double by 2040 without coordinated action across health systems, policymakers and educators.
- The index suggests that pairing targeted workforce investment with new care delivery models could address about 92% of the projected staffing gap, which directly connects Covista’s healthcare education programs to one of the sector’s largest capacity challenges.
- We will now look at how Covista's investment narrative could be influenced by its workforce index spotlight on long term healthcare shortages.
Covista Investment Narrative Recap
To own Covista, you need to believe its healthcare focused education model can keep attracting working adults and new graduates even as student preferences, regulation and funding shift. The big swing factor in the near term remains enrollment execution at Chamberlain and Walden, especially as digital programs compete more directly on price and flexibility.
The largest immediate risk is that flat or soft nursing enrollment and higher student support costs weigh on margins and cash generation, which would limit how aggressively Covista can expand capacity or repurchase shares. The recent workforce index and credit amendment do not materially change that near term operational equation.
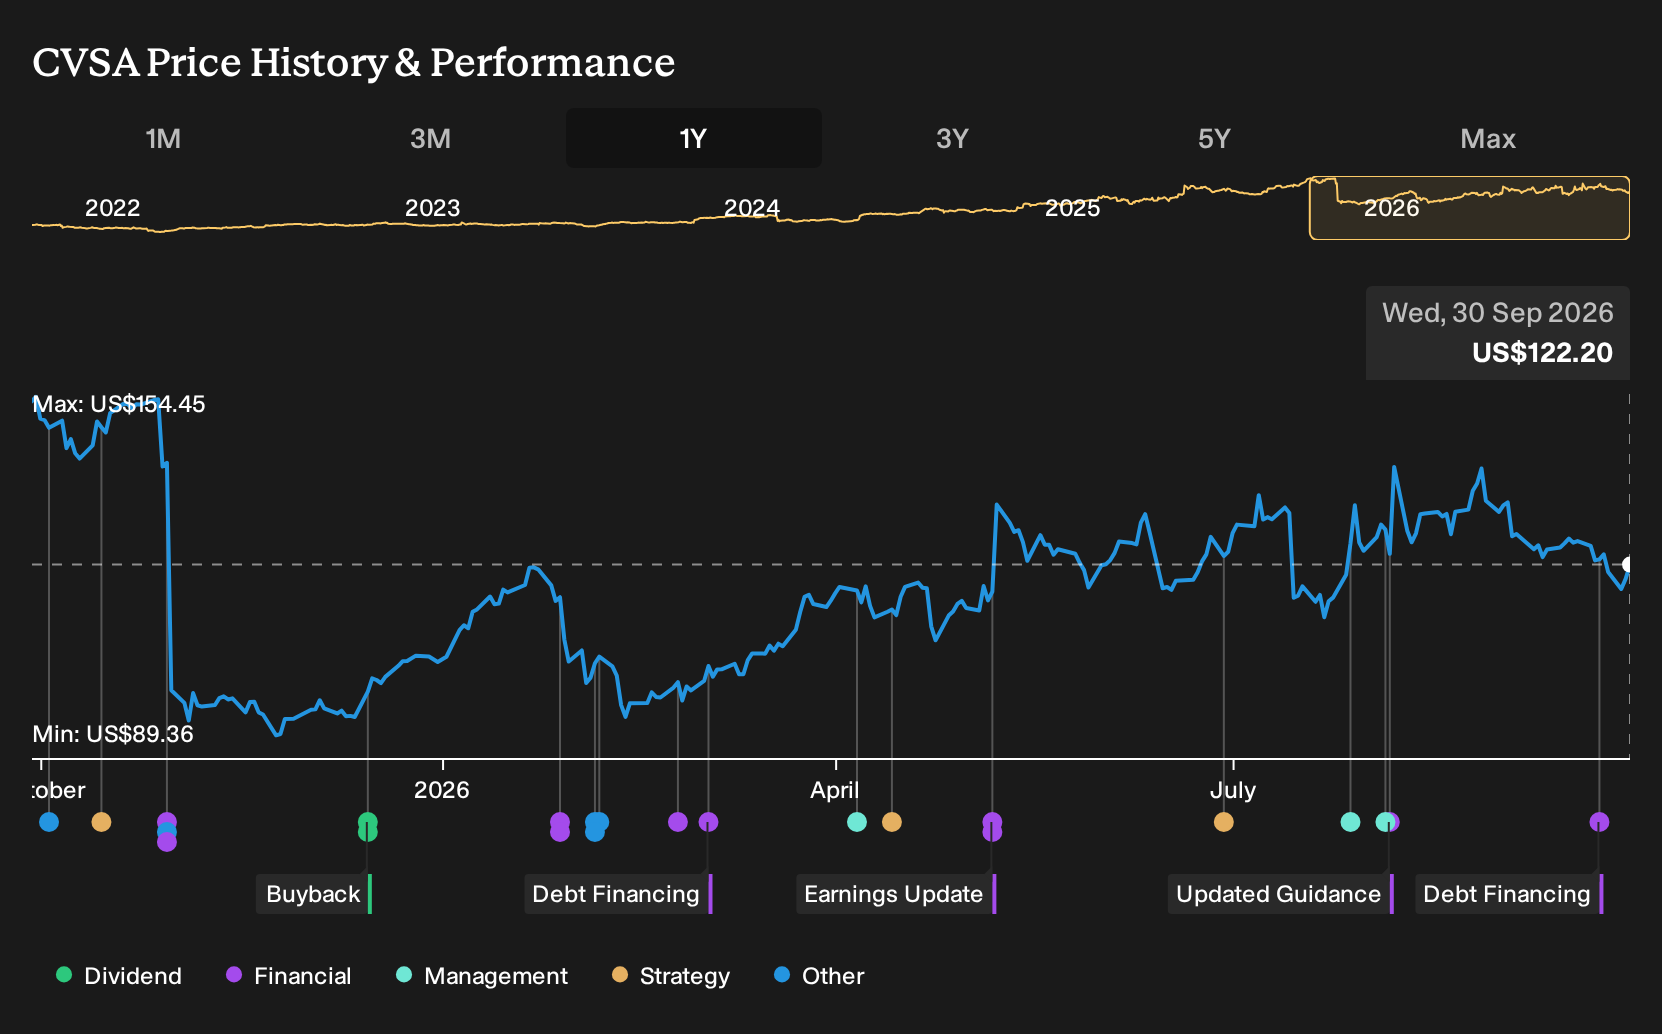
Amendment No. 6, which reprices US$510 million of term loans, looks most relevant for short term catalysts because it trims interest expense and slightly improves financial flexibility. Covista now pays Term SOFR plus a 2.00% margin on those loans instead of 2.25%, with base rate loans stepping down to a 1.00% margin from 1.25%.
This lower coupon could modestly support earnings quality and cash flow, which matters if enrollment growth at Chamberlain or Walden remains uneven or if regulatory shifts around student lending pressure volumes. There is a 1.00% premium on certain repricing transactions within six months, so investors should watch future refinancing moves as part of the funding risk picture.
Covista's narrative projects US$2.4b revenue and US$362.8m earnings by 2029. This assumes 7.4% yearly revenue growth and an earnings increase of about US$95m from US$267.4m today.
Discover why Covista's fair value points to a 31% potential upside from its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Covista leans heavily on competitive pressure rather than the workforce shortage tailwind you see in the new index. The most cautious analysts were already penciling in US$2.4b revenue and US$353.2m earnings by 2029, but on a lower 14.2x P/E. That more muted setup could shift again as the workforce data and debt repricing sink in.
Explore 2 other Covista fair value estimates, including one that suggests it could be worth just $159.50!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your Covista research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Covista. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Covista's overall financial health at a glance.
Looking for more investment ideas beyond Covista?
If the Covista story has sharpened your thinking around education and healthcare exposure, it can be useful to compare it with other businesses that share some of the same strengths or risk controls. The Simply Wall St Screener helps you filter companies by financial resilience, income potential and under the radar growth so you can build a watchlist that really fits your approach.
- If capital preservation sits high on your list, you can start with companies that combine steady fundamentals with lower risk profiles by checking out 32 resilient stocks with low risk scores.
- For investors who want income to do more of the heavy lifting, you can scan for payout opportunities with solid financial backing through the 6 dividend fortresses.
- If you prefer to hunt for mispriced quality, you can focus on resilient balance sheets and strong cash generation by reviewing the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com