
How Split Analyst Views Will Impact Applied Digital Stock (APLD) Investors
- Applied Digital has secured long-term AI and high-performance computing data center leases, including a 15-year, US$7b agreement with CoreWeave, while carrying a contracted backlog cited at around US$31b to US$36b.
- The business is pursuing rapid, capital-intensive expansion into AI-focused campuses funded with significant debt, even as analyst earnings estimates have recently been revised downward and views on valuation diverge.
- We will now look at how Applied Digital's investment narrative is affected by conflicting coverage and rate-driven concerns around funding.
Balance Applied Digital's high-conviction AI story with a broader watchlist by reviewing hand-picked 89 AI infrastructure stocks that could also benefit from long-term compute demand.
Applied Digital Investment Narrative Recap
To own Applied Digital, you need to trust that its AI and high performance computing build out can turn long dated leases and a US$31b to US$36b backlog into durable cash flows before its balance sheet gets stretched. Recent coverage shifts and the Zacks Rank downgrade mainly sharpen that focus rather than change the core thesis.
The near term swing factor is execution on new AI campuses, utilization, and funding at acceptable borrowing costs. The biggest risk is that heavy debt, less than one year of cash runway, and concentrated hyperscaler contracts collide with any delay, causing pressure on liquidity and forcing tougher financing choices.
The most relevant recent development is management’s push toward a US$1b net operating income run rate tied to those long term AI and HPC leases, including the US$7b CoreWeave deal and roughly 1.41 gigawatts of contracted capacity. That concrete target gives you a yardstick for whether the backlog is turning into actual economics.
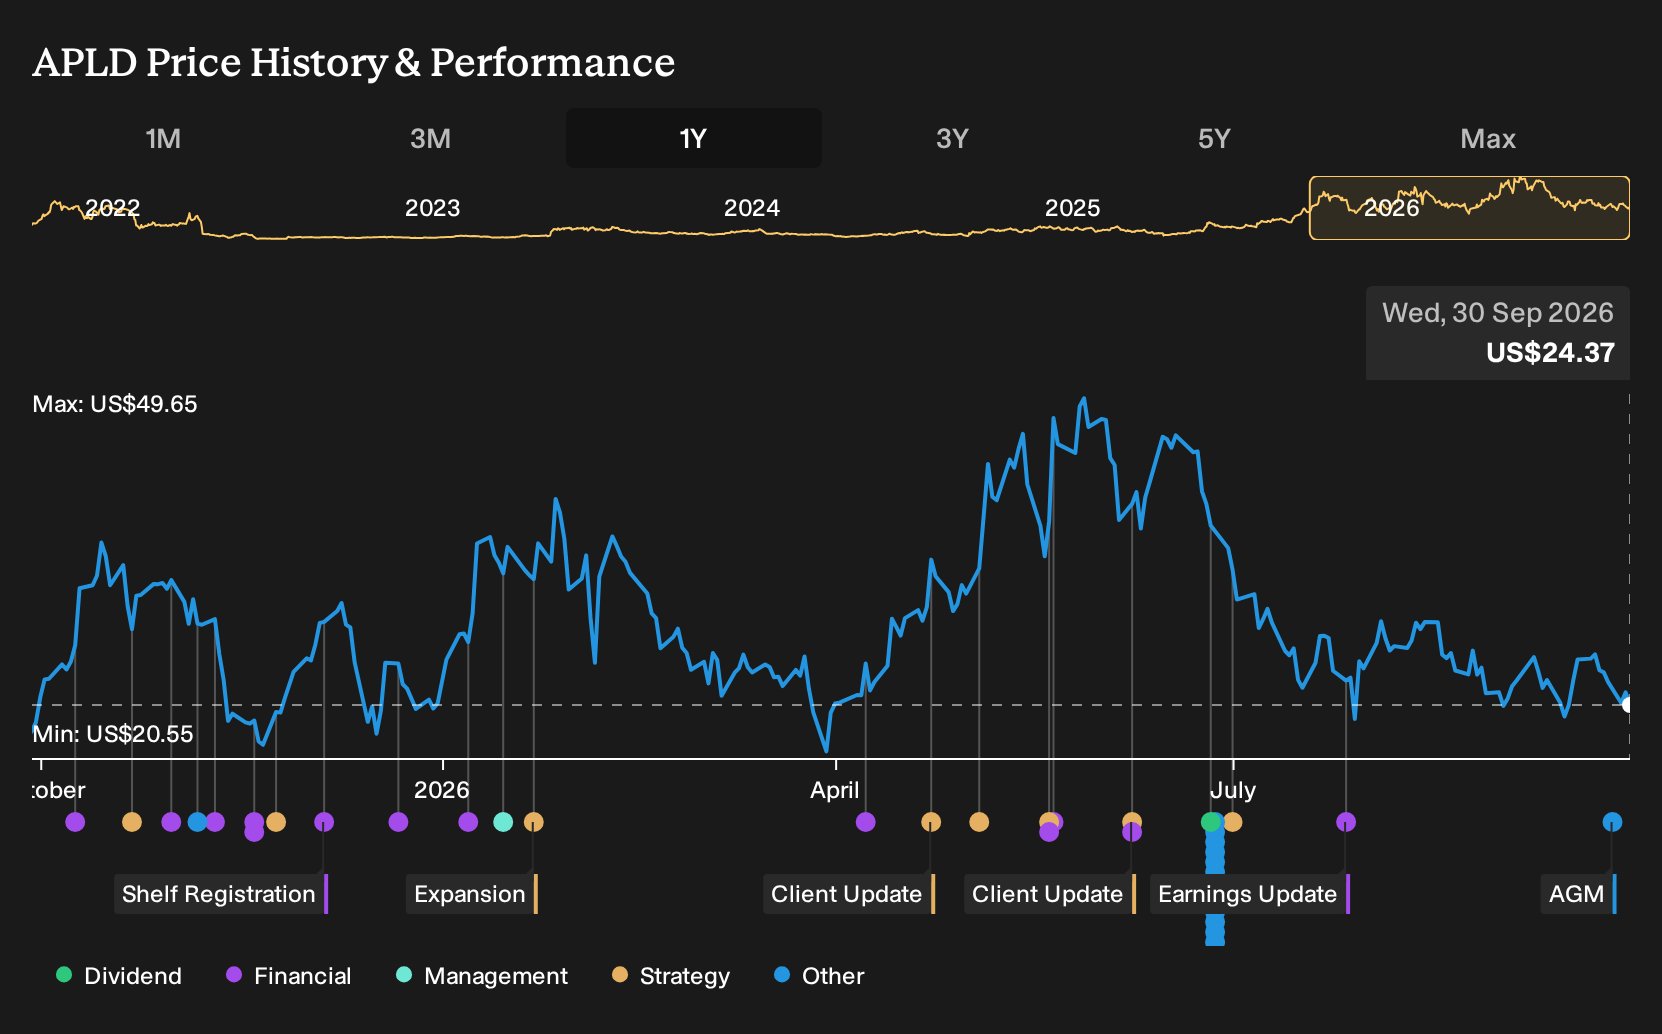
Against that, you have a stock already trading on a high P/S multiple compared with peers, downward earnings estimate revisions, and fresh Strong Sell style signals. The next few quarters of reported results and conference calls matter less for headline EPS and more for traction on build timelines, power availability, customer diversification, and funding terms.
Applied Digital's analyst narrative points to forecast revenue of US$3.0b and consensus earnings of US$295.0m by 2029. This implies revenue growth of 70.2% per year and an earnings swing of about US$544.2m from a current loss of US$249.2m to that 2029 profit figure.
Uncover why Applied Digital's fair value indicates a 180% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Applied Digital leans hard into the upside of customer concentration. The most optimistic analysts argue that if the CoreWeave style contracts hold, the business could reach about US$3.1b in revenue and US$1.8b in earnings by 2029. That is far more upbeat than consensus, and both sets of forecasts may shift after this week’s news.
Explore 7 other Applied Digital fair value estimates, including one that suggests as much as 335% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Applied Digital research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Applied Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Applied Digital's overall financial health at a glance.
Looking For More Ideas Beyond Applied Digital?
If Applied Digital has sharpened your view on AI infrastructure, it can help to compare it with a wider watchlist built around clear financial traits and different risk profiles.
The Simply Wall St Screener can surface other opportunities that match your style. These options give you a fast way to scan the market by quality, valuation and balance sheet strength.
- Prefer to keep downside in check and focus on sturdier businesses with measured risk profiles? Start with a 32 resilient stocks with low risk scores that score well on resilience and stability.
- If the priority is finding companies that look priced conservatively relative to their fundamentals, filter for value opportunities through a curated set of 32 high quality undervalued stocks with stronger cash generation and balance sheets.
- For investors who want solid financial footing before anything else, build a shortlist from a list of solid balance sheet and fundamentals (25 results) that pair cleaner leverage profiles with underlying fundamentals you can scrutinize further.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com