
Prestige Consumer Healthcare (PBH) Could Be 31% Undervalued As 2027 Goals Take Shape
Prestige Consumer Healthcare (PBH) has set new medium term objectives for fiscal 2027, focusing on its over the counter brands, the use of free cash flow, and current Clear Eyes supply constraints.
Prestige Consumer Healthcare shares have been under pressure, with the 30 day share price return down 11.41% and the year to date share price return down 25.07%. The 1 year total shareholder return has declined 27.60%, which hints that investors are weighing the new 2027 goals and Clear Eyes supply issues against the firm’s cash generation and capital allocation plans.
Scan other consumer-focused stocks using our curated list of 32 high quality undervalued stocks that combine resilient cash generation with balance sheets investors are watching closely right now.
Prestige Consumer Healthcare now trades well below both analyst targets and one fair value estimate range. With that kind of gap after a sharp pullback, where does a measured view of value really land?
Most Popular Narrative: 31% Undervalued
Prestige Consumer Healthcare closed at $45.87, while the most followed narrative anchors fair value at $66.80, creating a sizable valuation gap that hinges on how investors view brand strength, cash generation, and supply recovery.
Prestige's supply chain investments, specifically the acquisition of Pillar5 and onboarding new suppliers for Clear Eyes, are set to resolve current supply constraints, supporting normalization and eventual growth of revenues, especially in the high-demand eye care segment, from the second half of fiscal '26 and into fiscal '27.
See why 1 investors see Prestige Consumer Healthcare as 31% undervalued.
Result: Fair Value of $66.80 (UNDERVALUED)
Still, the Prestige Consumer Healthcare story hinges on the recovery of Clear Eyes supply and the heavy reliance on a handful of mature over the counter brands.
Find out about the key risks to this Prestige Consumer Healthcare narrative.
Another View: Prestige Consumer Healthcare Through The P/E Lens
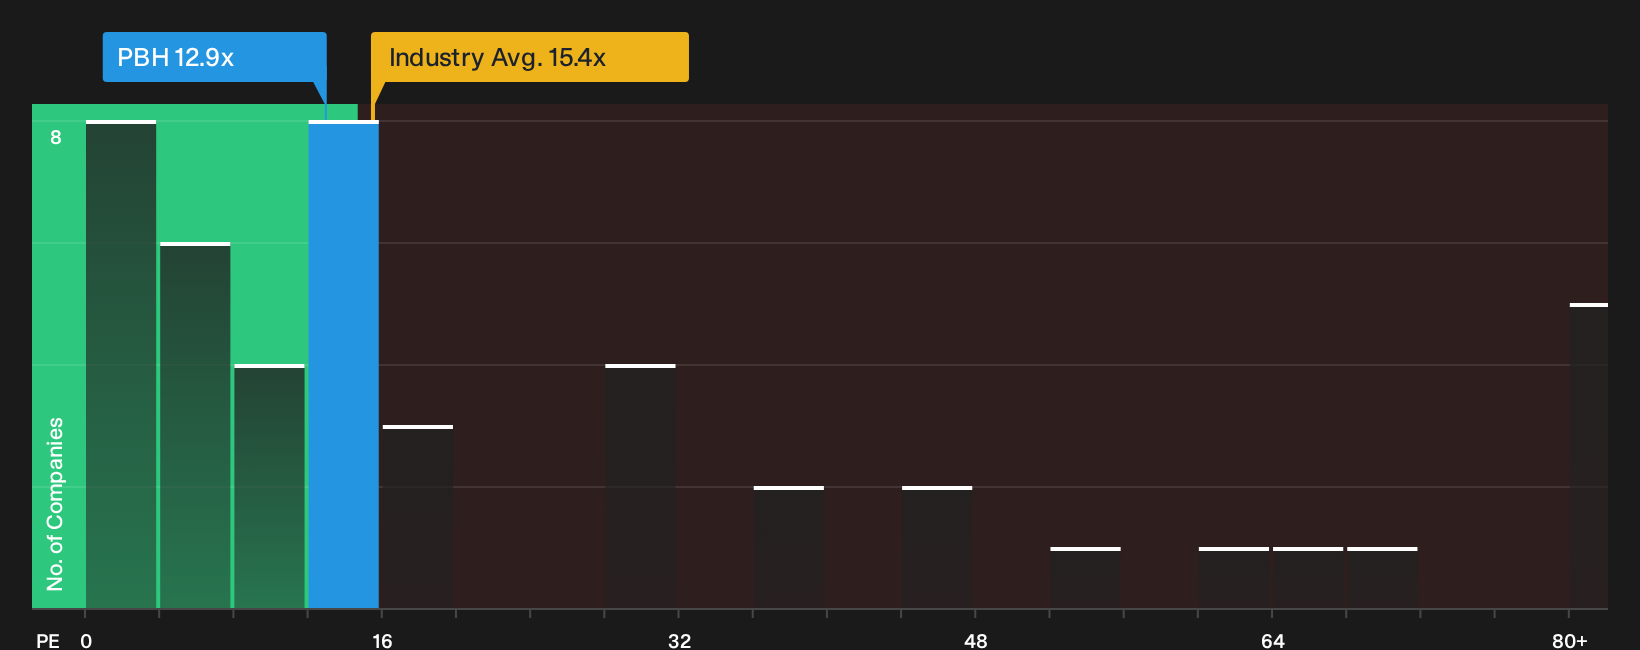
Prestige Consumer Healthcare might look cheap on that $66.80 fair value, yet the P/E picture is less forgiving. The stock trades at 12.9x earnings, which is higher than the 11.6x peer average, even though the fair ratio points closer to 15.4x. That gap suggests some room for upside if sentiment normalizes, but also real risk if peers stay cheaper for longer. Which side of that tradeoff feels more realistic to you?
To see how this earnings multiple stacks up against sector norms and where the fair ratio could pull the valuation over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Prestige Consumer Healthcare story feels split between pressure and potential, it may be worth moving quickly to test the numbers yourself before sentiment shifts again. For a balanced snapshot of what is worrying and what is encouraging investors right now, start with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Prestige Consumer Healthcare?
If Prestige Consumer Healthcare has your attention, do not stop there. Broader context from other opportunities can sharpen your judgment and keep your watchlist ahead of the crowd.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that many investors use as a starting universe.
- Surface potential mispricings before they are widely talked about by reviewing the 32 high quality undervalued stocks highlighted by our valuation filters.
- Lock in income-focused ideas built around ongoing cash returns by checking the 6 dividend fortresses currently standing out for yield hunters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com