
PVH (PVH) Stock Still Looks Reasonable Following Its 29% Five Year Fall
PVH Corp. has had a mixed share price journey in recent years, and the question for investors now is whether the current US$75.74 level is reasonable when judged against its sales. With the stock showing both gains and setbacks over different time frames, the link between what the business sells and what the market is willing to pay deserves a closer look.
- Over the past 5 years the PVH share price has fallen 29.5%, which puts the focus squarely on whether the underlying sales base can still support the current valuation.
- Recent headlines around PVH highlight a large goodwill impairment alongside reaffirmed targets and planned share buybacks, a mix that can influence how investors weigh the durability of revenue against accounting charges and capital returns.
- Your read on PVH is one view; the desks covering it have another. See what analysts think PVH's shares could be worth.
The issue now is whether PVH's present share price is justified by the scale and quality of its sales.
If you are weighing whether PVH is a bargain or a trap based on its sales and recent goodwill hit, it can help to compare it with 32 high quality undervalued stocks.
Is PVH Still Cheap on Sales?
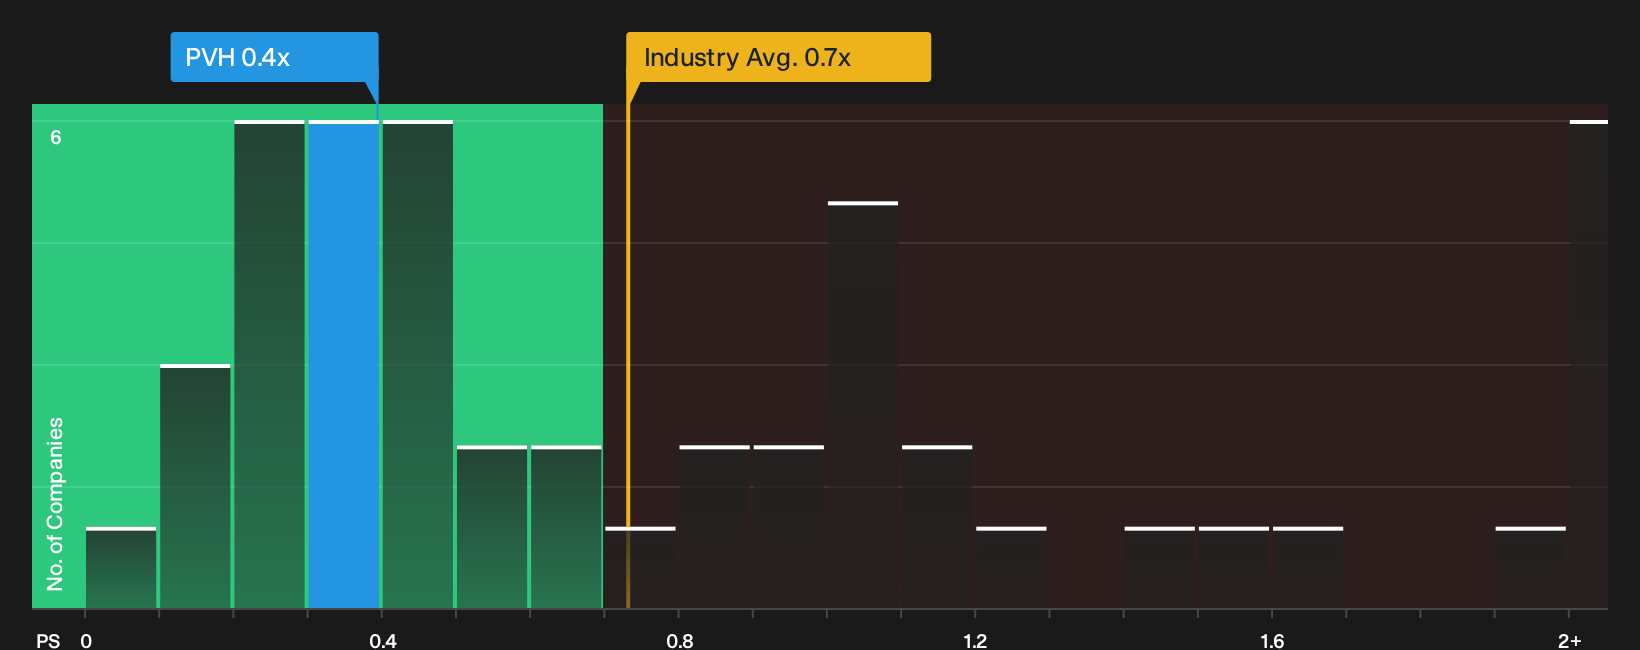
The P/S ratio fits PVH because this is a branded apparel business where revenue scale and pricing power tend to matter more than headline earnings in any single year. On this lens, the stock trades on a P/S of 0.4x, which is below the Luxury industry average of about 0.7x and also under the peer group level around 1.0x. That gap means investors are currently paying less for each dollar of PVH sales than is typical for similar companies.
The fair-value model, which adjusts the P/S benchmark for PVH's own margins, growth profile, size and risks, points to a higher multiple than the one the market is assigning. Despite the recent goodwill impairment and the focus it brought onto the income statement, the current P/S still prices PVH at a discount relative to what this framework suggests. To see how large that gap is in concrete terms, you can compare the present ratio against the fair multiple estimate. Explore the numbers behind PVH's P/S valuation.
The PVH Narrative: What Would Justify Today's Price?
PVH Narratives on Simply Wall St pick up where the valuation puzzle leaves off and spell out what kind of future growth, margins and earnings would need to show up for the current share price to look meaningfully high or low. Rather than relying on a single multiple or model outcome, each one lays out the key assumptions behind its view of fair value, so you can compare those expectations with PVH's actual results as they are reported.
Community views on PVH split between those who see meaningful upside from internal improvement efforts and those who think regional and tariff pressures already cap the story.
Bull case: 41% undervalued
"PVH is moving aggressively to digitally transform its supply chain and retail operations, including AI-driven inventory optimization and personalized e-commerce experiences..."
Discover why this Narrative puts PVH at 41% undervalued.
Bear case: 8% overvalued
"The large pre tax goodwill impairment of US$439 million tied to geopolitical and macroeconomic assumptions, together with EMEA revenue expected to decline mid single digits..."
Explore why this Narrative puts PVH at 8% overvalued.
PVH's value still depends on who is steering it
Price tags and revenue lines only tell part of the story for PVH, because the people setting priorities and how they are rewarded can tilt the risk and reward profile in powerful ways. See who runs PVH and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com