
Clinical Trial Data Reveal Could Be A Game Changer For Zai Lab (ZLAB)
- Zai Lab announced that global Phase 1b/1c data for its first-in-class DLL3-targeting ADC zocilurtatug pelitecan in first-line extensive-stage small cell lung cancer will be presented at the ESMO Congress 2026 session on October 26 in Madrid.
- The poster covers zoci in combination with atezolizumab, with or without carboplatin, in a hard-to-treat lung cancer setting. This aligns with Zai Lab’s efforts to build a differentiated oncology pipeline beyond in-licensed assets.
- The next step is to consider how this upcoming ESMO readout for Zai Lab’s DLL3 ADC may influence the broader investment narrative.
Scan how Zai Lab’s DLL3 ADC fits alongside other potential breakout oncology stories by comparing it with our curated list of 35 healthcare AI stocks.
Zai Lab Investment Narrative Recap
For Zai Lab, the investment case still hinges on whether its broad oncology and immunology portfolio can convert strong forecast revenue growth into a sustainable path toward profitability. The upcoming ESMO data for zoci matters mainly as a signal of how well the company can source and develop differentiated assets that support that story.
Over the near term, the most important catalyst remains clinical and regulatory execution across multiple programs while keeping spending in check for a business that is still loss making. The biggest risk is that heavy R&D and in licensing costs persist without enough high quality approvals and reimbursement decisions to narrow those losses.
The zoci readout links closely to the wider push that analysts highlight around multiple product launches and label expansions over the next 12 to 18 months. Positive safety and activity data in ES SCLC would help frame Zai Lab as more than a pure in licensing platform and could support the idea of a deeper oncology franchise over time.
That said, zoci is only one piece of the puzzle next to assets like VYVGART, bemarituzumab, KarXT, TIVDAK and Tumor Treating Fields, which analysts already point to as key drivers of a larger addressable market. For you, the question is whether the ESMO update meaningfully changes confidence in Zai Lab’s ability to execute on that multi asset catalyst stack while managing ongoing losses.
Zai Lab's current analyst framework points to forecast revenue of US$832.0 million and earnings of US$157.9 million by 2029, built on an assumed 22.4% yearly revenue growth rate and an earnings swing of roughly US$336.0 million from an earnings loss of US$178.1 million today.
Uncover why Zai Lab's fair value indicates a 28% potential upside to its current price, a gap that could narrow quickly if sentiment resets.
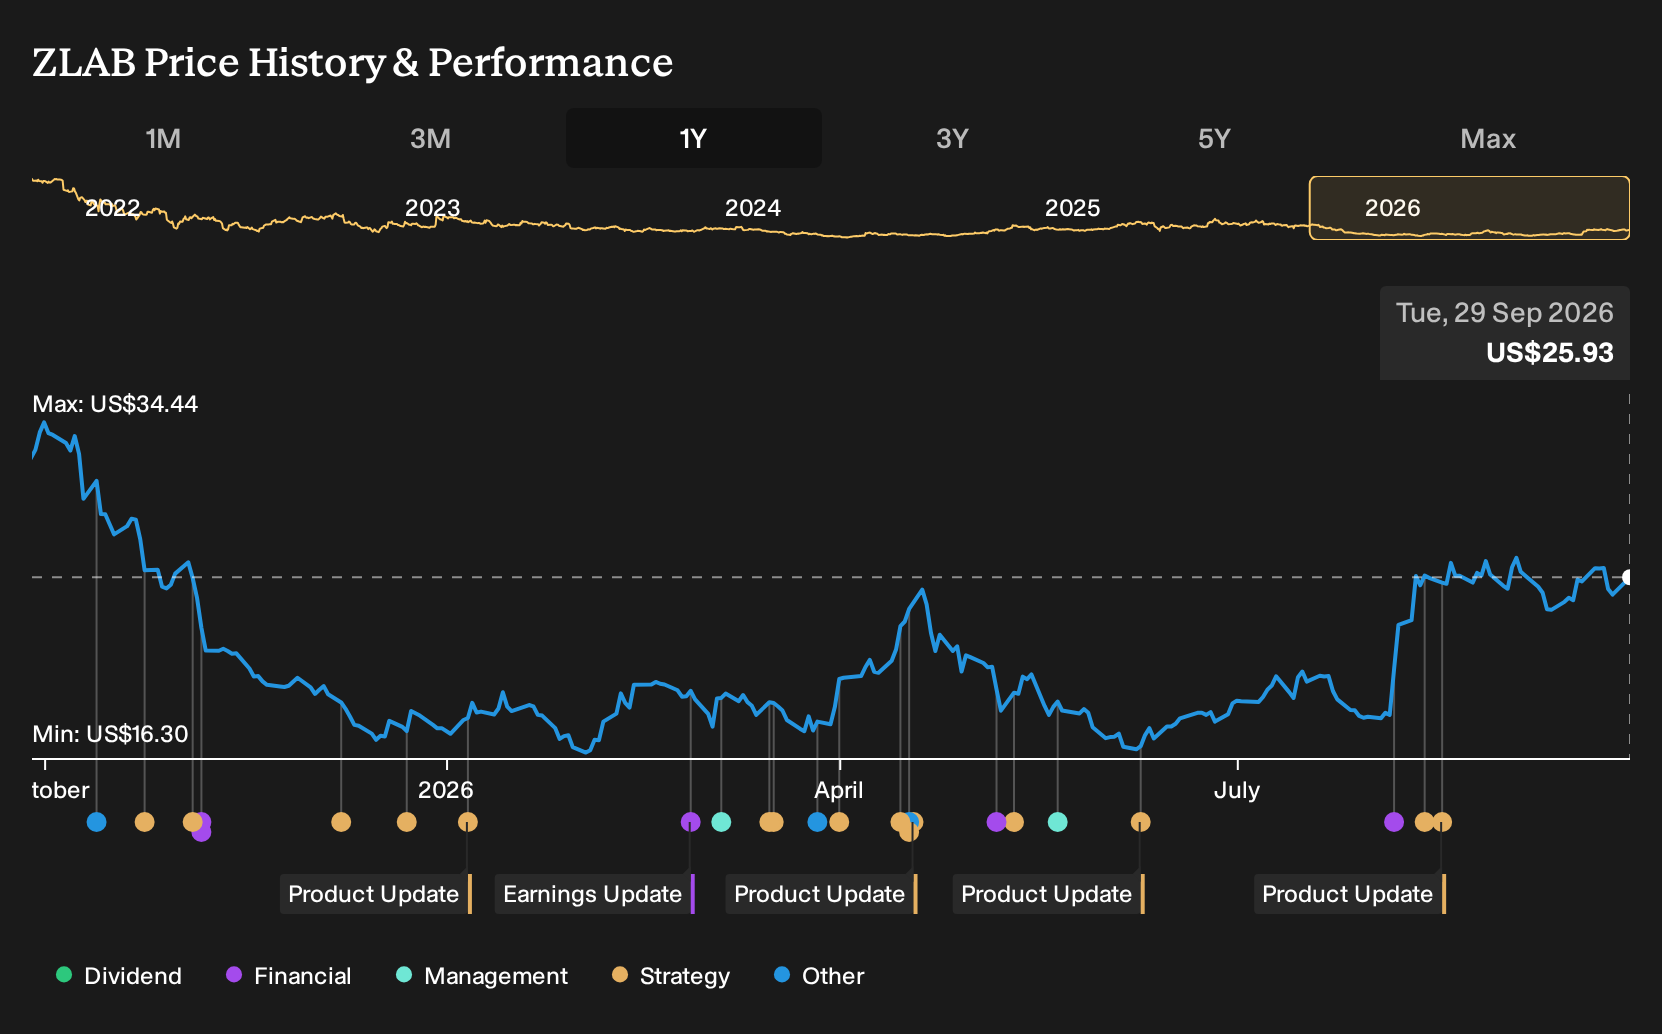
Exploring Other Perspectives
Some of the lowest Zai Lab forecasts lean hard into the risk that China pricing and reimbursement squeeze earnings. Those analysts were pencilling in revenue of about US$702.1 million and earnings of US$127.9 million by 2029, well below consensus. You can treat this ESMO zoci reveal as a fresh test of which story wins.
Explore 3 other Zai Lab fair value estimates, including one that suggests as much as 6% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Zai Lab research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zai Lab. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zai Lab's overall financial health at a glance.
Looking For More Investment Ideas Beyond Zai Lab?
Once you have a view on Zai Lab, it can help to widen the lens and compare it with other opportunities that fit different risk and return profiles using the Simply Wall St Screener.
- If you are hunting for mispriced opportunities with quality traits, start with a curated set of 32 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into their prices.
- If resilience matters more than headline growth, focus on companies in the 32 resilient stocks with low risk scores that carry lower risk scores and may better suit a steadier approach to building wealth.
- If you want sturdier financial foundations, concentrate your research on the list of solid balance sheet and fundamentals (25 results), which highlights businesses with stronger balance sheets and more robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com