
What Is Drawing Attention To Agnico Eagle Mines (AEM)?
Agnico Eagle Mines (NYSE:AEM) has come under pressure after an earnings miss, an analyst downgrade to Hold, and softer gold prices linked to expectations of a Federal Reserve rate hike.
Recent selling has been sharp, with a 7 day share price return of down 8.71% and a 30 day move of down 9.90%. However, Agnico Eagle Mines still shows a 90 day share price return of 20.01% and a 1 year total shareholder return of 11.22%, suggesting momentum has cooled in the short term after a stronger run earlier in the year.
Spot 36 elite gold producer stocks that may handle cost pressures and shifting gold prices differently to Agnico Eagle Mines while staying focused on producers with meaningful scale.Agnico Eagle Mines now sits between a recent pullback and a longer run of gains. This raises the question of whether the current dip is enough to justify stepping in today, or whether patience could offer a more attractive entry once valuation work is completed.
Most Popular Narrative: 99.9% Undervalued
Agnico Eagle Mines last closed at $185.83 while the most followed narrative assigns a fair value near $123,914, which frames the current pullback as small next to the valuation gap implied by that story.
With gold hovering near record highs, a massive structural shift is quietly playing out in the Abitibi greenstone belt that the broader market has completely failed to price in.
If you are holding Agnico Eagle ($AEM) or hunting for the ultimate asymmetric micro-cap play, you need to look at the cold engineering reality currently facing the Canadian Malartic complex, and the tiny junior right next door that holds the key to fixing it: Renforth Resources (CSE: RFR | OTCQB: RFHRF).
See why 30 investors see Agnico Eagle Mines as 100% undervalued.
According to lenny67, the narrative hinges on a potential multi year production gap at the Canadian Malartic complex and how mill capacity, regional geology, and nearby deposits could reshape the economics around Agnico Eagle Mines rather than focusing only on short term share price moves.
The same narrative applies an 8.30% discount rate to future cash flows and still reaches a fair value far above the current $185.83 share price. This reflects an extremely optimistic view of how earnings power, assets, and optionality could compound over time.
For readers comparing that story to other views on Agnico Eagle Mines, it is worth treating the 99.9% undervaluation figure as one scenario among many, and stress testing the assumptions behind production, project timing, and commodity pricing against your own expectations and risk tolerance.
Result: Fair Value of $123,914 (UNDERVALUED)
Still, investors need to factor in clear risks, including the possibility that engineering outcomes, permitting timelines, or gold price moves diverge sharply from the narrative’s assumptions.
Find out about the key risks to this Agnico Eagle Mines narrative.
Another View on Agnico Eagle Mines Valuation
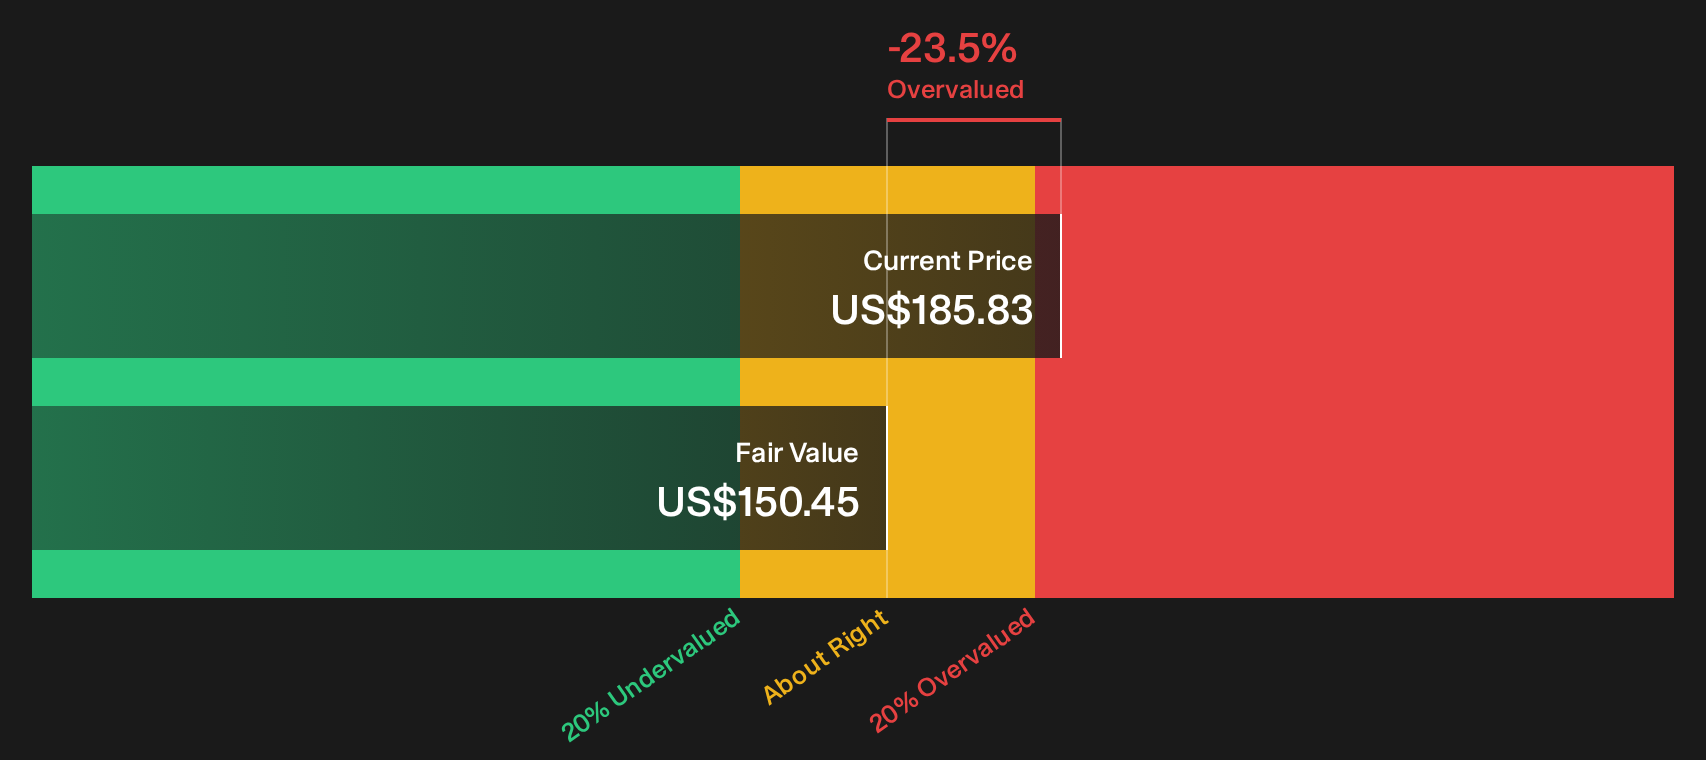
The narrative fair value of $123,914 for Agnico Eagle Mines clashes with Simply Wall St's cash flow work. On the SWS DCF model, AEM at $185.83 trades above an estimated future cash flow value of $150.45, which flags the shares as overvalued rather than deeply discounted. Which story feels closer to reality for you.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Agnico Eagle Mines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals for Agnico Eagle Mines can feel confusing, so move quickly from headline takes to your own work by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Agnico Eagle Mines
If Agnico Eagle Mines leaves you uncertain about the next move, broaden your watchlist now so you do not miss other opportunities quietly setting up.
- Target growth at a discount by reviewing our hand picked pool of quality stocks that look mispriced through the Simply Wall St lens via 32 high quality undervalued stocks.
- Strengthen your income stream by scanning companies with resilient cash flows and generous payouts through the focused yield list at 6 dividend fortresses.
- Prioritise resilience and sleep at night by studying stocks with lower risk scores and sturdier profiles using the curated universe in 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com