
Diageo (LSE:DGE) Unveiled An India Focused Blue Label, Is The Stock Still Cheap?
Diageo (LSE:DGE) has drawn fresh attention after Johnnie Walker introduced a limited Johnnie Walker Blue Label Indian Festive Blend, a new India focused expression that links premium Scotch with contemporary local design.
For shareholders, the picture is mixed. Diageo’s 1-day share price return of 0.87% and 90-day share price gain of 5.63% suggest improving short term momentum; however, the 1-year total shareholder return has declined 5.8% and the 5-year total shareholder return is down 47.55%, pointing to longer running pressure on the investment case.
Spot 4 high quality undiscovered gems that, like Diageo’s Johnnie Walker launch, rely on strong brands and compelling product stories yet still sit under most investors’ radar.After a 5.6% gain over 90 days, but with a 5-year total return still down more than 47%, is Diageo’s recent bounce the start of a rerating, or just the afterglow of past expectations already baked into the price?
Most Popular Narrative: 19% Undervalued
On the numbers, Diageo’s last close at £16.24 sits below a widely followed fair value estimate of about £20.07. This frames the current debate around whether the stock already reflects the mixed operational picture or not.
Diageo is intensifying its focus on premiumization and category expansion (notably in tequila and ready-to-drink beverages) to capture rising consumer affluence and elevated brand preferences in both emerging and developed markets, supporting future revenue growth and gross margin expansion.
The company is executing a multiyear overhaul to deepen locally tailored, occasion-led marketing and distribution strategies across key regions (Europe, Asia-Pacific, and Africa), positioning itself to leverage demographic shifts such as urbanization and a growing legal drinking-age population, which are expected to drive volume and sales momentum over the long term.
See why 144 investors see Diageo as 19% undervalued.
Result: Fair Value of £20.07 (UNDERVALUED)
Still, Diageo’s story can deteriorate quickly if alcohol moderation trends deepen or if execution stumbles in volatile regions such as Africa or Latin America.
Find out about the key risks to this Diageo narrative.
Another View on Diageo’s Valuation
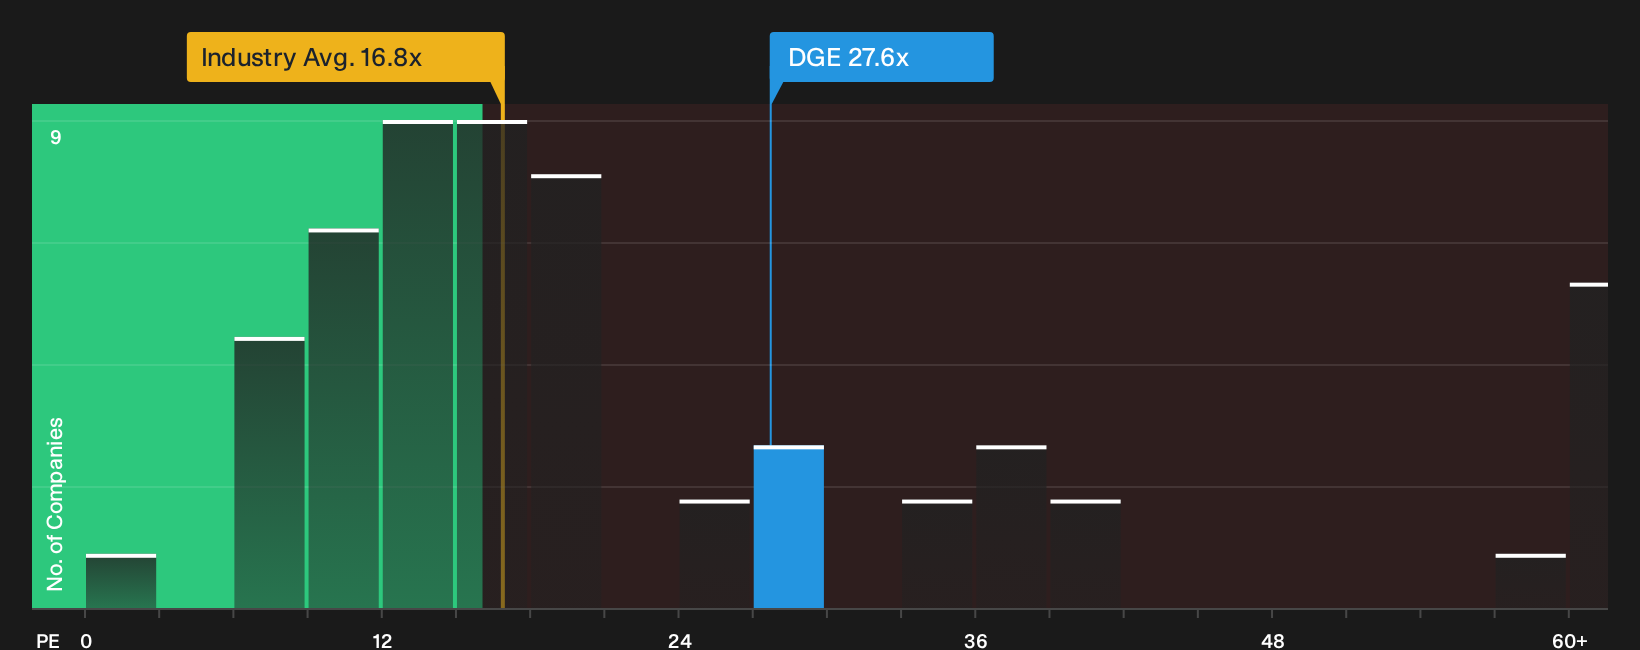
A second lens uses Diageo’s P/E of 27.6x. That looks rich beside the European Beverage sector at 16.8x, yet it is roughly in line with a fair ratio of 27.7x and still below a 41.8x peer average. So is this pricing a risk premium or a quality premium in disguise?
For a closer look at how the earnings multiple stacks up against peers and the fair ratio, our valuation breakdown lays out the numbers in full, including key sensitivities, in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of pressure and potential around Diageo leaves you uncertain, consider acting promptly and evaluating both sides for yourself by checking 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Diageo?
Do not stop with Diageo. Broaden your watchlist with a few focused screeners that surface different types of opportunities before the crowd fully catches on.
- Target potential mispricings by scanning 8 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their underlying business strength.
- Strengthen your income stream by reviewing 1 dividend fortresses that aim to pair higher yields with balance sheet resilience and consistent cash generation.
- Sleep easier at night by concentrating on 4 resilient stocks with low risk scores where financial health and lower risk scores take priority over short term excitement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com