
What Sterling Infrastructure (STRL)'s Earnings Outlook Means For Shareholders
- Sterling Infrastructure is preparing to report earnings that analysts expect to be significantly higher year over year, with forecasts citing an EPS estimate of $6.07 and revenue of $1.16b, largely tied to mission critical E-Infrastructure work such as data centers and semiconductor campuses.
- The business now leans heavily on E-Infrastructure projects, where strong free cash flow margins and a growing backlog in AI data centers and large construction programs highlight how core operations are increasingly anchored to long lead, technically complex developments.
- We will look at how Sterling Infrastructure's investment narrative is shaped by rising expectations tied to its E-Infrastructure earnings engine.
What Is Sterling Infrastructure's Investment Narrative?
Sterling Infrastructure is essentially a bet that mission critical E-Infrastructure continues to require specialized contractors capable of handling complex, capital heavy projects such as AI data centers and semiconductor campuses. The business already sources most of its revenue from this line of work, with earnings and cash flow supported by long duration contracts and a sizeable US$2.44b contribution from E-Infrastructure Solutions within a US$3.44b top line.
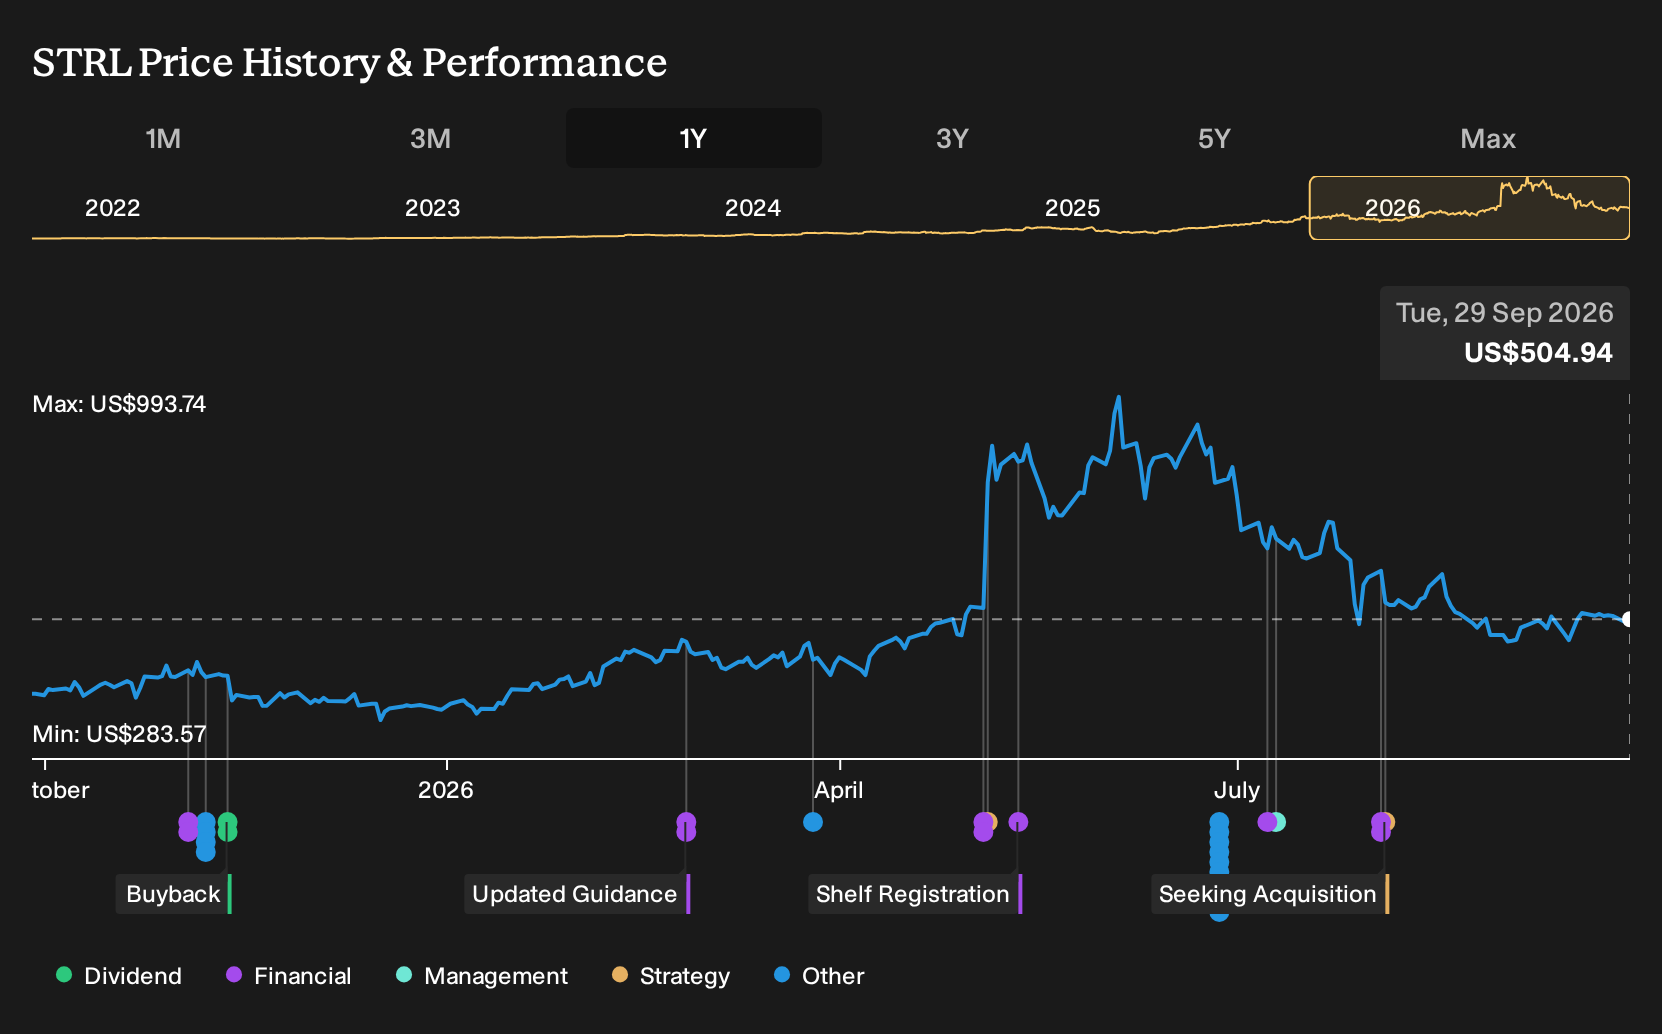
Recent share moves indicate that volatility is significant. The stock climbed 6.0% over the past month but declined over 90 days, even as analysts forecast materially higher EPS and revenue in the upcoming report. That recent dip does not change the near term catalyst list in a major way. Execution on the backlog, maintaining pricing on technically demanding projects, and managing higher risk external funding remain the key variables.
That said, alongside the strong E-Infrastructure story sits an underappreciated pressure point around ...
There's only one way to know the right time to buy, sell or hold Sterling Infrastructure. Head to Simply Wall St's company report for the latest analysis of Sterling Infrastructure's Fair Value.
Exploring Other Perspectives
Some of the most optimistic analysts frame Sterling Infrastructure around a single catalyst: they see E‑Infrastructure demand for AI data centers and chip fabs as the swing factor. Before this news, the bullish group was modeling revenue of about US$4.5b and earnings of roughly US$1.0b by 2029, so your take on these assumptions may change after fresh information lands.
Explore 3 other Sterling Infrastructure fair value estimates, including one that suggests as much as 98% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sterling Infrastructure research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sterling Infrastructure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sterling Infrastructure's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sterling Infrastructure?
Sterling Infrastructure might be front of mind after this earnings setup, but your best edge comes from comparing it with a wider group of potential opportunities using a structured stock screener.
If you want to broaden your watchlist and pressure test your thesis on risk, quality, and income, the Simply Wall St Screener can help you quickly surface stocks that fit very different roles in a portfolio.
- For investors who care most about valuation support and business quality, scan through our curated 32 high quality undervalued stocks that combine strong fundamentals with pricing that may appeal to value focused buyers.
- If balance sheet resilience is your first filter, build a shortlist from the list of solid balance sheet and fundamentals (25 results) to find companies with financial structures that may better withstand tougher conditions.
- Those looking for opportunities that the wider market may not be paying attention to can review the 17 high quality undiscovered gems and see which quieter stories deserve a closer look next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com