
United Laboratories Stock and Its China Diabetes Drug Filing Means For Shareholders
- United Laboratories International Holdings reported that China’s National Medical Products Administration accepted the marketing registration application for its self-developed IDegLira biosimilar, a once daily fixed dose insulin degludec and liraglutide combination for type 2 diabetes.
- This filing positions United Laboratories as the first domestic producer in China to seek approval for an IDegLira biosimilar. It could reshape the company’s diabetes portfolio by tying long acting glucose control to a simplified dosing schedule.
- We will now look at how United Laboratories' investment narrative could shift as it pursues first mover IDegLira biosimilar status.
Scan beyond United Laboratories International Holdings and compare this first mover IDegLira story with other drug makers pushing for defensible moats in diabetes and chronic care through our curated 133 healthcare AI stocks
What Is United Laboratories International Holdings' Investment Narrative?
To own United Laboratories International Holdings, you need to believe in a China centered pharma platform that can keep turning a broad mix of bulk medicine, intermediates, and finished drugs into durable cash flow while managing capital heavy manufacturing. The IDegLira biosimilar filing fits that thesis. It shows the group is willing to invest in more complex, higher value chronic care products rather than rely only on commoditised antibiotics and older therapies.
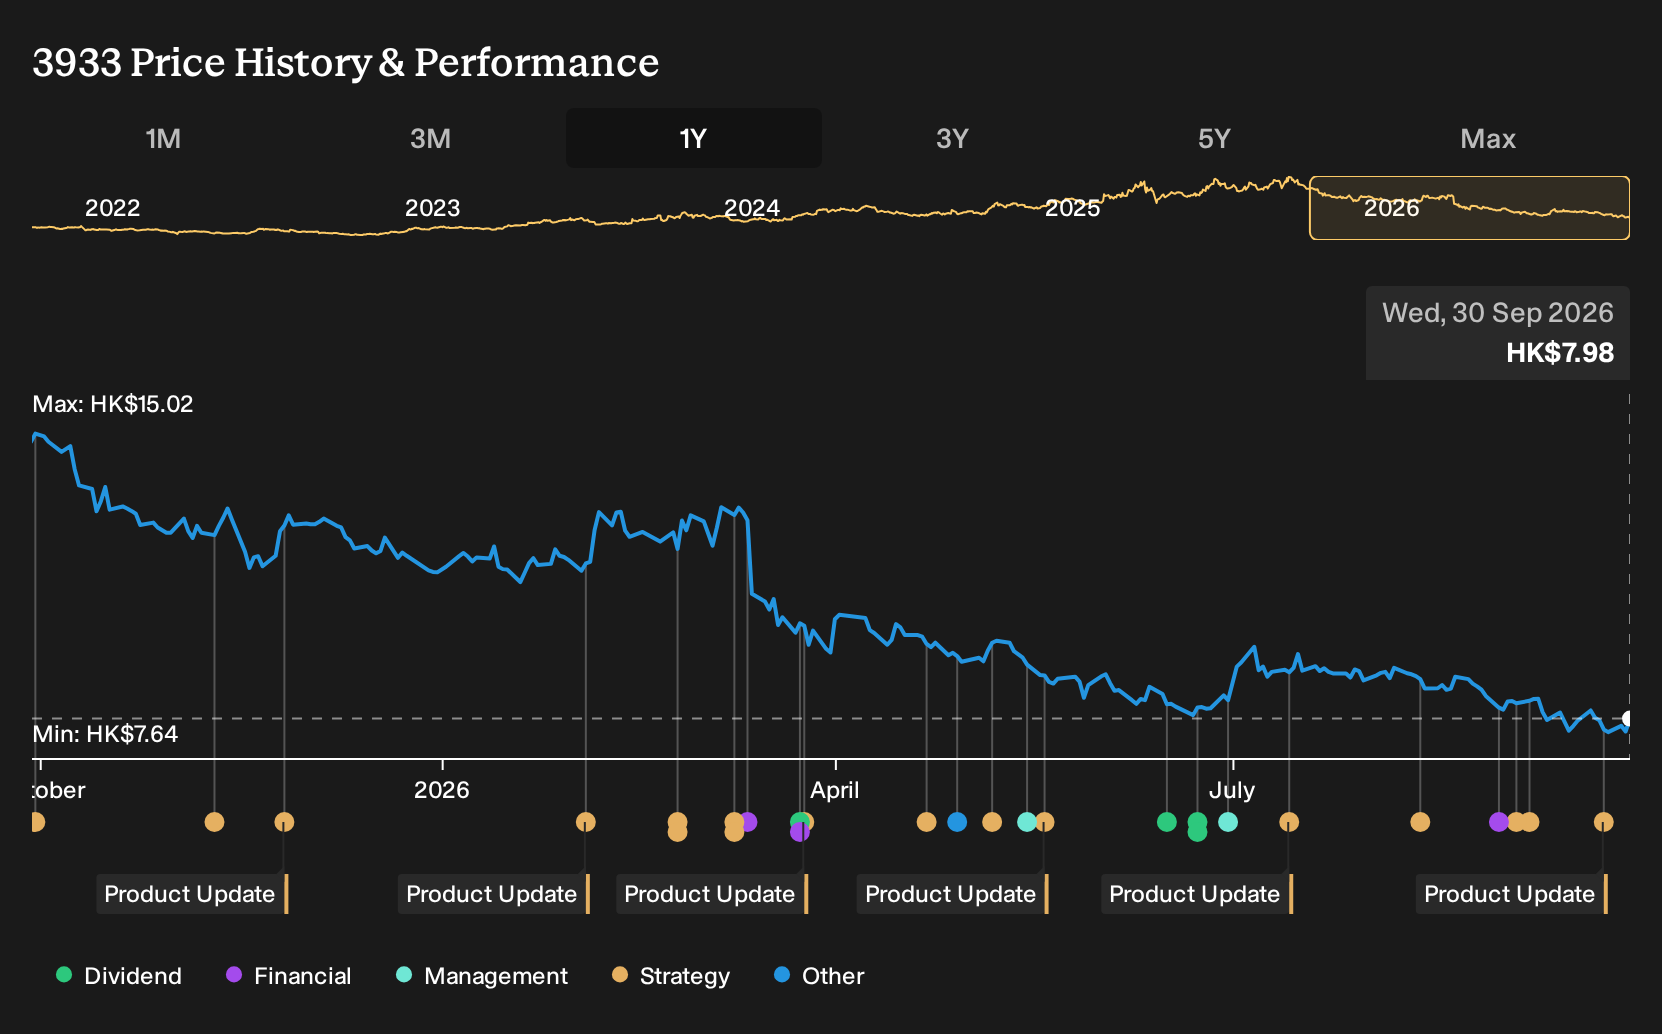
In the near term, the key swing factors remain very operational. Execution on R&D, regulatory timelines, and the ability to defend pricing in a crowded diabetes arena matter more than storytelling. Profitability is a pressure point, with net profit margins at 4.5% compared with 21.7% last year. The stock has fallen 45% over the past year despite a P/E of 24.8x, which sits below the peer average of 30.1x but above both the sector and one fair value estimate. The IDegLira news therefore arrives into a market that is already skeptical about how efficiently United Laboratories can turn its pipeline into returns.
That said, there is one awkward tension in the United Laboratories story that only really shows up once you focus on ...
There's only one way to know the right time to buy, sell or hold United Laboratories International Holdings. Head to Simply Wall St's company report for the latest analysis of United Laboratories International Holdings's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span an extreme range, from about HK$0.000044 to HK$12.88, which shows how far views on United Laboratories International Holdings can stretch. Since neither figure reflects the recent IDegLira filing, treat this as a starting point and explore more community perspectives before forming a view.
Explore another United Laboratories International Holdings fair value estimate, including one that suggests as much as 100% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your United Laboratories International Holdings research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for United Laboratories International Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Laboratories International Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Laboratories International Holdings?
If the United Laboratories International Holdings story has sharpened your view on risk, reward, and pricing power in healthcare, it can help to widen the lens and compare it with other businesses that share some of those traits but sit in very different positions on quality, income potential, or balance sheet strength.
- For investors who want lower drama and steadier fundamentals, consider scanning a 226 resilient stocks with low risk scores that may better fit a more conservative approach.
- If value is the priority and you are hunting for mispriced opportunities, line up United Laboratories International Holdings against a 189 high quality undervalued stocks to see where the risk and return trade offs look more attractive.
- Income focused portfolios can benefit from comparing United Laboratories' profile with a 156 dividend fortresses that screens for stronger yield support and consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com