
Brookfield Infrastructure Partners (BIP) Stock Looks Above Fair Value Despite Its 56% Run
Brookfield Infrastructure Partners has delivered a 3 year gain that many utilities investors will notice, yet the recent pullback raises a simple question for you as a holder or potential buyer. Is today’s share price properly grounded in the earnings that support this partnership.
- The unit price has risen 55.7% over the past 3 years, which puts real pressure on the question of how much of Brookfield Infrastructure Partners’ earnings power is already baked into the valuation.
- The partnership leans on long term, often contracted assets that can shape how steadily earnings flow, which matters for how much investors are willing to pay for each dollar of profit.
- There is a second opinion on Brookfield Infrastructure Partners worth weighing. See what analysts think Brookfield Infrastructure Partners's shares could be worth.
The issue now is whether Brookfield Infrastructure Partners’ current price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings question that hangs over Brookfield Infrastructure Partners against a wider field, scan companies in the 32 high quality undervalued stocks
.Has Brookfield Infrastructure Partners Run Too Far on Earnings?
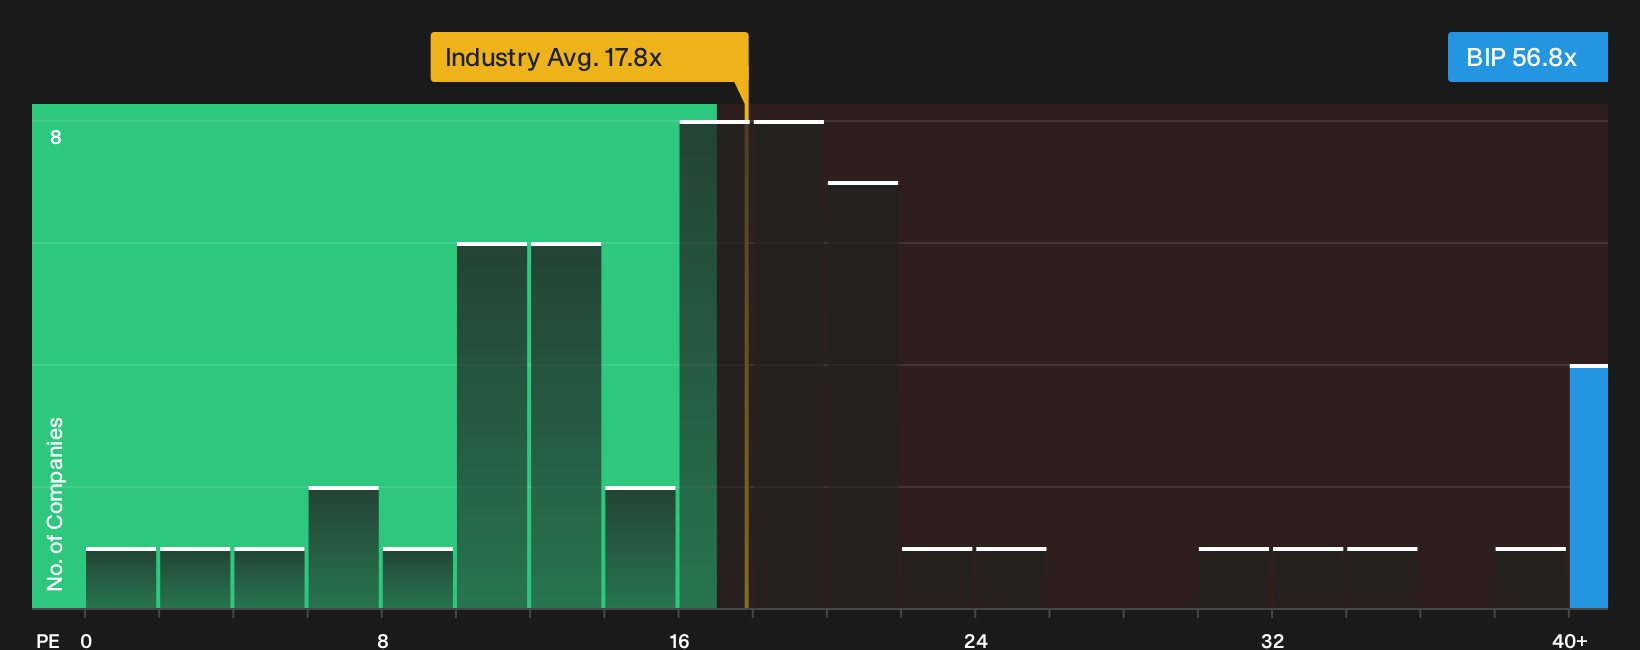
The P/E ratio suits Brookfield Infrastructure Partners because earnings sit at the center of how holders think about this type of asset-heavy partnership. On that yardstick, the units trade on about 56.8x earnings, which is well above the integrated utilities industry average of roughly 17.8x. That is also rich relative to the broader peer group at about 20.4x, so you are paying a far higher price for each dollar of profit than is common across similar businesses.
The Fair Ratio model, which blends the partnership’s growth profile, profitability, size and risk into a tailored benchmark, points to Brookfield Infrastructure Partners screening as overvalued on this P/E. The gap is wide enough that the framework looks more like a warning flag rather than a precise target. This suggests the market is placing a heavy premium on the reliability and future potential of the earnings stream. Anyone considering the stock needs to judge whether that confidence is justified before accepting such a steep multiple as reasonable for long term ownership. Explore the numbers behind Brookfield Infrastructure Partners's P/E valuation.
The Brookfield Infrastructure Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Brookfield Infrastructure Partners valuation puzzle leaves off and spell out which future paths for growth, margins and earnings would need to play out for the units to look meaningfully under or over today's price. Each one turns Brookfield Infrastructure Partners' implied fair value into a thesis about the business that you can track over time, rather than a single frozen snapshot.
One of the top community narratives on Brookfield Infrastructure Partners: 25% undervalued
"The current narrative that Brookfield Infrastructure Partners is undervalued suggests that the share price does not fully reflect the scale of its AI driven infrastructure pipeline..."
Discover why this Narrative puts Brookfield Infrastructure Partners at 25% undervalued.
One more Brookfield Infrastructure Partners check that belongs beside the earnings multiple
Price and profits only tell you so much about Brookfield Infrastructure Partners, because the people steering the assets and the way they are rewarded can tilt long term outcomes in subtle but powerful ways. See who runs Brookfield Infrastructure Partners and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com