
Knowles (KN) Could Be 15% Undervalued After Expanding Its RF Product Portfolio
Knowles (KN) has rolled out its ATT A-Series attenuators, a fresh RF component family aimed at compact, high reliability designs across defense, aerospace, industrial, and communications hardware.
The ATT A-Series launch comes at a time when Knowles shares have climbed strongly, with a year-to-date share price return of 70.02% and a 1-year total shareholder return of 60.10%. However, the 90-day share price performance has eased, suggesting that momentum has cooled following a strong multi-year total shareholder return of 154.74% over three years and 98.51% over five years.
Scan how Knowles fits alongside other RF and industrial hardware plays by reviewing the hand-picked list of solid balance sheet and fundamentals (25 results) in the same corner of the market.
Knowles has already delivered big gains, yet the recent pause in the share price raises a sharper issue. Do the current numbers still point to potential upside, or has most of the rerating already played out?
Most Popular Narrative: 15% Undervalued
Knowles last closed at $37.32 while the most followed narrative pegs fair value at $43.75, so the story being told by the models is that the shares trade at a discount and that this gap rests heavily on how earnings and margins evolve under current growth plans.
The expansion of specialty film production and the launch of new product lines, such as inductors, are set to increase Knowles' total addressable market, providing incremental growth opportunities that should support revenue acceleration and potentially higher margins as these initiatives scale.
Knowles' ongoing focus on delivering differentiated, custom-engineered solutions and scaling through operational efficiency is helping the company achieve higher factory utilization and margin improvement, positively impacting net margins and earnings.
See why 2 investors see Knowles as 15% undervalued.
Result: Fair Value of $43.75 (UNDERVALUED)
Still, the Knowles narrative can be knocked off course if the product mix continues to pressure Medtech margins, or if new capacity ramps extend scrap costs and factory inefficiencies.
Find out about the key risks to this Knowles narrative.
Another View On Knowles Valuation
The analyst narrative presents Knowles as about 15% undervalued using earnings forecasts and a future P/E of roughly 35x. A second lens tells a tougher story. The SWS DCF model estimates future cash flows at $11.49 per share, well below the current $37.32 price, which appears expensive on that basis.
The gap between an earnings based fair value of $43.75 and a DCF output under $12 raises a straightforward question for investors: Which set of assumptions seems closer to how Knowles will convert revenue into cash over time, and what margin of safety that leaves at today’s price.
Look into how the SWS DCF model arrives at its fair value.
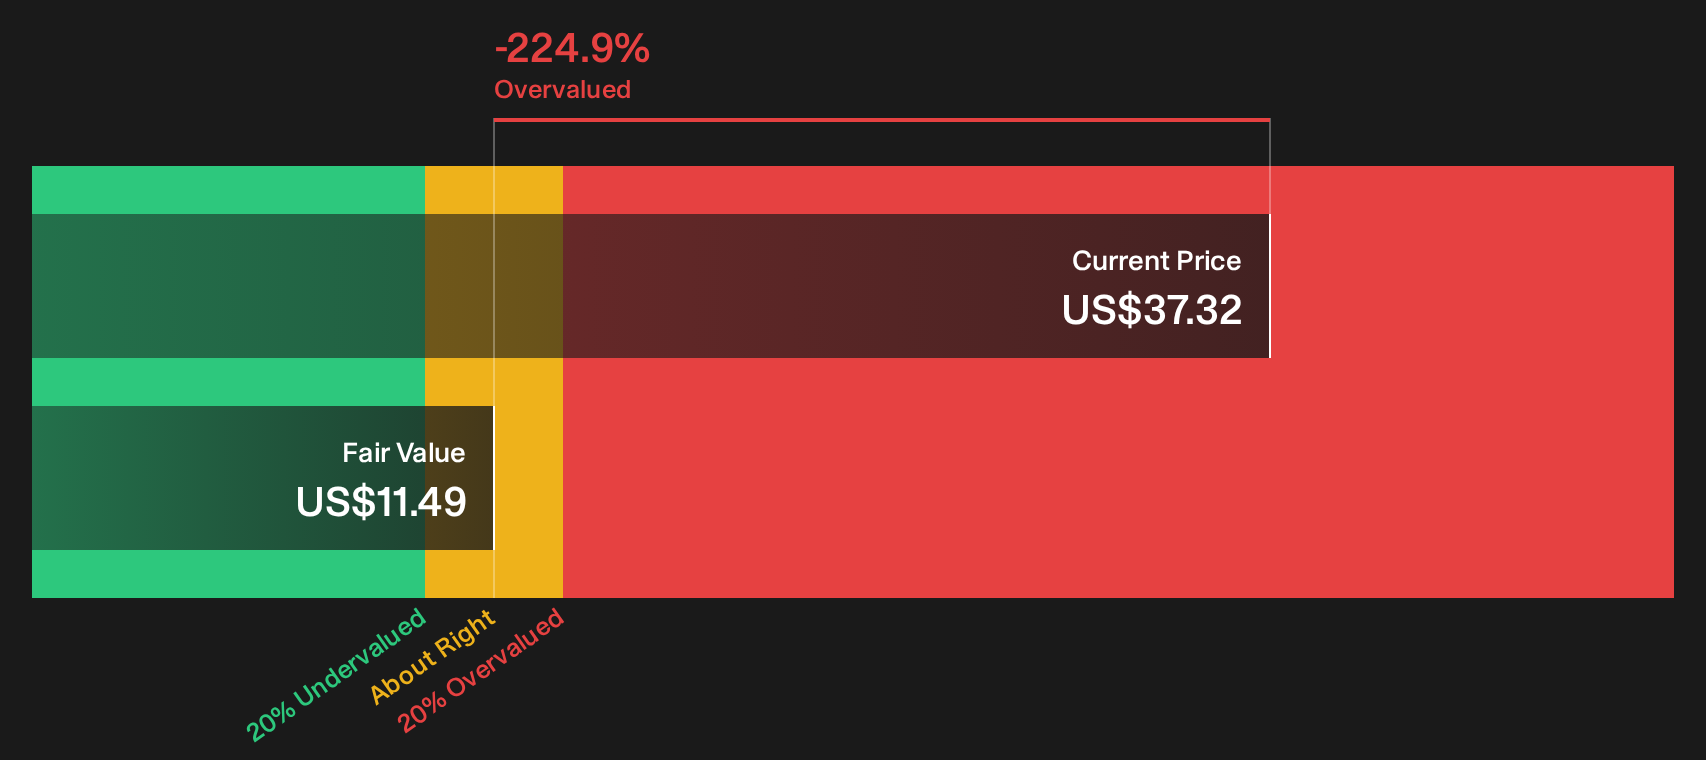
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Knowles for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Knowles is mixed, and that is exactly when fresh eyes on the numbers can matter most, so move quickly and pressure test the optimism by walking through the 2 key rewards
Looking for more investment ideas beyond Knowles?
If Knowles has you rethinking what belongs in your portfolio, broaden the search with other carefully filtered opportunities before the next move leaves you watching from the sidelines.
- Target resilient compounders by scanning a curated 32 resilient stocks with low risk scores that focuses on businesses with sturdier profiles when conditions get choppy.
- Hunt for value by reviewing a focused 17 high quality undiscovered gems that highlights under-the-radar companies with stronger fundamentals than their current pricing suggests.
- Strengthen your core holdings by working through a disciplined 6 dividend fortresses that surfaces candidates with higher yields and more robust payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com