
Will Earnings Beat Change MKS Stock Narrative (MKSI)
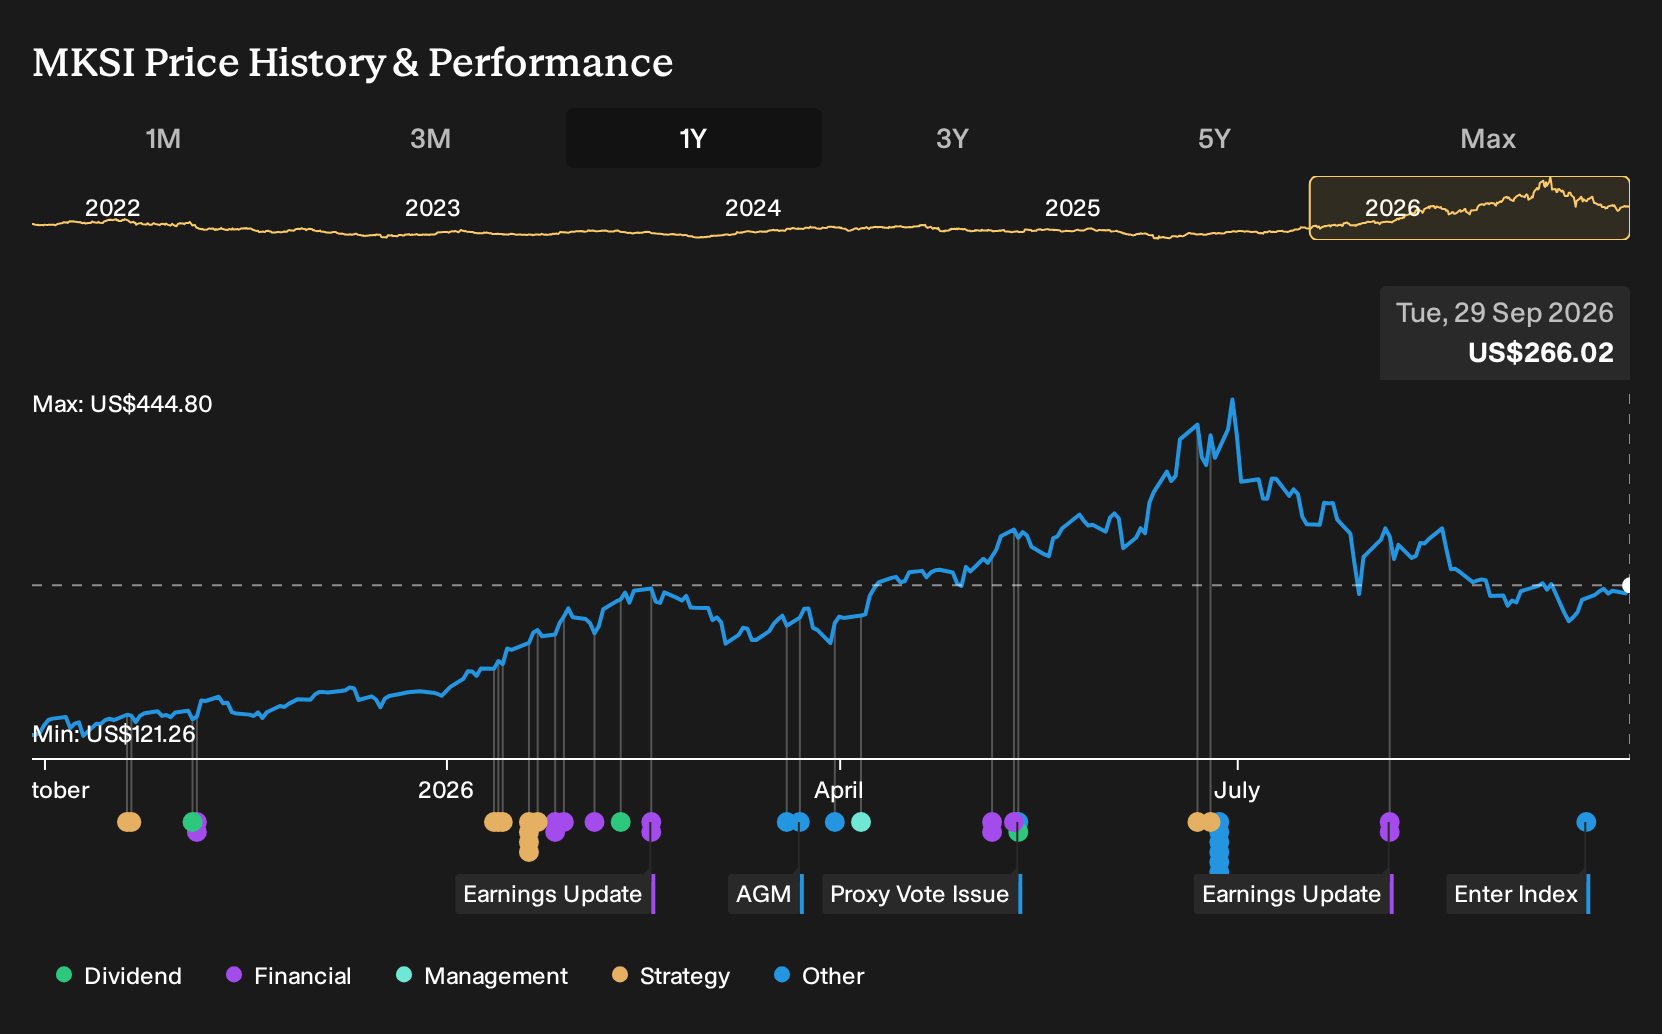
- MKS Inc. was added to the FTSE All-World Index after reporting a stronger than expected first quarter, with meaningful revenue growth and earnings per share above consensus, supported by demand tied to AI focused semiconductor manufacturing.
- The combination of index inclusion and AI linked semiconductor exposure highlights how MKS Inc. is increasingly tied to long cycle chip production and tooling decisions rather than only short term equipment spending.
- The next focus will be on how this index inclusion and AI driven semiconductor demand could reshape MKS Inc.'s broader investment narrative.
MKS Investment Narrative Recap
To own MKS, you need to believe that AI focused chip manufacturing can keep pulling demand through its vacuum, photonics, and materials segments, and that management can translate that demand into steadier cash generation. The near term swing factor remains how quickly AI semiconductor projects convert into orders and services revenue, rather than one off equipment spending.
The biggest operational risk right now sits on the balance sheet and cash side. MKS carries meaningful leverage and debt is not well covered by operating cash flow, which can restrict flexibility if chip capital spending slows or trade tariffs pressure margins. The FTSE All World inclusion does not directly change those fundamentals.
The clearest recent data point that links to this index move is the stronger than expected first quarter that Cooke & Bieler flagged, with meaningful revenue growth and earnings per share above consensus, helped by AI related semiconductor demand. That update showed investors how tightly MKS is tied to AI driven capacity and complexity in chipmaking.
For you as a shareholder, the question is whether that pattern can persist while the firm manages concentrated customers, cyclical NAND exposure, and high borrowing. If AI related orders stay solid and services from the installed base keep building, MKS can have more room to address leverage and tariff related margin pressure, which remains central to the medium term story.
MKS' current earnings sit at $439.0 million and analysts see that moving to $1.7b by 2029, which is an earnings increase of about $1.3b, supported by a projected 20.3% yearly rise in revenue that would take sales to $7.6b in the same year.
Uncover why MKS' fair value indicates a 57% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on MKS leans hard into tariff and geopolitics risk. Those analysts were already more cautious, assuming revenue of about US$6.7b and earnings of roughly US$1.6b by 2029, versus the higher consensus path. You can treat that as a reminder that opinions differ widely and may shift after this index news.
Explore 3 other MKS fair value estimates, including one that suggests it could be worth just $253.48.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your MKS research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MKS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate MKS' overall financial health at a glance.
Looking for more investment ideas beyond MKS?
If the MKS story has sharpened your thinking on AI, cash flow, and balance sheet risk, it can be useful to compare it with other companies that share some of those qualities or sit at very different points on the risk spectrum.
Use the Simply Wall St Screener to widen your watchlist and pressure test your thesis against a broader set of opportunities.
- For investors who want potential upside without ignoring financial strength, consider reviewing a curated set of 32 high quality undervalued stocks.
- If capital preservation ranks high for you, stress test your portfolio idea against a group of 32 resilient stocks with low risk scores that score well on resilience.
- When you want to hunt for less followed opportunities with solid fundamentals, scan our 17 high quality undiscovered gems that may not yet be widely tracked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com