
Iress And 2 Australian Undervalued Tech Stocks To Own
Australian inflation recently accelerated to 4% and the cash rate is at a 15 year high of 4.6%. Higher funding costs can pressure many sectors, yet often leave some technology stocks trading at prices that do not fully reflect their potential. That gap is where opportunity lives. This article highlights three undervalued Australian tech stocks from our screener that could appeal to patient investors willing to look past the headlines.
The three undervalued tech stocks below are just a sample, with our full screen surfacing 21 more Australian technology companies with equally compelling stories that are not covered here. To go deeper on this idea, head into the Undervalued Tech screener to identify, filter, and analyze the highest conviction opportunities that fit your criteria.
Iress (ASX:IRE)
Iress is a pure software and services play in financial markets. This fits squarely with the Undervalued Tech theme, as its trading, portfolio and wealth platforms underpin recurring fee income from brokers, advisers and super funds, while some non software data revenue adds diversification.
Iress generates most of its business from APAC Wealth Management at about A$138 million, UK Wealth & Sourcing at roughly A$113 million, and Global Trading & Market Data at around A$254 million, with a market cap near A$1 billion placing it firmly in mid cap territory.
For tech investors, Iress offers direct exposure to financial software that underpins trading and wealth workflows, where long contracts and embedded systems can matter far more than quarterly noise or short term sentiment.
"Although the new cloud native EMS and Interop focused trading stack is intended to support richer data products and more modular workflows, client migration and partner adoption risk remain. If take up is slower than planned, trading revenue and margin expansion from these investments could be more muted than the current cost outlay suggests."
One question is what happens if a relatively quiet shift in how clients use this software meaningfully changes the balance between steady margins and future growth potential.
If that trade off between margins and future growth potential is what interests you, read the full narrative for Iress to see how the thesis could accelerate from here.

Bravura Solutions (ASX:BVS)
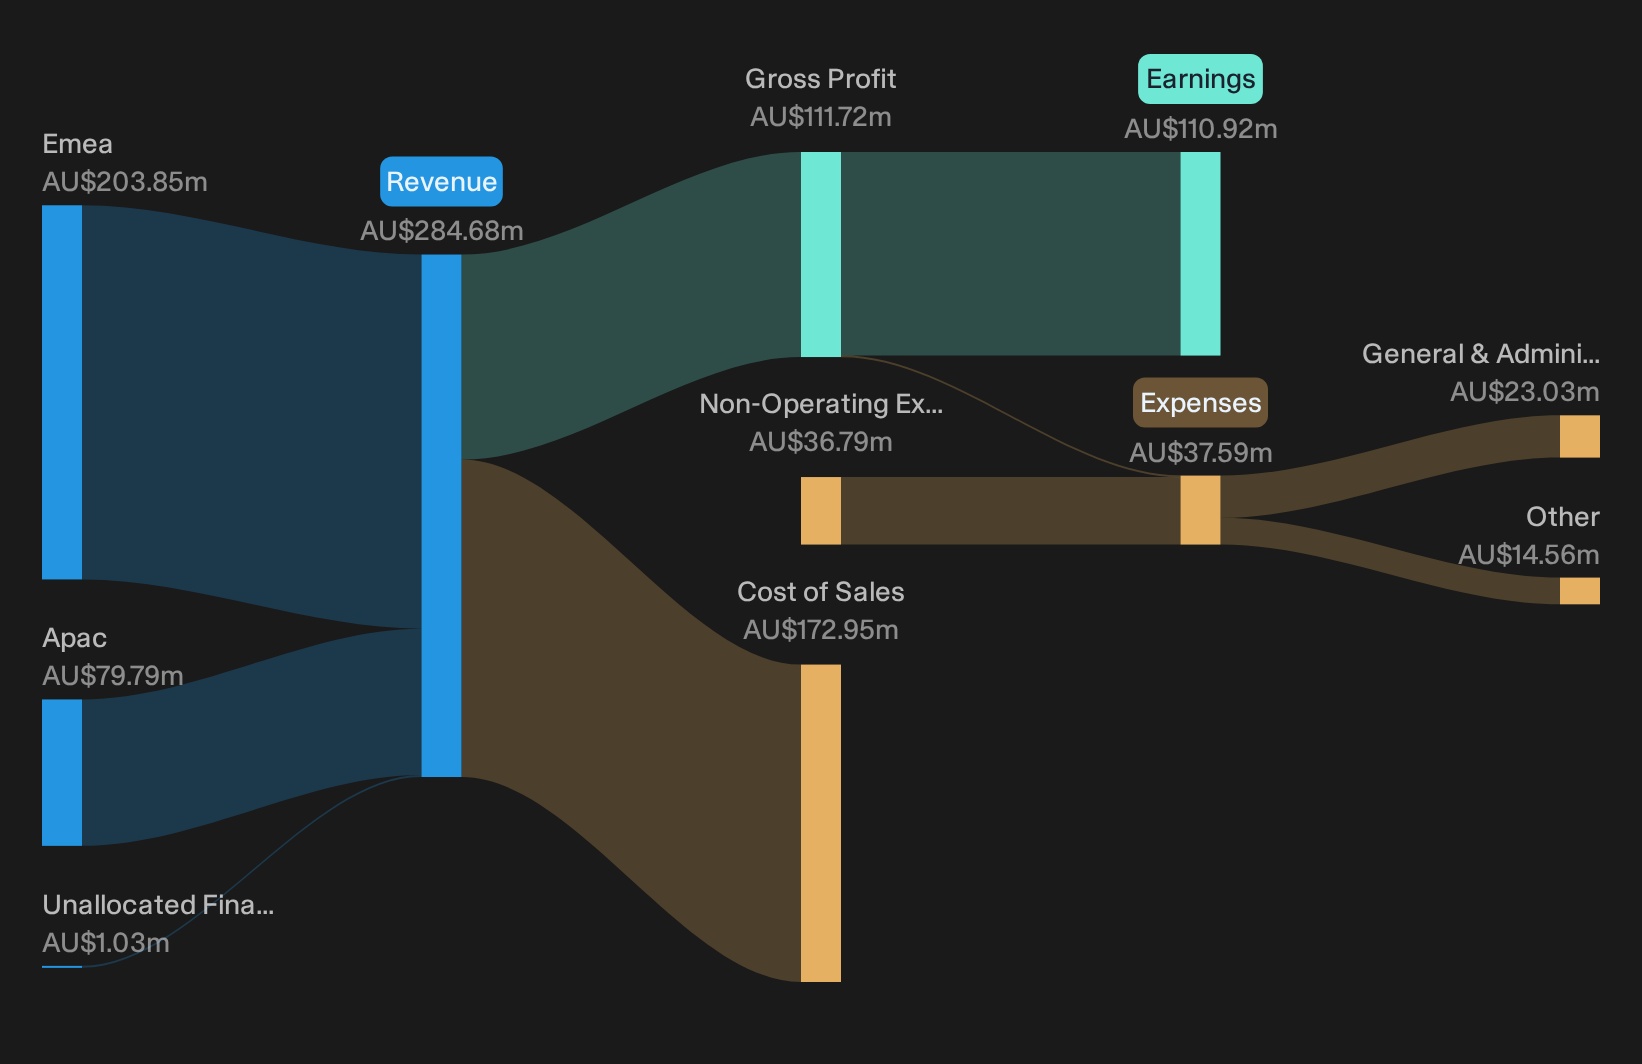
Bravura Solutions is a wealth and funds administration software specialist, with its Sonata and Sonata Alta platforms placing it firmly in the Undervalued Tech theme. The group generated about A$79 million from APAC and A$204 million from EMEA, and has a market cap near A$1.4b.
For investors scanning the Undervalued Tech list for real, enterprise-grade software rather than hype, Bravura Solutions offers a direct line into the plumbing of pensions, super and wealth platforms where switching costs are high and product depth really matters.
"Growing regulatory requirements for transparency and compliance in financial services are pushing institutions to adopt modern, third-party platforms, and Bravura's continued investment in product relevance and partnerships (e.g., with administration providers) positions it to benefit from this trend, supporting stable to growing revenue streams and improved client stickiness."
The real test comes if a single pressure point inside that pension software stack starts to reshape how much pricing power and margin resilience Bravura can hold onto.
If that pressure point is what you are watching, read the full narrative for Bravura Solutions to see how Bravura Solutions could convert regulatory change into accelerating earnings quality.
Life360 (ASX:360)
Life360 runs a mobile-first safety and location platform that squarely fits the Undervalued Tech theme, with most of its US$572 million plus in software and programming revenue tied to subscriptions, and an A$4.6b market cap reflecting a sizeable listed presence.
For investors hunting for tech exposure tied to everyday family routines rather than pure enterprise software, Life360 offers a blend of subscription services and hardware that link directly to how people protect kids, cars, pets and valuables.
"New premium services and integrated hardware (for example, unified Tile and the forthcoming GPS pet tracker) deepen Life360's value proposition, increase member engagement, and create higher conversion to paid tiers. These ecosystem enhancements reinforce recurring revenue growth and may further expand net margins over time as premium offerings scale."
The real swing factor is what happens if one subtle shift in how users value that safety bundle materially changes pricing power and long term profitability.
That pricing hinge is exactly what the full narrative for Life360 unpacks, showing how Life360’s ecosystem bets could turn engagement into accelerating monetisation, while also flagging the key risks.

Seeking Fresh Alternatives Beyond Tech?
New ideas move fast. By the time the crowd spots the next breakout, the cleanest entry point may already be flying past. For now, get in early.
- Spot where steady cash generation meets low drama by scanning the curated list of solid balance sheet and fundamentals (12 results) before others get caught chasing stories with weaker foundations.
- Ride structural power demand and grid upgrades by tracking the focused 39 power grid technology and infrastructure stocks while the theme is still building momentum rather than already priced in.
- Catch the cash flow shift toward electrification and infrastructure metals by reviewing the targeted 17 top copper producer stocks before latecomers crowd into the same producers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com