
SELLAS Life Sciences Group (SLS) Stock Looks Expensive Against Its Book Value
SELLAS Life Sciences Group has delivered a very large 3 year share price gain. With the stock recently closing at US$11.51, the live question is whether that move is supported by what its balance sheet is actually worth on paper.
- Over the past 3 years, SELLAS Life Sciences Group has returned roughly 7x, which puts a lot of weight on whether investors are now paying well above the value of the company’s net assets.
- Fresh preclinical data for SLS009 in pancreatic cancer and ongoing work on the cancer vaccine candidate Galinpepimut S can affect how you think about future funding needs and the speed at which book value might change from here.
- There is a second opinion on SELLAS Life Sciences Group worth weighing. See what analysts think SELLAS Life Sciences Group's shares could be worth.
The issue now is whether SELLAS Life Sciences Group's current share price lines up with its book value when set against the industry average.
If you are weighing whether SELLAS Life Sciences Group's sharp 3 year run still lines up with its book value, it can help to compare it with 32 high quality undervalued stocks.
Is SELLAS Life Sciences Group Getting Expensive on Book Value?
P/B is often the cleanest yardstick for a clinical stage biotech like SELLAS Life Sciences Group, because tangible equity sits at the center of how investors frame downside protection and future funding capacity.
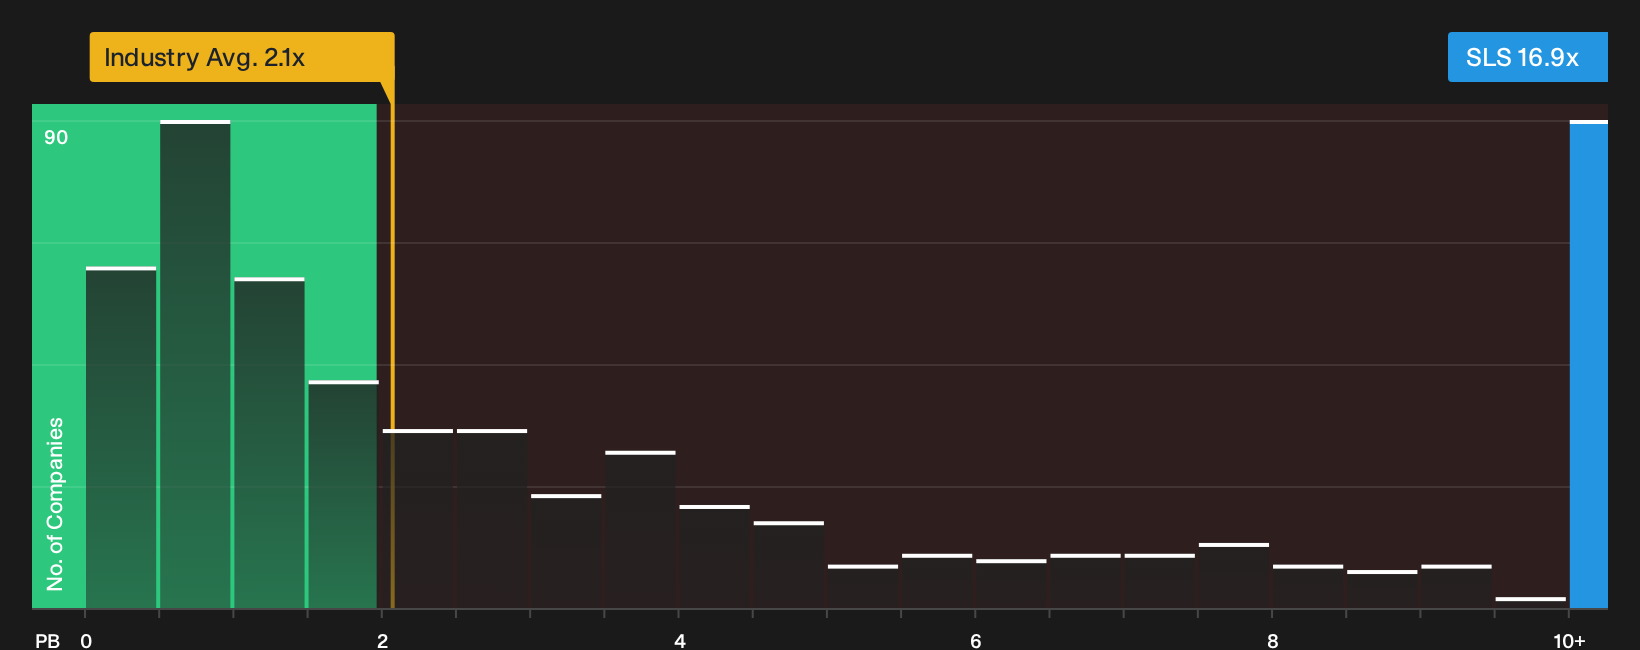
Right now, SELLAS Life Sciences Group trades at a P/B of about 16.9x, which is far above the wider Biotechs industry average of roughly 2.1x and also well ahead of the peer group around 4.9x. That gap suggests the market is placing a lot of value on the current pipeline and optionality, rather than just the assets already on the balance sheet.
Because the recent SLS009 pancreatic cancer data and the ongoing work on Galinpepimut S are front of mind for investors, optimism around those programs looks heavily reflected in the multiple, and the stock screens as overvalued on a pure book value comparison. The valuation model also heavily penalises the firm’s current losses, so the extreme premium reads less like a precise mispricing and more like a signal that expectations are very high at this stage. Explore the numbers behind SELLAS Life Sciences Group's P/B valuation.
The SELLAS Life Sciences Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the SELLAS Life Sciences Group valuation puzzle leaves off by spelling out the future growth, margin and earnings paths that would need to hold for the stock to be worth materially more or less than today’s price. Each scenario ties a fair value to a specific set of potential catalysts and risks so you can track which storyline is gaining traction over time on the Community page.
A written, number driven view on SELLAS Life Sciences Group helps pin down what would need to go right in areas like SLS009 in pancreatic cancer and the Galinpepimut S vaccine program for today’s P/B premium to keep making sense. It provides a concrete set of assumptions you can revisit as new clinical data and funding decisions emerge over the next few years.
Share your own Narrative for SELLAS Life Sciences Group and set out the assumptions behind your valuation.
The price of SELLAS Life Sciences Group is only one piece of your decision
Share price and P/B tell you how the market values SELLAS Life Sciences Group today, but broker models also sketch where they think the business could be a few years from now. Explore where analysts expect SELLAS Life Sciences Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com