
Strong Results Could Be A Turning Point For Comfort Systems USA Stock
- Comfort Systems USA reported first half 2026 revenue of US$6.13b and net income of US$812m, supported by heavy exposure to technology linked construction and modular solutions.
- The acquisition of Hunt Electric for US$206m adds roughly US$250m of expected annualized revenue, deepening Comfort Systems USA's role in integrated mechanical and electrical work for data centers and other complex projects.
- This article examines how Comfort Systems USA's technology focused financial results influence the investment narrative available to investors.
Scan beyond Comfort Systems USA and look for other contractors riding the same data center and AI infrastructure wave with our hand picked 89 AI infrastructure stocks.
Comfort Systems USA Investment Narrative Recap
To own Comfort Systems USA, you need to believe that AI heavy data center, semiconductor and industrial projects keep flowing through its US$14.1b backlog into actual work, and that execution on complex jobs stays tight. The latest results, with US$6.13b in first half 2026 revenue and US$812m in net income, reinforce that this tech leaning mix is real, not just a story.
The short term swing factor is how smoothly that record backlog converts into revenue while modular capacity ramps toward customer targets. The biggest risk is concentration. If large technology or industrial programs slow or slip, or if project mix reverts toward less complex work, Comfort Systems USA could see both growth and margins come under pressure.
The Hunt Electric deal is the clearest operational update tied to this data center and AI build out. Comfort Systems USA paid US$206m for a business expected to add about US$250m of annualized revenue, mainly in the Western U.S. electrical market. That extra scale directly feeds into the technology focused construction narrative that has been driving recent financial performance.
For you as an investor, the acquisition matters because it deepens Comfort Systems USA’s ability to offer integrated mechanical and electrical packages on large, power hungry projects. That can support backlog quality and win rates, but it also raises execution risk if complex jobs are mispriced or delayed. With strong recent earnings and a higher P/E than the broader construction group, any stumble on integrating Hunt or delivering these combined projects could shift sentiment quickly.
Comfort Systems USA Analyst Expectations In Focus
Comfort Systems USA's current analyst storyline points to revenue of US$19.6b and earnings of US$2.9b by 2029, built on forecasts of 20.3% yearly top line growth and a move from US$1.4b of earnings today to that higher figure. This implies roughly a US$1.5b increase in profit over the period.
Uncover why Comfort Systems USA's fair value indicates a 32% potential upside to its current price that may not last much longer.
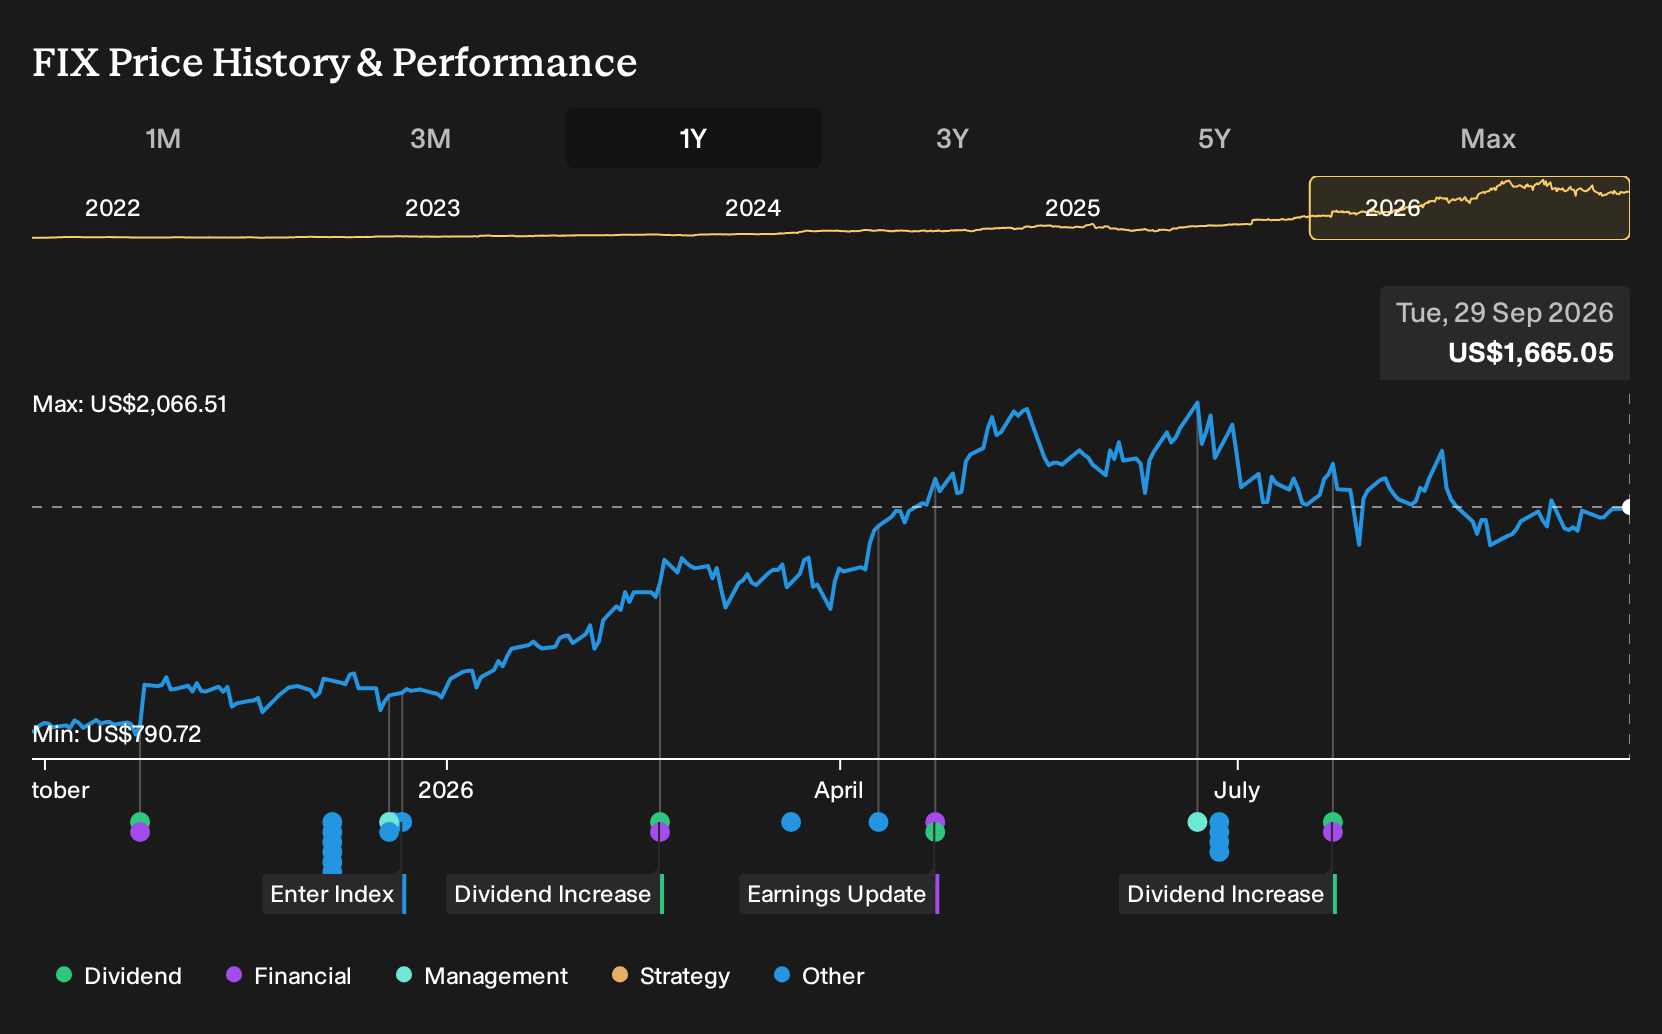
Exploring Other Perspectives
One alternate view puts labor risk ahead of data center demand. The most cautious analysts worry that wage pressure and staffing gaps could squeeze Comfort Systems USA more than expected. They were only penciling in revenue of about US$15.7b and earnings of roughly US$2.2b by 2029. That is well below the consensus path. These estimates, all set before the Hunt Electric news, may shift as fresh information filters through. Treat them as one of several viewpoints to test against your own expectations.
Explore 5 other Comfort Systems USA fair value estimates, including one that suggests it could be worth just $1,910.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Comfort Systems USA research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Comfort Systems USA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comfort Systems USA's overall financial health at a glance.
Looking for more Comfort Systems USA sized ideas?
If Comfort Systems USA has sharpened your focus on where capital intensive projects and strong execution can meet, it can be useful to scan for other stocks with clear financial profiles that suit your own risk and income preferences.
- If stability matters most to you, start with companies that pair conservative balance sheets with solid fundamentals using our list of solid balance sheet and fundamentals (25 results).
- For investors hunting for potential mispricing, filter for companies that combine quality metrics with valuations that screens flag as attractive through the 32 high quality undervalued stocks.
- If consistent cash returns are a priority, focus on businesses offering higher income potential and assess them using the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com