
Microsoft (MSFT) Faces Michael Burry Warning Over $3 Trillion AI Liabilities
- Michael Burry has flagged what he describes as about US$3 trillion in off-balance-sheet AI data center liabilities at Microsoft (NasdaqGS:MSFT) and major peers.
- His warning focuses on long term infrastructure commitments for AI capacity that do not appear as traditional debt on company balance sheets.
- Burry argues that if future AI demand falls short of these obligations, large writedowns and funding strains could ripple across the broader economy.
- The alarm over hidden AI data center liabilities at Microsoft and rivals sits alongside other structural forces our research has uncovered. Check out 3 other big wins that Microsoft investors should know about.
For readers who want more ideas around the picks and shovels behind the AI buildout, the next step is 89 AI infrastructure stocks.
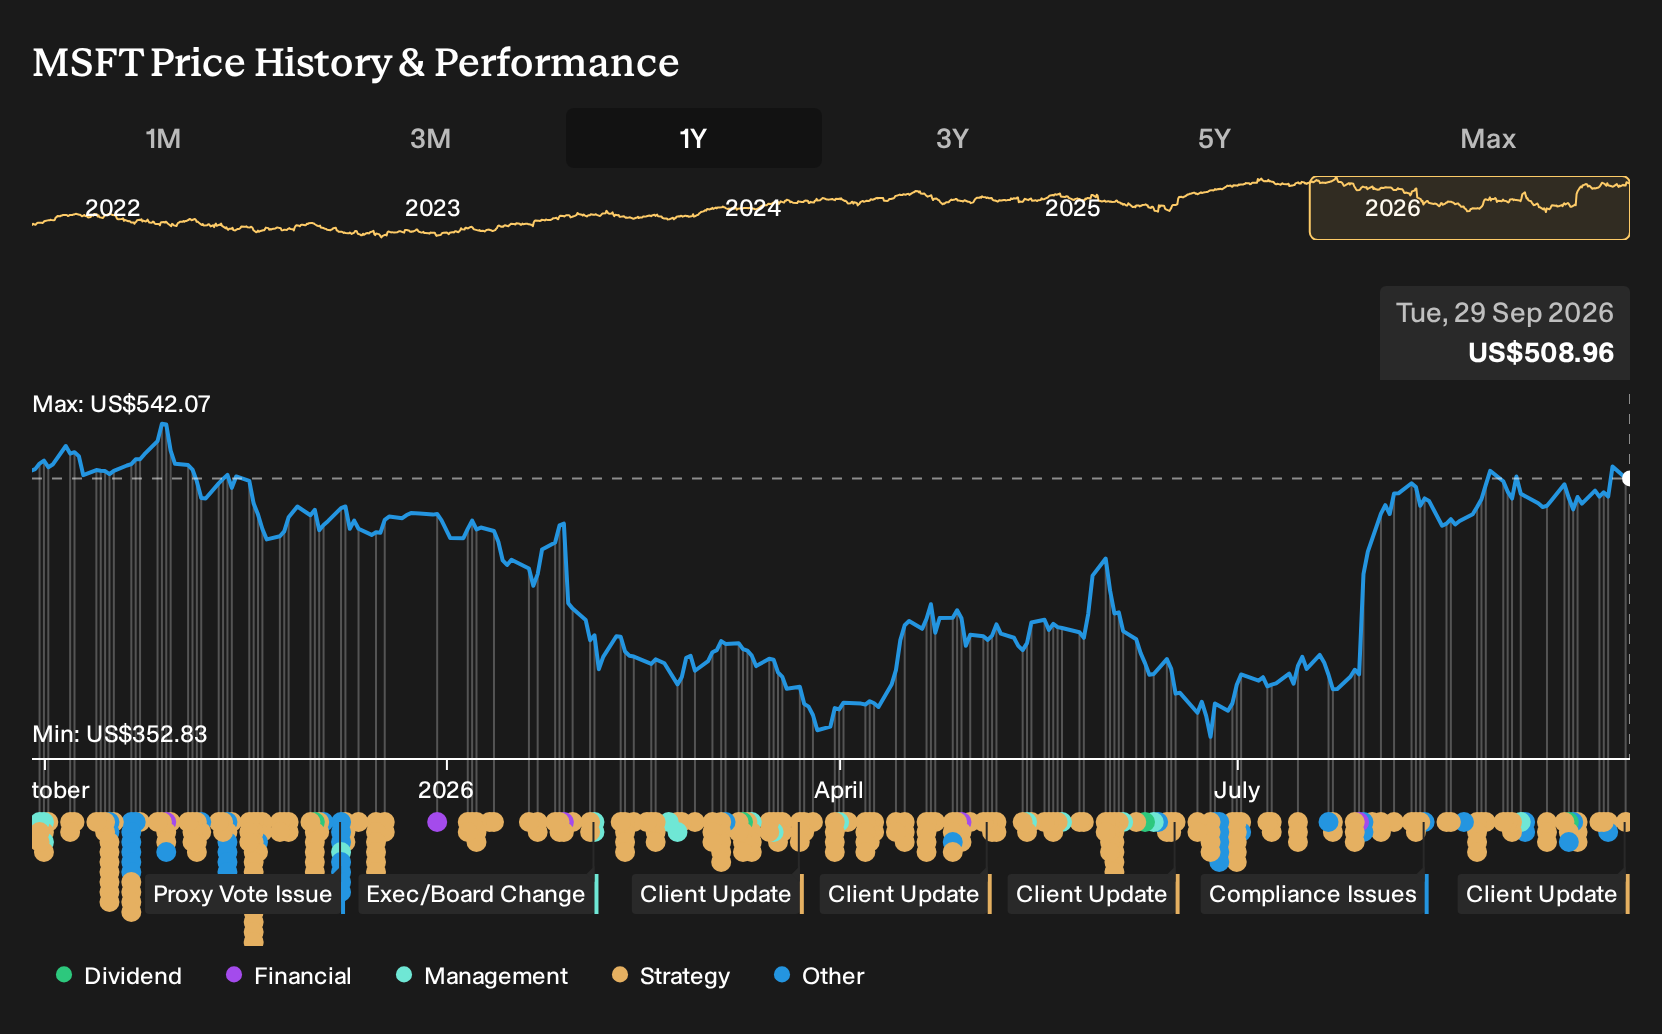
Microsoft is a US software heavyweight with a US$3.8 trillion market cap, building and running cloud platforms that power much of the AI infrastructure now being scaled out by large enterprises. Its role as both a developer of AI tools and a provider of the underlying data center capacity puts these long term infrastructure commitments at the center of how investors assess risk.
See which insiders are buying and selling Microsoft following this latest news.
Why Burry’s AI liability warning matters for the Microsoft Narrative
Michael Burry flagging roughly US$3t in off balance sheet AI data center commitments runs straight into the Microsoft Narrative’s biggest risk lever: the need for massive AI and cloud CapEx to earn its keep. The core story assumes elevated spending on Azure capacity, partners and long term energy deals can still support margin stability and high quality free cash flow. Burry’s critique does not dismantle that thesis, but it underlines the concern that large, contracted AI infrastructure, much of it tied to hyperscale workloads, could strain returns if usage or pricing power fall short of expectations.
See how these catalysts shape Microsoft's path to a $573 fair value.
For this warning to meaningfully shift how investors treat Microsoft, watch the next few quarters of Azure and Copilot disclosure, especially any new color on long dated data center, power and lease obligations relative to AI related revenue. Evidence that contracted capacity and reported cash generation are moving in step, rather than AI commitments racing ahead, will be the key test of whether Burry’s off balance sheet alarm translates into a real break in the existing Narrative.
The question on Microsoft that rarely gets asked
One piece of the Microsoft puzzle barely covered in AI headlines is who actually calls the shots in Redmond, how their pay packets are structured, and what that means for the choices you see on screen. See who is actually steering Microsoft, and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com