
How Investors Are Reacting To Tapestry (TPR) Google AI Checkout Rollout
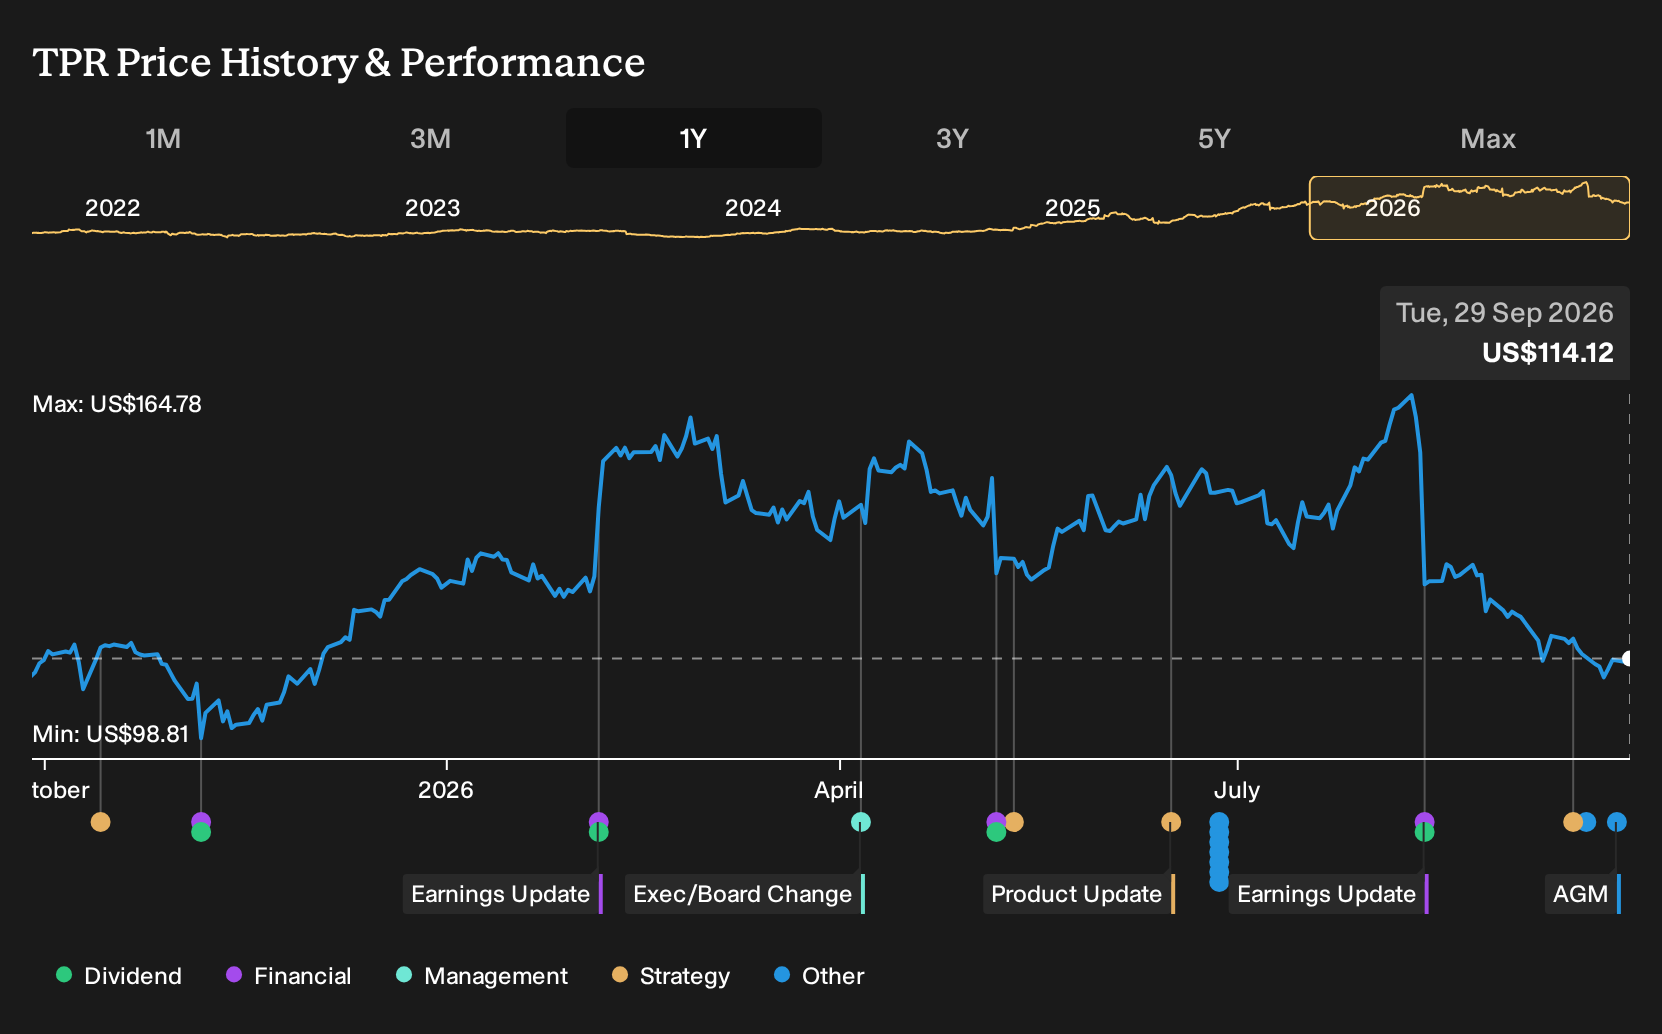
- Tapestry recently brought its Coach and Kate Spade brands into Google's AI shopping ecosystem, allowing U.S. consumers to purchase products directly within Google Search, AI Mode, and the Gemini app using UCP-powered checkout and Google Pay.
- This tighter link between Tapestry's brands and Google's AI tools could influence how effectively the group converts search interest into direct sales with fewer drop off points.
- We will now look at how Tapestry's investment narrative could be influenced by its move to enable direct AI driven checkout within Google.
Scan how Tapestry is leaning into AI powered shopping, then size up other consumer businesses tied to similar trends with our curated list of 88 AI infrastructure stocks.
Tapestry Investment Narrative Recap
Tapestry appeals to shareholders who buy into a straightforward idea. The group needs Coach to keep pulling in younger customers, international regions like Greater China and Europe to deepen, and Kate Spade to move closer to being a consistent earnings contributor rather than a drag. In the near term, the key swing factor remains execution on brand health and direct to consumer, not index moves.
The biggest operational risk still sits with Kate Spade and its recent revenue declines, alongside exposure to tariffs and heavier spending on marketing and omnichannel. Inclusion in the FTSE All World Index helps liquidity and visibility, but does not directly change these fundamentals or reduce the execution risk around customer acquisition and profitability.
The Google AI shopping integration for Coach and Kate Spade looks most relevant for the current catalysts around digital and direct to consumer. Tapestry already leans on higher margin direct channels. Shortening the path from product discovery to checkout could affect conversion and data quality if customers adopt the new flow at scale.
Execution is the key variable. The UCP powered, Google Pay checkout is live only in the U.S. today. Any operational upside hinges on stable performance, clean customer experiences, and the ability to roll this out across more markets over time. For an investor, this sits alongside the existing risks around tariffs, debt and the ongoing rebuild of Kate Spade.
Tapestry's narrative projects US$9.6b revenue and US$1.9b earnings by 2029, which assumes 6.3% yearly revenue growth and an earnings increase of about US$0.4b from US$1.5b today.
Uncover how Tapestry's fair value indicates a 46% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the lowest Tapestry analysts focus on margin risk rather than AI upside. They were working off slower revenue growth of about 4.5% a year and earnings of roughly US$1.7b by 2029, compared with US$1.9b in the baseline view. That more cautious setup could shift if the Google AI checkout and index inclusion change conviction.
Explore 3 other Tapestry fair value estimates, including one that suggests it could be worth just $111.38.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tapestry research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tapestry. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tapestry's overall financial health at a glance.
Looking For More Ideas Beyond Tapestry?
Once you have a view on Tapestry, it can help to line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter for fundamentals first, then focus on the story.
- If capital protection comes first for you, start with a basket of steadier profiles drawn from 32 resilient stocks with low risk scores.
- Income focused investors can zero in on businesses with higher yields and sturdier payout records by scanning our 6 dividend fortresses.
- For those hunting for less crowded opportunities with solid financial foundations, the 17 high quality undiscovered gems can surface ideas that are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com