
Zillow Group (ZG) Rolls Out Preview As Fair Value Stays In Focus
Zillow Group (ZG) is in focus after rolling out its Preview pre-market listings across both Zillow and Realtor.com. This joint product push coincides with its recent removal from the FTSE All-World Index.
Despite the product launch, Zillow Group’s share price has slid to US$28.01, with the 7-day share price return down 11.33% and the 30-day share price return down 23.49%, while the 1-year total shareholder return has declined 62.37%. This points to fading momentum even as investors reassess the impact of Preview and the recent index removal.
Scan beyond Zillow Group and explore how other real estate platforms and property-focused businesses are preparing for their next move with the curated 17 high quality undiscovered gems
The selloff and index exit could be read as a verdict on Zillow Group’s fundamentals, or as sentiment breaking away from the underlying business. The valuation work starts by testing which story the current price reflects.
Most Popular Narrative: 41% Undervalued
On the most followed view, Zillow Group screens cheaply against a fair value of $47.23 compared with the latest close at $28.01. This puts the pressure on whether its product flywheel really converts traffic into higher quality revenue over time.
The shift toward integrated, end to end digital transaction ecosystems (like Zillow 360 and Enhanced Markets) is enabling Zillow to capture more ancillary services revenue (mortgages, rentals, software). This is reducing dependence on advertising and expanding top line growth, as well as supporting EBITDA margin expansion through operational efficiencies.
Secular tailwinds from increased mobility, remote work, and persistent demand for digital home search and rental tools are continuing to boost transaction volumes and the need for data rich, tech enabled real estate solutions. This is underpinning Zillow's user growth, increased monetizable connections, and ultimately revenue potential even in a flat macro housing environment.
See why 27 investors see Zillow Group as 41% undervalued.
Result: Fair Value of $47.23 (UNDERVALUED)
Still, the bullish Zillow Group story could unravel if housing affordability remains strained and legal or data access disputes disrupt listings and agent spending.
Find out about the key risks to this Zillow Group narrative.
Another View on Zillow Group’s Valuation
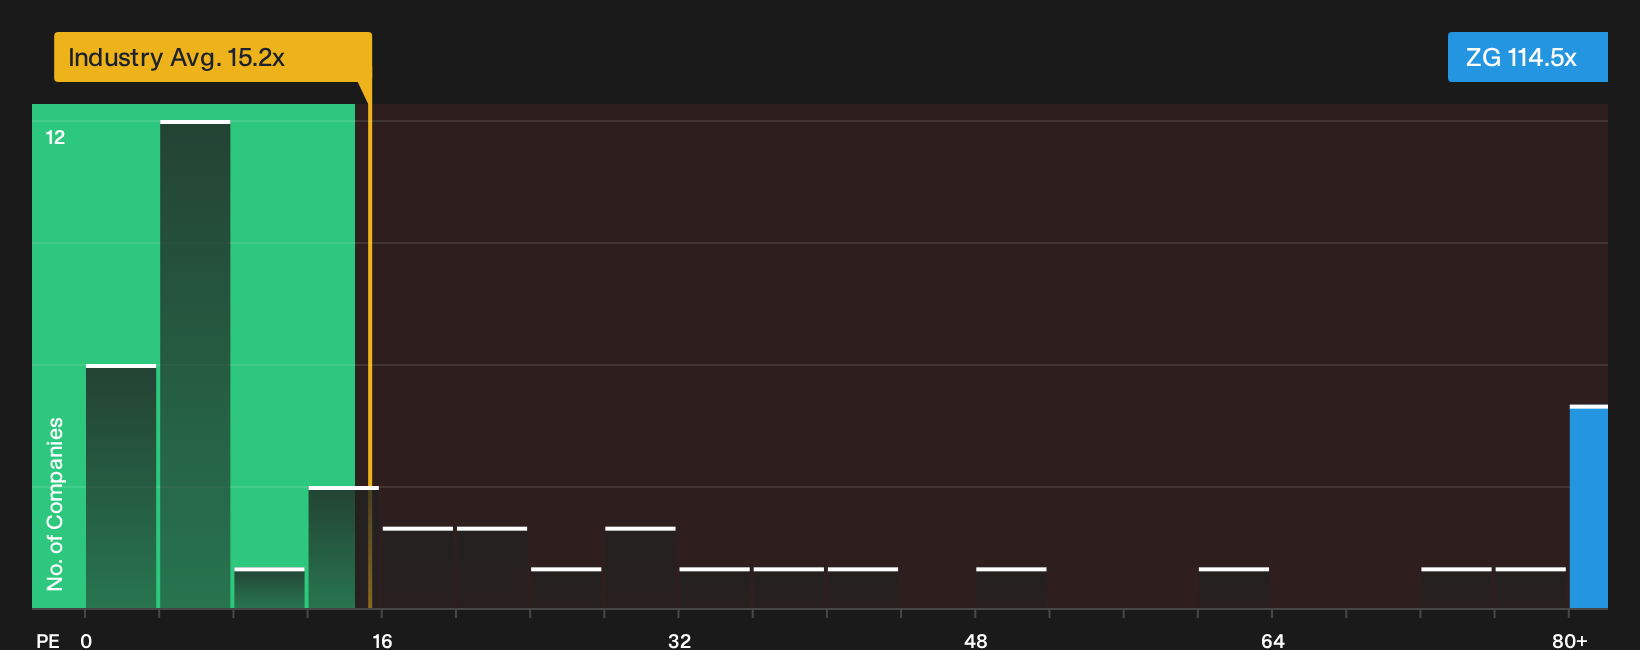
The DCF work points to Zillow Group looking cheap, yet the simple earnings multiple tells a very different story. At a P/E of 114.5x versus 15.1x for the US real estate industry and a fair ratio of 47.1x, the stock trades on a much richer earnings tag that raises clear valuation risk. Which signal do you put more weight on?
To see how this richer earnings multiple stacks up against what the numbers suggest the ratio could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Zillow Group’s valuation can feel messy, so move fast, test the numbers for yourself, and decide where you land on 3 key rewards and 1 important warning sign
Looking for more ideas beyond Zillow Group?
If Zillow Group has you rethinking your watchlist, do not stop here. Broaden your opportunity set with focused stock ideas that match what you care about most.
- Target potential mispricing by scanning companies that combine quality fundamentals with attractive valuations using the 32 high quality undervalued stocks.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with stronger financial footing.
- Reduce stress around downside risk by filtering for 32 resilient stocks with low risk scores that may better fit a steadier approach to compounding wealth.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com