
Huntington Bancshares (HBAN) Lifts 2027 Guidance, Is The Stock Still A Bargain?
Huntington Bancshares (HBAN) recently lifted its 2027 earnings guidance, setting an EPS range of $1.75 to $1.83. This reflects updated pricing conditions and planned steps to address funding and asset yield pressures.
Recent guidance came against a weaker tape for Huntington Bancshares, with the share price down about 9.8% over the past month and about 15.7% over the past quarter. Even so, the 3 year total shareholder return is about 75%, suggesting long term holders have still seen strong gains. Investors appear to be weighing the updated 2027 earnings outlook alongside recent executive retirement news and preferred dividend declarations, which can shift perceptions of both growth potential and risk around the bank’s funding and capital plans.
See how Huntington Bancshares compares with other regional banks repricing for higher earnings targets by reviewing our curated list of 32 high quality undervalued stocks.
Huntington Bancshares now pairs higher 2027 earnings targets with a share price that has recently pulled back. The real work for investors is deciding whether that gap reflects opportunity or lingering risk as the valuation section begins.
Most Popular Narrative: 24% Undervalued
Huntington Bancshares is framed as undervalued in the most followed narrative, with a fair value of about $20.04 against the recent $15.27 close, which puts the 2027 earnings guidance into a wider story about partnerships, fee income and margin pressure.
The expansion into Texas through the Veritex acquisition, together with the Cadence partnership and build-out in the Carolinas, is widening Huntington Bancshares’ footprint in higher population growth markets and is supported by sequential loan and deposit growth, which can underpin future revenue and earnings. Value-added fee businesses at Huntington Bancshares, including payments, wealth management, capital markets and loan and deposit fees, are still growing faster than the balance sheet, with recent double digit growth in several of these areas, which can increase noninterest income and support net margins as funding costs stay elevated.
See why 49 investors see Huntington Bancshares as 24% undervalued.
Result: Fair Value of $20.04 (UNDERVALUED)
Still, the Huntington Bancshares story only holds if partnership synergies and fee growth land as expected, and if funding costs do not squeeze net interest income more severely.
Find out about the key risks to this Huntington Bancshares narrative.
Another View on Huntington Bancshares’ Valuation
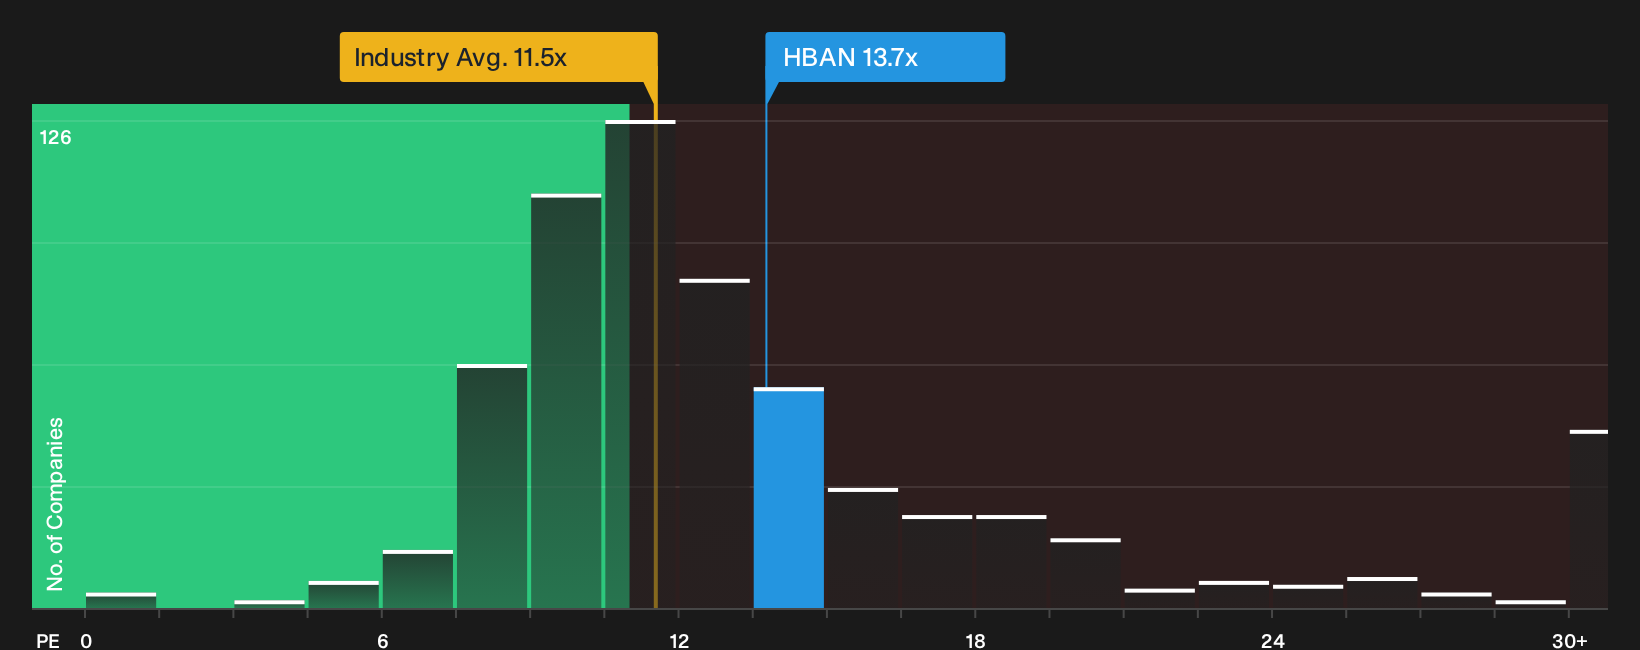
Huntington Bancshares screens as cheap on intrinsic value, yet its P/E of 13.7x is higher than both the US Banks industry at 11.5x and its peer average of 11.8x. The gap versus a fair ratio of 17.4x points to a wide valuation spread. Is that a safety margin or a value trap in the making?
See what the numbers say about this price in more detail in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around Huntington Bancshares can pull you in opposite directions, so move quickly to check the full picture for yourself with 5 key rewards and 1 important warning sign
Looking for more Huntington Bancshares style investment ideas?
If Huntington Bancshares has you thinking more carefully about price, quality and risk, do not stop here. The right shortlist can change your next decision.
- Target potential mispricings by scanning a curated set of value opportunities through the 32 high quality undervalued stocks.
- Prioritise resilience by reviewing companies with strong financial footing and healthy balance sheets using the list of solid balance sheet and fundamentals (25 results).
- Hunt for lesser known opportunities by zeroing in on financially sound businesses in the 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com