
Learn Why The Bull Case For Cavco Industries Stock Could Change Following Frameless Home Launch
- Cavco Industries introduced the Grande Arbor, the first HUD-code manufactured home built without a permanent steel chassis, targeting multigenerational buyers after federal rules removed the chassis requirement.
- The frameless design and double primary suite layout indicate a push into urban and suburban markets where curb appeal, flexible configurations and multigenerational living are gaining attention.
- This development raises questions about how Cavco Industries' frameless HUD-code launch might influence the broader investment narrative around manufactured housing.
Compare Cavco Industries' move into frameless HUD-code housing with other potential opportunities by scanning our hand picked list of list of solid balance sheet and fundamentals (25 results).
Cavco Industries Investment Narrative Recap
Cavco Industries appeals to investors who see a long runway for factory-built housing, supported by housing affordability pressure and federal policy. The major near term swing factor is whether demand and pricing can remain firm enough to support earnings forecasts that indicate about 10.7% annual profit growth alongside slower expected revenue growth of 7.5% a year.
The Grande Arbor launch fits directly into that thesis but does not eliminate key risks. Tariffs on components, soft regional demand including in Florida, and high chattel mortgage rates in the 8% to 9% range still threaten margins and order volumes. Execution on the frameless product rollout is important, while financing conditions remain the primary risk.
The recent Grande Arbor debut ties closely to earlier regulatory changes around chassis rules that analysts had already identified as a potential catalyst for Cavco Industries. Those changes expanded the theoretical addressable market by making HUD-code homes easier to place in traditional neighborhoods and by supporting more varied designs, including multi story formats.
What matters now is how effectively management converts that regulatory opening into actual shipments and stable profitability. Tariff exposure, price sensitivity, and uneven regional demand all remain in the background as practical constraints. If frameless HUD-code offerings scale smoothly through Cavco’s existing factory footprint and Financial Services arm, that could support the earnings growth analysts are modeling.
Cavco Industries' current analyst narrative points to revenues of about US$2.8b and earnings of roughly US$241.8 million by 2029, based on forecast revenue growth of 7.6% a year and earnings today of US$190.6 million. This implies an earnings increase of about US$51.2 million by the 2029 estimate year.
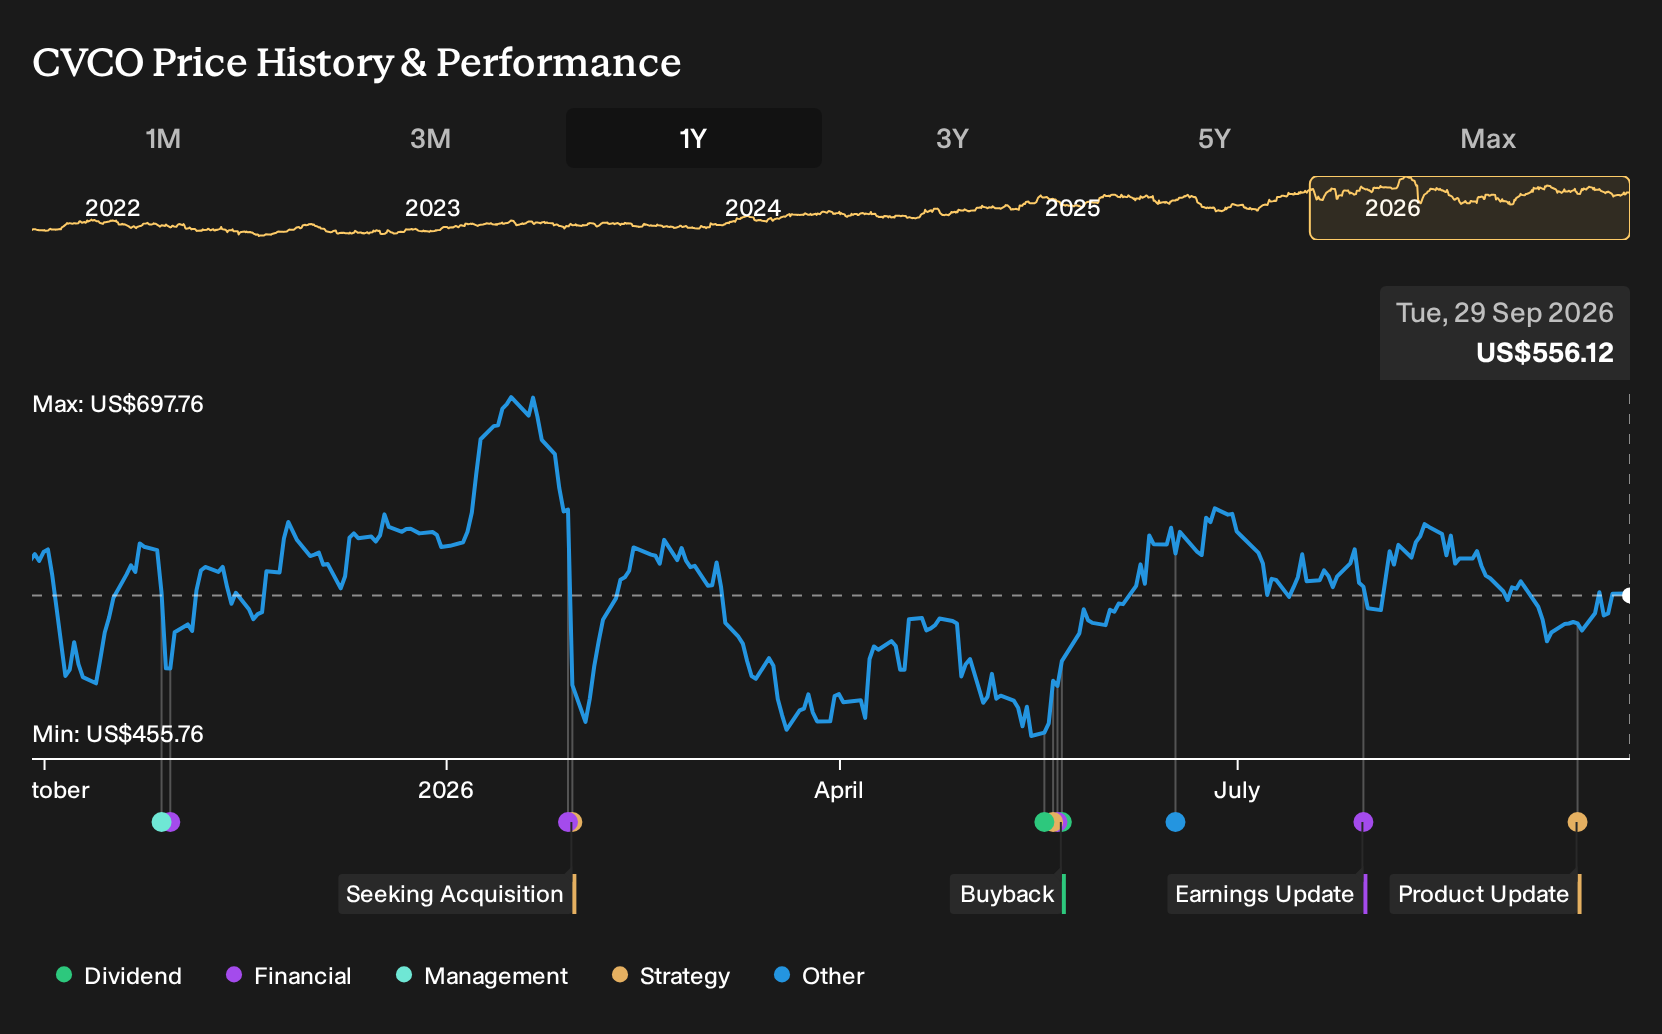
Uncover why Cavco Industries' fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community offers 2 fair value estimates for Cavco Industries, stretching from about US$257.81 to US$625, so opinions range widely. When you layer on tariff risk, uneven regional demand and high chattel mortgage rates, you get a mix of optimism and caution that is worth exploring from several angles.
Explore another Cavco Industries fair value estimate, including one that suggests as much as 54% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cavco Industries research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Cavco Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cavco Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cavco Industries?
If Cavco Industries has sharpened your view on housing and construction, it can help to widen the lens and compare it with other businesses that line up with your risk tolerance, return expectations, and balance sheet comfort level. The Simply Wall St Screener is built for exactly that kind of side by side review.
- For investors who want financial resilience front and center, start with companies that show strong balance sheets and solid fundamentals using our list of solid balance sheet and fundamentals (25 results).
- If you are hunting for potential mispricing, broaden your watchlist with a 32 high quality undervalued stocks that combines quality metrics with attractive valuations.
- Income focused readers who care about consistency and payout strength can scan a curated set of 6 dividend fortresses that prioritise yield and stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com