
AMC Global Media Early Buyers Backed The Harder Case Not Revenue
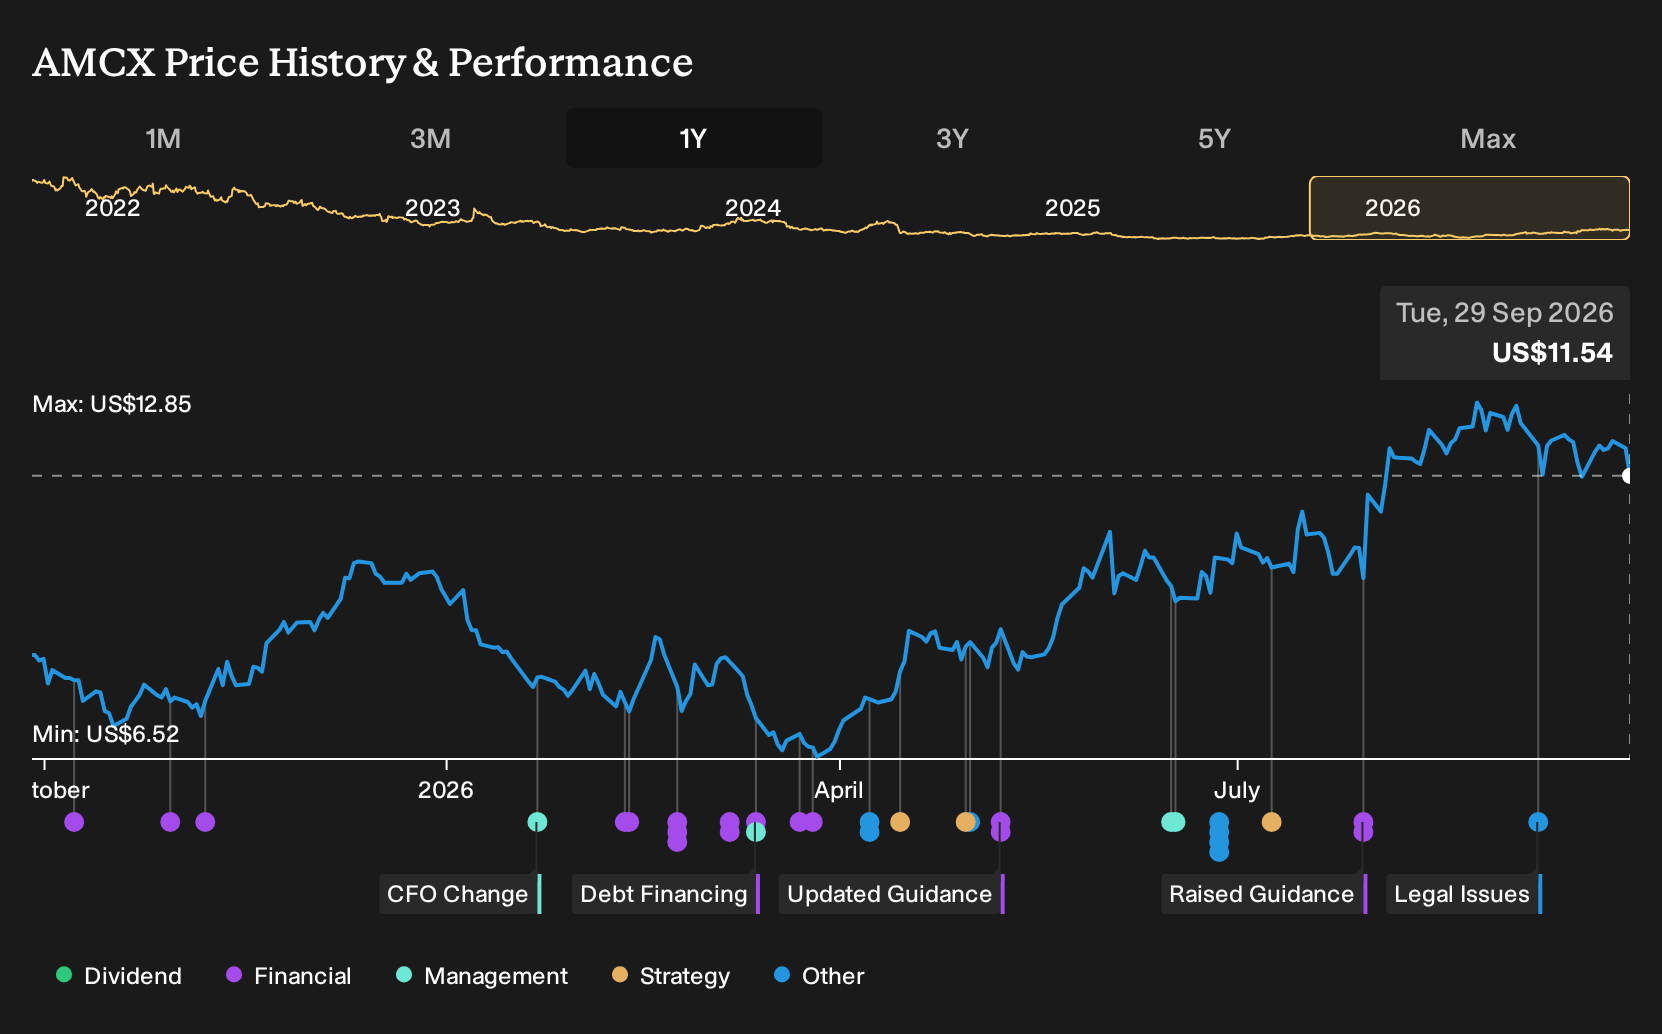
If AMC Global Media sat on your watchlist instead of in your portfolio, the result may feel like a punch. Investors who held AMC Global Media over the past year are up 40.0%, including dividends. That gain landed even as the most recent quarterly report showed lower revenue and a swing from profit to loss. So what early belief about streaming growth and targeted digital ads, recorded before September 2025, might have helped you spot that upside potential?
If the move has made AMC Global Media harder to judge, start where the gap is still open and scan 32 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On AMC Global Media
The shares cost US$8.34 at the start of the period, and AMC Global Media sat between two very different stories about where streaming and digital ads might take the group.
The bullish case pointed to a Fair Value of US$10, a price that would only make sense if shrinking revenue at about 2.1% a year still came with margins rising from a loss of 7.4% to a 6.2% profit by 2028.
The more cautious view saw Fair Value at US$6.5, based on revenue falling about 4% a year and margins improving only to 3.4%, with modest 2% streaming subscriber gains treated as a key risk.
What The Results Changed For AMC Global Media
The clearest test of the AMC Global Media thesis came from profitability. Quarterly net income moved from a profit of US$50.289 million in Q2 2025 to a loss of US$21.943 million in Q2 2026, and net margin fell from 8.4% to 4.0% in the red. That shift challenged both the optimistic margin recovery story and the more cautious improvement path, so the evidence cut both ways.
The key assumption here was that streaming and digital ads would show up in better margins. When you look at another media stock, track not just revenue but the net margin trend in each report and check whether it lines up with any promised efficiency or monetisation gains.
What AMC Global Media’s Price Already Implies
AMC Global Media now trades at US$11.54, while this Narrative’s Fair Value sits below the current price based on its own modelling and assumptions. The argument leans on pressure from cord-cutting, aging franchises and intense streaming competition, even with extra licensing cash in the mix.
A buyer at today’s price is effectively backing durable streaming, licensing and digital ad economics. The question is how that stacks up against the Narrative’s concern that secular TV and content cost pressures could erode those cash flows over time.
"Shrinking pay-TV subscribers and overreliance on aging franchises threaten revenue, as streaming growth and digital ads cannot fully offset traditional declines. Limited scale and rising content costs, combined with intense competition from larger platforms, continue to pressure margins and hinder long-term growth."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Where Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 37% below our estimate - targets complex offshore gas developments as new deepwater regions attract investment.
- Company 2 - 25% below our estimate - sells GPUs and software that many AI data centre customers treat as default.
- Company 3 - 48% below our estimate - advises on failures in complex products where regulators and courts require human experts.
Three companies from the same screener. Open every one of the 25 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com